


Why Hershey (HSY) Is Back In The Spotlight
Hershey (HSY) drew fresh attention after reporting quarterly revenue of $2.79b, up 6.6% year on year, with results ahead of analyst expectations for sales, organic growth, and gross margins.
Despite the upbeat revenue and margin surprise, Hershey’s share price has drifted, with a 30-day share price return down 9.65% and a year-to-date share price return down 7.65%. The 1-year total shareholder return has declined 9.02%, pointing to fading momentum after earlier long-term gains.
Scan how Hershey’s results compare with other resilient consumer stocks by jumping into our hand-picked list of 30 resilient stocks with low risk scores that are poised for steadier returns and fewer surprises.
Hershey just delivered stronger revenue and margins while the share price has slipped and now trades at a discount to analyst targets and some intrinsic value estimates. Does that mix still tilt the risk reward toward buyers?
Most Popular Narrative: 113% Overvalued
On the narrative view, Hershey screens as heavily overpriced, with a fair value of $79.25 against a last close of $168.46, even as recent results looked solid on the surface.
A fortress brand and scale position in U.S. confectionery (Reese’s, Hershey’s, Kisses) generates ~23% through-cycle ROIC and exceptionally durable free cash flow that fell only ~13% even in the worst input-cost year on record. The 2025 cocoa shock, a ~60% GAAP EPS collapse driven largely by non-cash hedge mark-to-market, obscured an underlying cash engine that remained intact. The forward thesis rests on three assumptions: that cocoa is structurally elevated but normalizing, allowing operating margin to recover toward a ~24% ceiling over the decade; that the One Hershey strategy extends the moat into salty, functional, and international adjacencies to sustain mid-single-digit (~3.5%) revenue growth; and that GLP-1 demand erosion remains a slow overhang rather than a cliff. The binding constraint is growth, not quality: this business protects the downside far better than it compounds the upside. The question is not whether Hershey is a great business (it is), but whether the price pays you to own a slow-growing, extraordinarily predictable one.
See why 6 investors see Hershey as 113% overvalued.
Result: Fair Value of $79.25 (OVERVALUED)
Still, the Hershey story could crack if cocoa costs stay elevated for longer or if GLP-1 driven appetite changes hit confectionery demand harder than expected.
Find out about the key risks to this Hershey narrative.
Another View: Hershey Through A Cash Flow Lens
Where the user narrative sees Hershey as heavily overpriced, our DCF model tells a different story. On that framework, HSY at $168.46 is trading about 43.7% below an estimated future cash flow value of $299.20, which frames the stock as materially undervalued instead.
This gap between a cash flow based estimate and the $79.25 narrative fair value leaves investors with a practical question. Is the market more likely to lean toward cash generation and brand durability, or toward slower forecast growth and richer P/E multiples over time?
Look into how the SWS DCF model arrives at its fair value.Look into how the SWS DCF model arrives at its fair value.
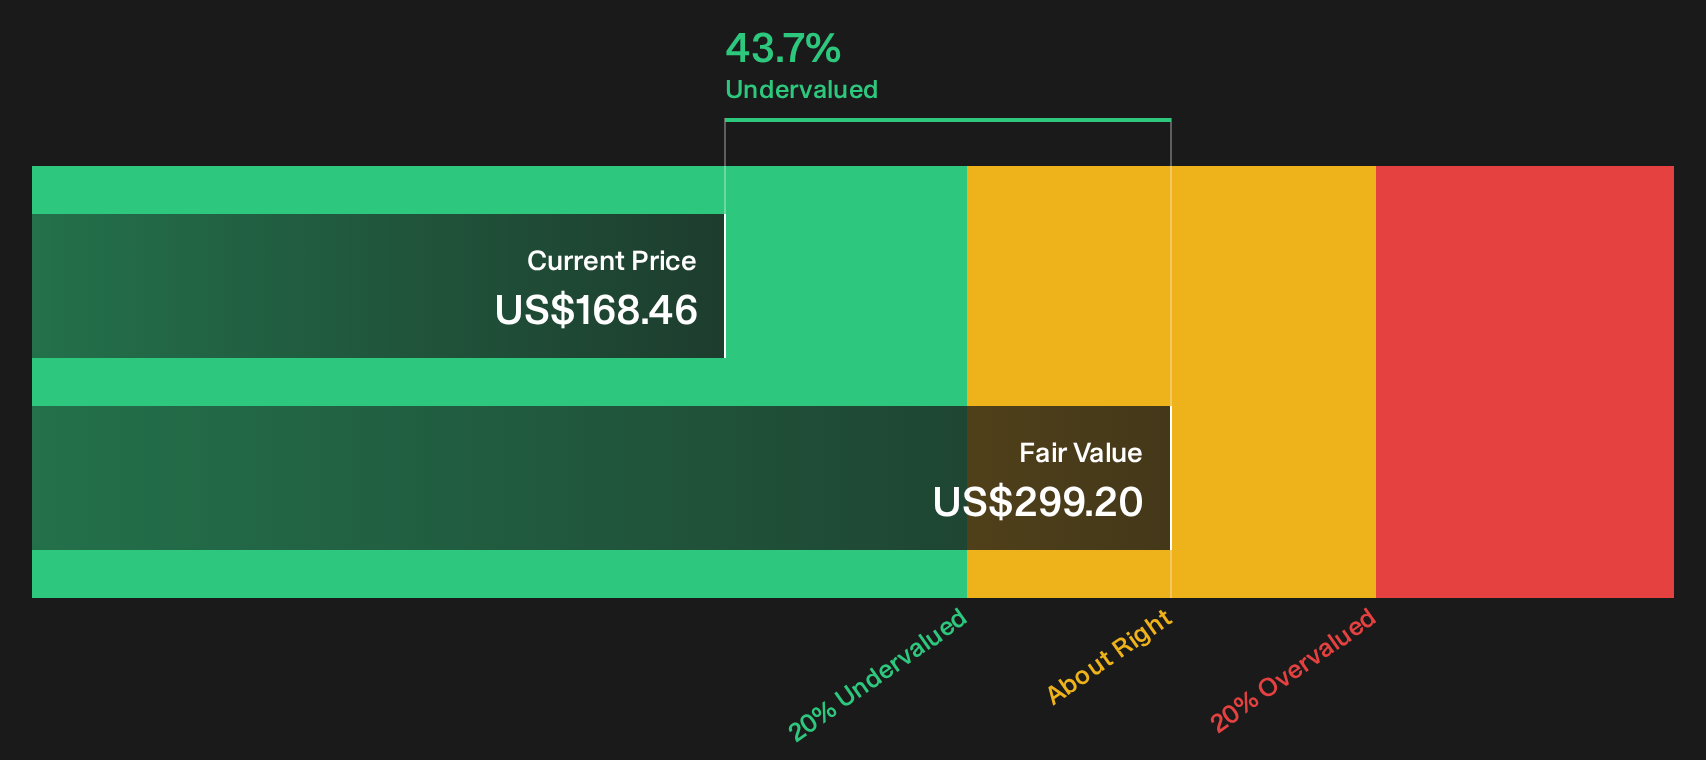
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hershey for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Hershey can tempt you to lean on headlines instead of the data. Act quickly, review both the upside and the concerns, and weigh the 4 key rewards and 1 important warning sign.
Ready To Find More Ideas Beyond Hershey?
Do not stop at Hershey. Use the Simply Wall Street Screener to quickly surface fresh stock ideas that fit your goals before the crowd pays attention.
- Chase potential mispricing by scanning a focused universe of quality companies that currently look cheap on fundamentals through the 29 high quality undervalued stocks.
- Strengthen your income stream by hunting for reliable payers in the 7 dividend fortresses that combine higher yields with solid financial footing.
- Step ahead of the herd by filtering for financially sound businesses using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com