


CoreCivic (CXW) Stock May Be Overvalued Given Its Earnings Base
CoreCivic has seen its share price move sharply over recent years, which puts a spotlight on a simple question for anyone looking at the stock today: Is the current valuation supported by the earnings the business is generating?
- Over the past 5 years, CoreCivic has delivered a total return of 262.1%, which raises the issue of how much of that performance is grounded in its profit profile.
- The company’s model of operating correctional and detention facilities ties its earnings power closely to contract terms, occupancy levels and cost controls, which can affect how durable any current profit base really is.
- Your read on CoreCivic is one view; the desks covering it have another. See what analysts think CoreCivic's shares could be worth.
The issue now is whether CoreCivic’s recent share price, including the latest close at US$31.47, is adequately explained by the earnings investors are paying for.
If you are weighing whether CoreCivic’s earnings justify its recent share price, it can help to compare that question across 29 high quality undervalued stocks.
Has CoreCivic Run Too Far on Earnings?
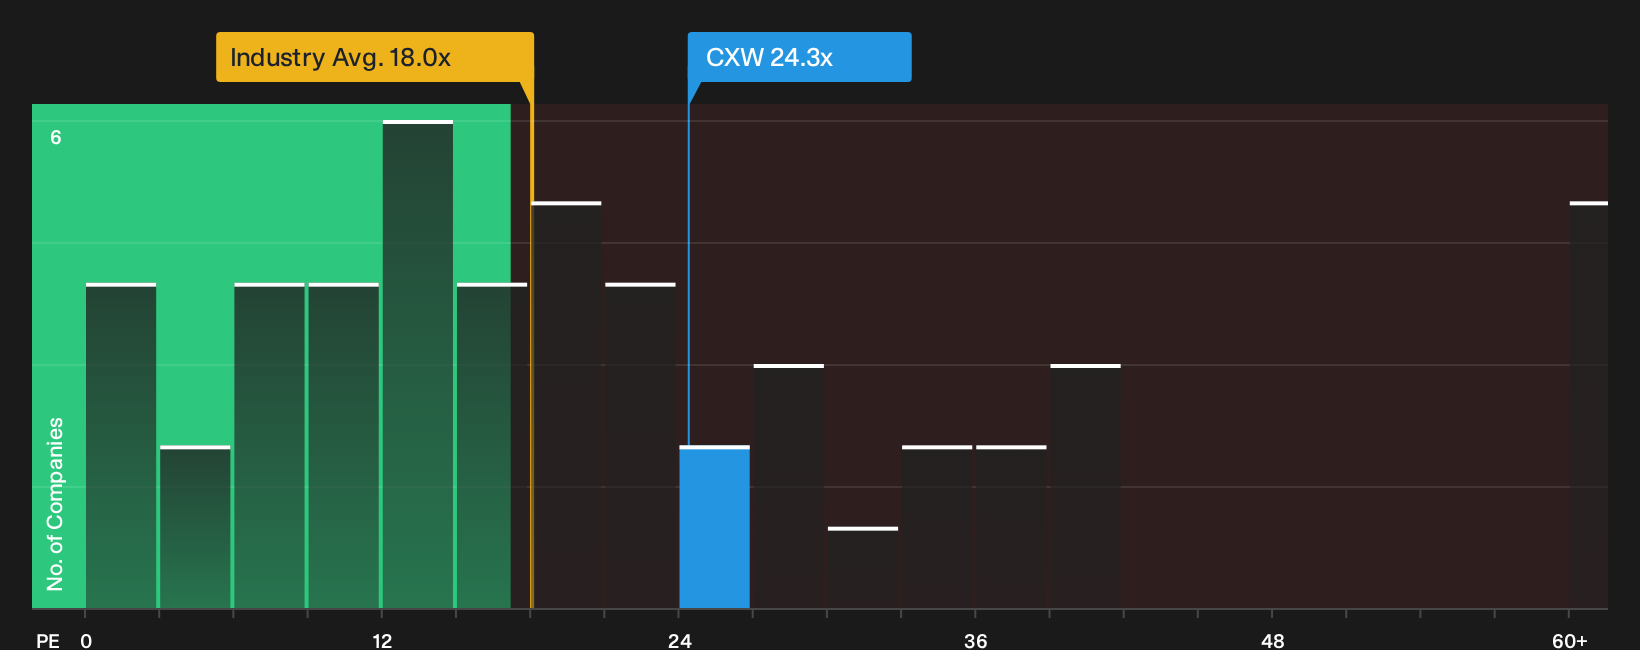
The P/E ratio is a natural fit for CoreCivic because investors often focus on the earnings flowing from its facility contracts. On this measure, the stock trades on about 24.3x earnings, compared with roughly 18.6x for its peer group and about 18.0x for the wider Commercial Services space. That puts a clear premium on each dollar of profit relative to many other listed service providers.
The fair value framework that blends CoreCivic’s growth profile, profitability, size and risk points to a lower P/E than where the shares change hands today. This signals the stock screens as overvalued on this metric. For anyone considering the shares, the key question is whether the contract structure, occupancy outlook and cash generation are strong enough to justify paying well above what this model suggests for the current earnings base. Explore the numbers behind CoreCivic's P/E valuation.
The CoreCivic Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for CoreCivic pick up where the valuation puzzle leaves off and explain which paths for future growth, margins and earnings would need to occur for the shares to be worth materially more or less than today’s price. Each scenario links a fair value to a clear storyline about CoreCivic’s potential catalysts and pressure points, allowing you to track over time which version appears closest to reality on the Community page.
One of the top community narratives on CoreCivic: 25% undervalued
"CoreCivic's extensive portfolio of ready-to-activate idle facilities, combined with preemptive investments in staffing and transportation assets, positions the company to quickly capture additional contract awards..."
Discover why this Narrative puts CoreCivic at 25% undervalued.
One more CoreCivic check that sits outside the valuation math
Price and earnings only tell part of the CoreCivic story, since our broader review also flags company specific concerns that could matter a lot for anyone weighing the shares. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com