


Timken (TKR) Pullback Puts Its Tariff And Margin Recovery Valuation Story In Focus
Timken (TKR) has drawn fresh attention after recent share price moves, with the stock up about 0.6% at the latest close but down roughly 8% over the past month.
Recent trading has been choppy for Timken, with the 30-day share price return down 7.66% and the 90-day move down 16.28%, even though the year-to-date share price return is 33.87% and the 1-year total shareholder return is 52.57%. This points to strong longer-term momentum that has cooled in the short term as investors reassess growth prospects and risk.
Compare Timken's recent pullback with hand-picked industrial peers by scanning the list of solid balance sheet and fundamentals (23 results) that have held up through similar bouts of volatility.
Timken now trades in an awkward middle ground, with the recent pullback on one side and a wide gap to analyst and intrinsic value estimates on the other. Where does fair value really land in that spread?
Most Popular Narrative: 22% Undervalued
Timken's most followed valuation story pegs fair value at about $147.75 per share versus the recent $115.52 close. This frames the recent pullback as a gap between price and what analysts think the business is worth on cash flows and margins.
Timken is implementing a pricing strategy to offset the cost impact of tariffs, which is expected to fully mitigate the direct impact from tariffs on a run-rate basis by the end of the year. This proactive approach should help maintain and eventually improve net margins.
See why 4 investors see Timken as 22% undervalued.
The most widely followed narrative uses a discount rate of 8.98% and a forecast net profit margin of 11.86% to arrive at a fair value estimate of $147.75, which sits well above both the last close and the current price implied by the recent sell off. That framework treats Timken as a business with moderate revenue growth of about 3.4% a year and much faster earnings expansion as margins recover from one off items and management follows through on its cost program.
The same storyline also assumes earnings power can grow meaningfully from the current $258.7m base, with analysts expecting higher profitability to do more of the heavy lifting than top line expansion. That is a different profile from high growth stocks that lean mostly on rapid sales gains, and it leaves more of the valuation case resting on execution of pricing, cost savings and portfolio moves in the automotive OEM arm.
Balancing that, the narrative does not ignore risks such as softer organic revenue, tariff costs of roughly $25m and a recent step down in adjusted EBITDA margins from 20.7% to 18.2%. These factors could all affect how quickly those margin targets are reached. For readers weighing the numbers, the key tension is whether the market is overreacting to recent earnings noise or underestimating the path to the higher profitability embedded in that $147.75 figure.
Result: Fair Value of $147.75 (UNDERVALUED)
Still, Timken's recent 3% organic revenue decline and lower 18.2% adjusted EBITDA margin could challenge the margin recovery story that investors are leaning on.
Find out about the key risks to this Timken narrative.
Another View on Timken’s Valuation
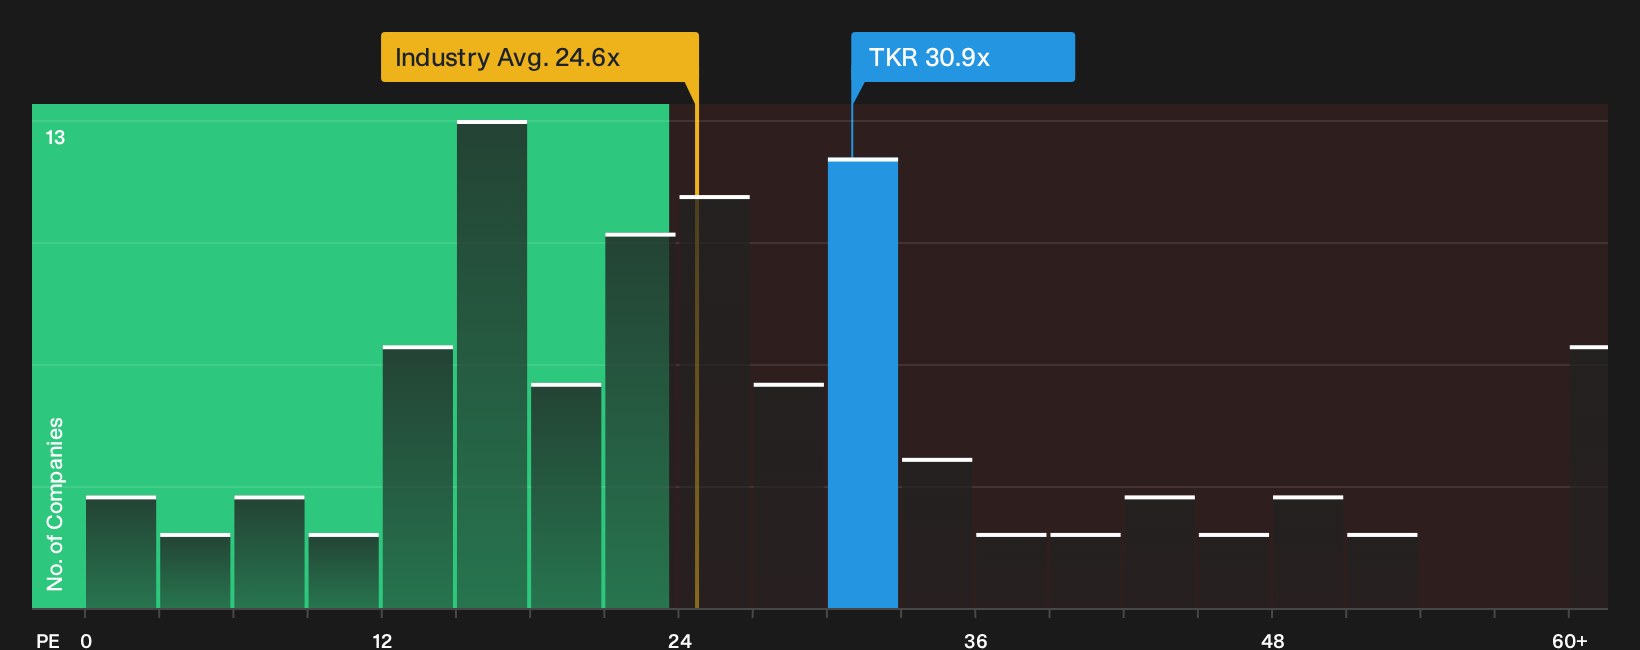
Timken screens as cheap on cash flows, with the SWS DCF model suggesting fair value around $179.35 per share versus the recent $115.52 price, which points to a sizeable undervaluation. Yet the shares trade on a 30.9x P/E, richer than the US Machinery industry at 24.3x and peer average of 15x, and only slightly below a 32.8x fair ratio. That mix of a discounted DCF and premium earnings multiple leaves a simple question for investors: Is the market underestimating long term cash generation, or overpaying for near term earnings?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Timken's recent swing in sentiment are clear, so move quickly, review the full picture and weigh it against your own risk tolerance. To see both sides of the story in one place, start with 3 key rewards and 3 important warning signs.
Looking For More Ideas Beyond Timken?
Do not stop with Timken. Broaden your watchlist and pressure test your thesis by lining it up against other opportunities that fit clear, data backed filters.
- Target potential upside by scanning a curated pool of companies that screen as priced below their fundamentals using the 29 high quality undervalued stocks.
- Prioritize resilience and capital preservation by sorting through a 30 resilient stocks with low risk scores that focuses on businesses with steadier risk profiles.
- Spot lesser known opportunities before they gain wider attention by reviewing a 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com