


Why Hilltop Holdings (HTH) Is Back In The Spotlight
Hilltop Holdings (HTH) has drawn fresh attention after recent trading, with the share price closing at US$38.38 and short term returns softening over the past week and month.
Recent softness has taken some heat out of Hilltop Holdings’ momentum, with the share price return easing over the past quarter. Yet the year to date gain of 13.22% and a 1 year total shareholder return of 15.99% keep the longer trend positive, supported by a 3 year total shareholder return of 47.70%.
Compare Hilltop Holdings to a curated 30 resilient stocks with low risk scores that also aims for steadier returns and stronger balance sheets.
Hilltop Holdings has cooled off after a solid run, which leaves a simple question hanging over the current US$38.38 price. Does the recent pause improve the risk reward, or has the easier upside already been taken?
Most Popular Narrative: 3% Undervalued
Hilltop Holdings last closed at $38.38, while the most followed narrative places fair value around $39.67, leaving only a small valuation gap but a very clear set of drivers that matter more than the headline number.
Continuing growth and strong demand for loans in Texas and across the Sun Belt, fueled by population gains and robust economic conditions, are expected to drive increases in lending volume and recurring revenue streams as Hilltop's loan pipeline remains healthy and pipelines in commercial lending continue to expand. The ongoing shift toward digital financial services allows Hilltop to gain operational efficiencies and lower operating costs, as management focuses on further digital investments and improving customer analytics, leading to better efficiency ratios and expanded net margins over time.
See why 1 investors see Hilltop Holdings as 3% undervalued.
Result: Fair Value of $39.67 (UNDERVALUED)
Still, the narrative around Hilltop Holdings can weaken quickly if mortgage origination stays under pressure or if competition in core Texas markets squeezes lending margins.
Find out about the key risks to this Hilltop Holdings narrative.
Another View on Hilltop Holdings Valuation
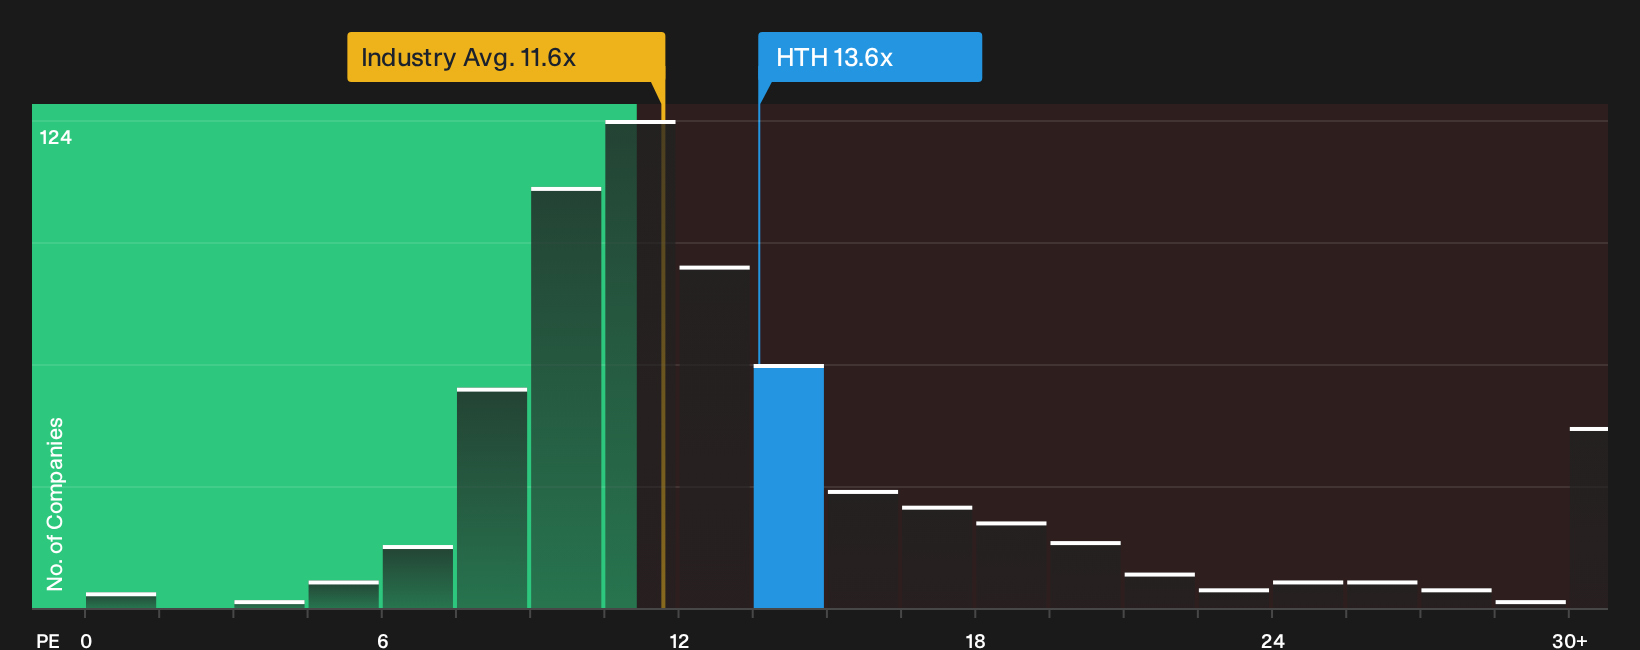
On simple P/E terms, Hilltop Holdings trades at 13.6x earnings. That is higher than both the US Banks industry on 11.7x and its peer group on 10.8x, and also above an estimated fair ratio of 8.5x. The gap points to valuation risk if sentiment cools further.
See what the numbers say about this price in our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Hilltop Holdings is mixed right now, with both bright spots and pressure points in focus, so move quickly and review the evidence yourself, then weigh up the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Hilltop Holdings?
If Hilltop Holdings has your attention, do not stop here. Broader context can help refine decisions, and skipping other ideas could mean overlooking a better fit.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (23 results) tailored for investors who want financial strength front and center.
- Hunt for quality at a reasonable price with a focused 29 high quality undervalued stocks that filters for strong fundamentals paired with potentially appealing valuations.
- Prioritize income and stability by reviewing a hand picked 7 dividend fortresses designed for those who care about yield and staying power together.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com