


Haemonetics (HAE) Following Margin Expansion Narrative Looks Fairly Valued
Haemonetics (HAE) has attracted fresh attention after a recent move in the share price, with the stock closing at $108.52 on 21 September 2026. Investors are weighing that level against recent returns.
The recent pullback of 0.19% on the day follows a strong run, with Haemonetics posting a 48.92% 90 day share price return and a 35.68% year to date share price gain. The 1 year total shareholder return of 114.25% points to momentum still building.
Scan how Haemonetics compares with other potential momentum plays by reviewing the hand picked 29 high quality undervalued stocks that may offer similar strength with different risk profiles.
Haemonetics now trades only slightly below the average analyst target, yet at a much steeper discount to some fair value estimates. Is that gap cautious pricing, or a misread of the business after this surge?
Most Popular Narrative: Fairly Valued
Haemonetics is now trading almost exactly in line with the most widely followed fair value estimate of $108.40, which uses a 7.9% discount rate and builds in specific assumptions about future growth and margins.
Enterprise-wide portfolio transformation highlighted by the divestiture of low-margin businesses, disciplined capital deployment, and ongoing investment in automation and digital solutions is driving substantial gross and operating margin expansion (guidance of 26 to 27% for FY26) and is likely to support further improvements in net margins and free cash flow conversion.
See why 8 investors see Haemonetics as 0% overvalued.
Result: Fair Value of $108.40 (ABOUT RIGHT)
Still, concentrated exposure to NexSys, TEG and VASCADE, along with a largely U.S. focused footprint, leaves Haemonetics vulnerable if competition or regulation turns quickly.
Find out about the key risks to this Haemonetics narrative.
Another View on Haemonetics’ Valuation
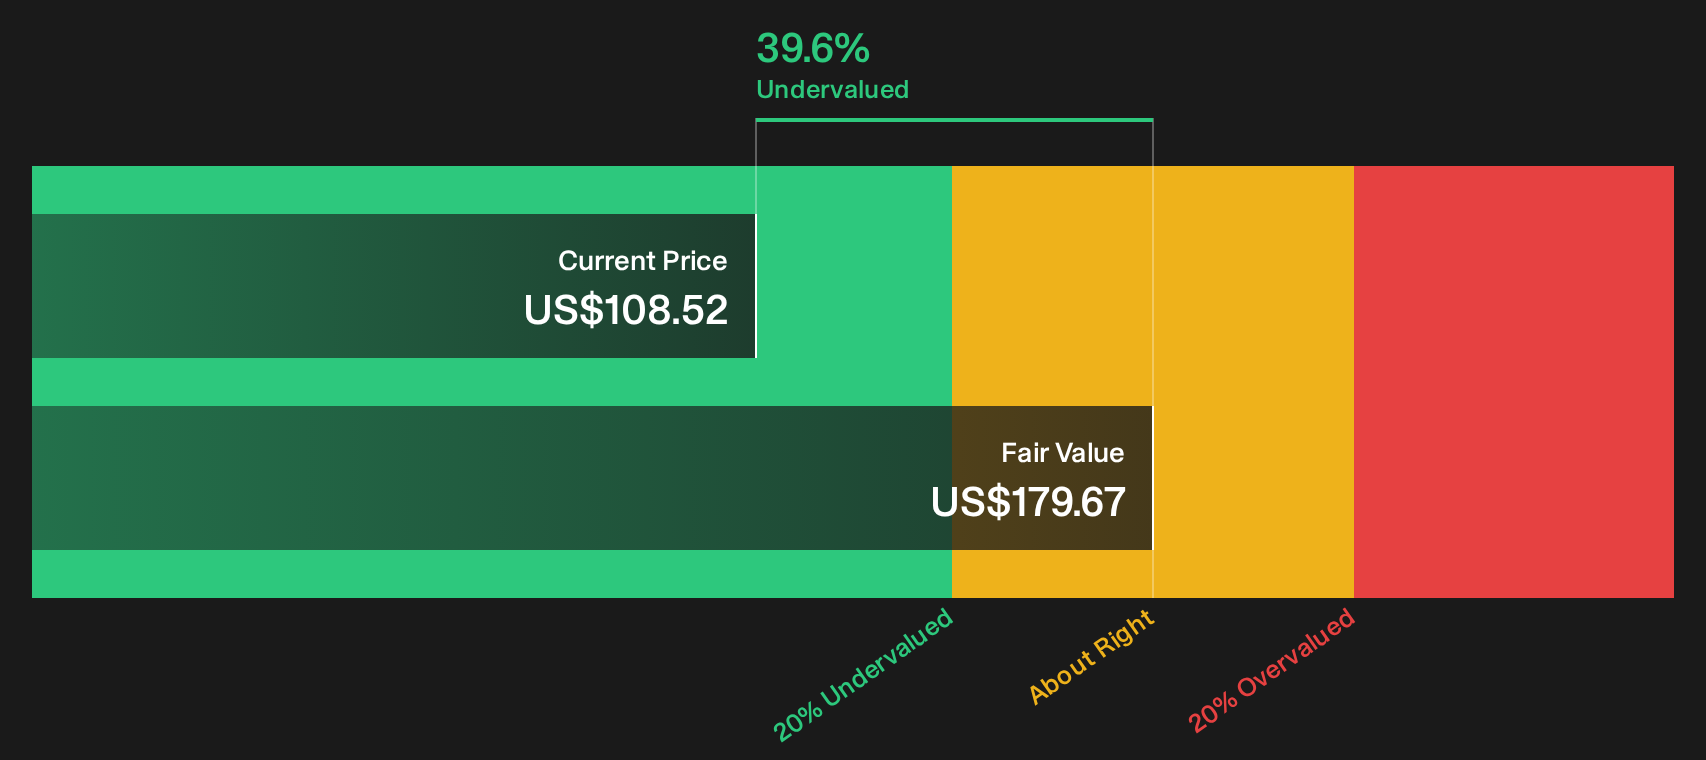
While the analyst fair value of $108.40 points to Haemonetics being roughly in line with expectations, the SWS DCF model presents a different view. On that framework, the stock at $108.52 is trading about 40% below an estimated future cash flow value of $179.67. Which set of assumptions do you trust more?
For a clearer sense of how this cash flow lens works in practice, take a closer look at the SWS DCF model and how it treats Haemonetics’ long term earnings power: Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages in the Haemonetics story so far. If you want to move quickly and shape your own view, weigh up the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Haemonetics?
If Haemonetics has sharpened your focus on valuation and quality, do not stop here. Use the Simply Wall St Screener to spot fresh opportunities, compare business strength in minutes, and keep your watchlist stacked with ideas before everyone else catches on.
- Target sturdier businesses first by scanning a list of solid balance sheet and fundamentals (23 results) that can help you filter for financial resilience before you commit capital.
- Hunt for mispriced opportunities with a 29 high quality undervalued stocks that highlights companies where quality, cash flows, and balance sheet strength line up.
- Surface potential future market favorites early by working through a 16 high quality undiscovered gems that focuses on under-the-radar stocks with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com