


3 UK Growth Stocks With High Insider Ownership And Up To 48% Earnings Growth
As the UK market grapples with global economic challenges, such as weak trade data from China impacting the FTSE 100 and 250 indices, investors are increasingly seeking growth stocks that demonstrate resilience. In this context, companies with high insider ownership can offer a compelling proposition, as they often align management interests with shareholder value and may be better positioned to navigate turbulent times.
Top 10 Growth Companies With High Insider Ownership In The United Kingdom
| Name | Insider Ownership | Earnings Growth |
| TEAM (AIM:TEAM) | 32% | 85.3% |
| RentGuarantor Holdings (AIM:RGG) | 39.7% | 87.7% |
| Quantum Base Holdings (AIM:QUBE) | 31.8% | 111.8% |
| Mortgage Advice Bureau (Holdings) (LSE:MAB1) | 18.3% | 22.4% |
| Metals Exploration (AIM:MTL) | 15.9% | 86.7% |
| Hochschild Mining (LSE:HOC) | 38.3% | 22.2% |
| Energean (LSE:ENOG) | 19.3% | 32.9% |
| EARNZ (AIM:EARN) | 19.5% | 76.5% |
| Crimson Tide (AIM:TIDE) | 32.5% | 119.1% |
| ActiveOps (AIM:AOM) | 22.2% | 81% |
Here we highlight a subset of our preferred stocks from the screener.
Henry Boot (LSE:BOOT)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Henry Boot PLC, with a market cap of £191.36 million, operates in the United Kingdom's home building sector through its various subsidiaries.
Operations: The company's revenue segments are not specified in the provided text.
Insider Ownership: 26.2%
Earnings Growth Forecast: 30% p.a.
Henry Boot, a UK construction and property development firm, is experiencing challenges with a recent net loss of £2.92 million for H1 2026, down from a profit last year. Despite this setback, the company's earnings are forecast to grow significantly at 30% annually, outpacing the UK market's growth rate. Recent board changes aim to strengthen governance amid these financial adjustments. The firm's strategic projects like Golden Valley indicate potential future growth in innovation sectors critical to national security.
- Delve into the full analysis future growth report here for a deeper understanding of Henry Boot.
- The valuation report we've compiled suggests that Henry Boot's current price could be quite moderate.
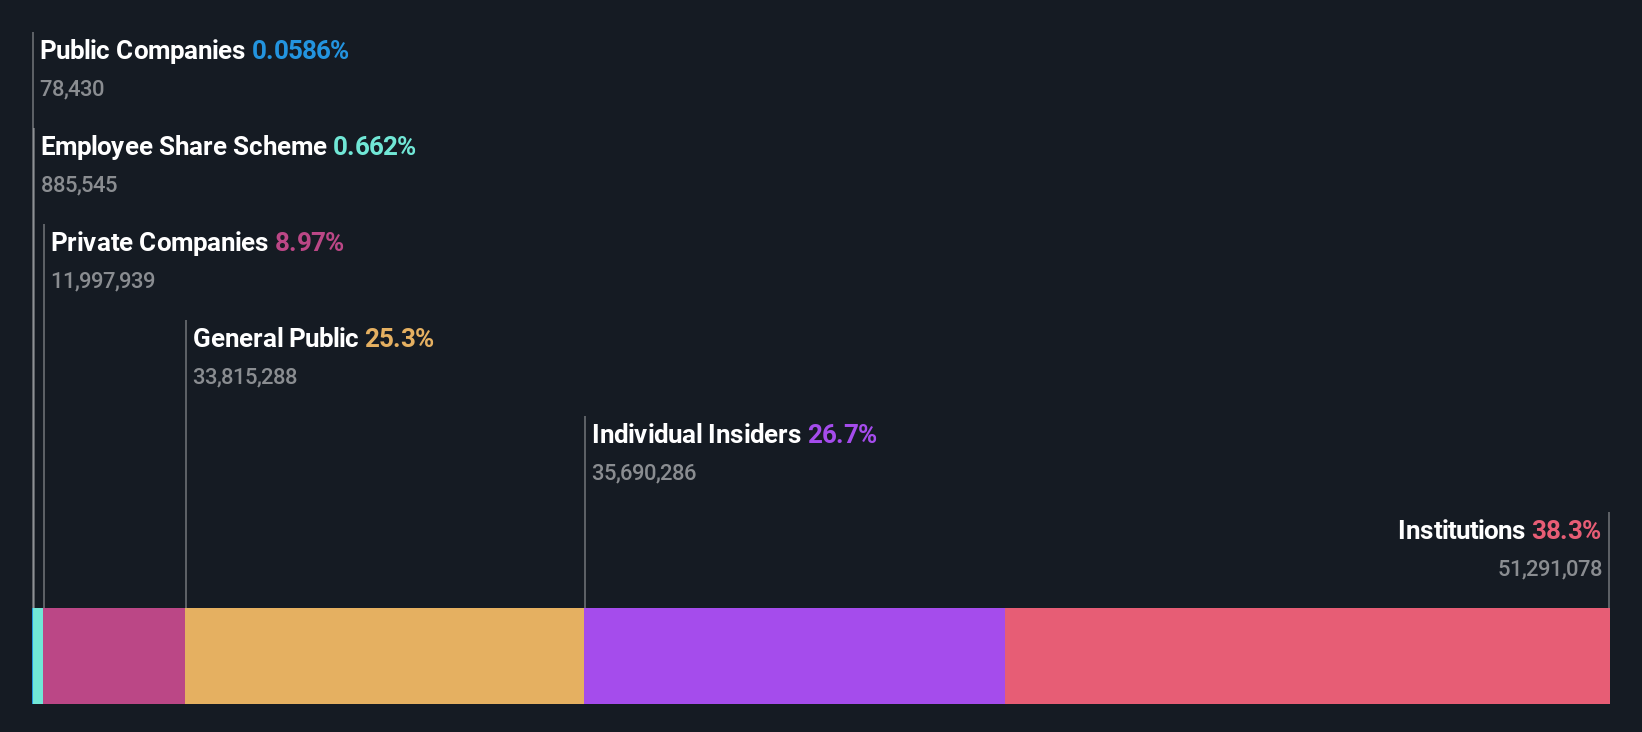
Hochschild Mining (LSE:HOC)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Hochschild Mining plc is a precious metals company involved in the exploration, mining, processing, and sale of gold and silver deposits with a market cap of £3.07 billion.
Operations: The company's revenue segments include $582.84 million from San Jose, $82.87 million from Mara Rosa, and $840.85 million from Inmaculada.
Insider Ownership: 38.3%
Earnings Growth Forecast: 22.2% p.a.
Hochschild Mining, with substantial insider ownership, reported a significant 102.7% earnings growth over the past year and forecasts a robust annual profit increase of 22.2%, surpassing UK market expectations. Despite volatile share prices recently, analysts predict a 23.2% rise in stock value, highlighting its potential undervaluation at 66.1% below estimated fair value. Recent production guidance maintains stable output levels amidst increased cost projections for gold equivalent ounces between $2,380-$2,500 per ounce.
- Navigate through the intricacies of Hochschild Mining with our comprehensive analyst estimates report here.
- Our comprehensive valuation report raises the possibility that Hochschild Mining is priced lower than what may be justified by its financials.
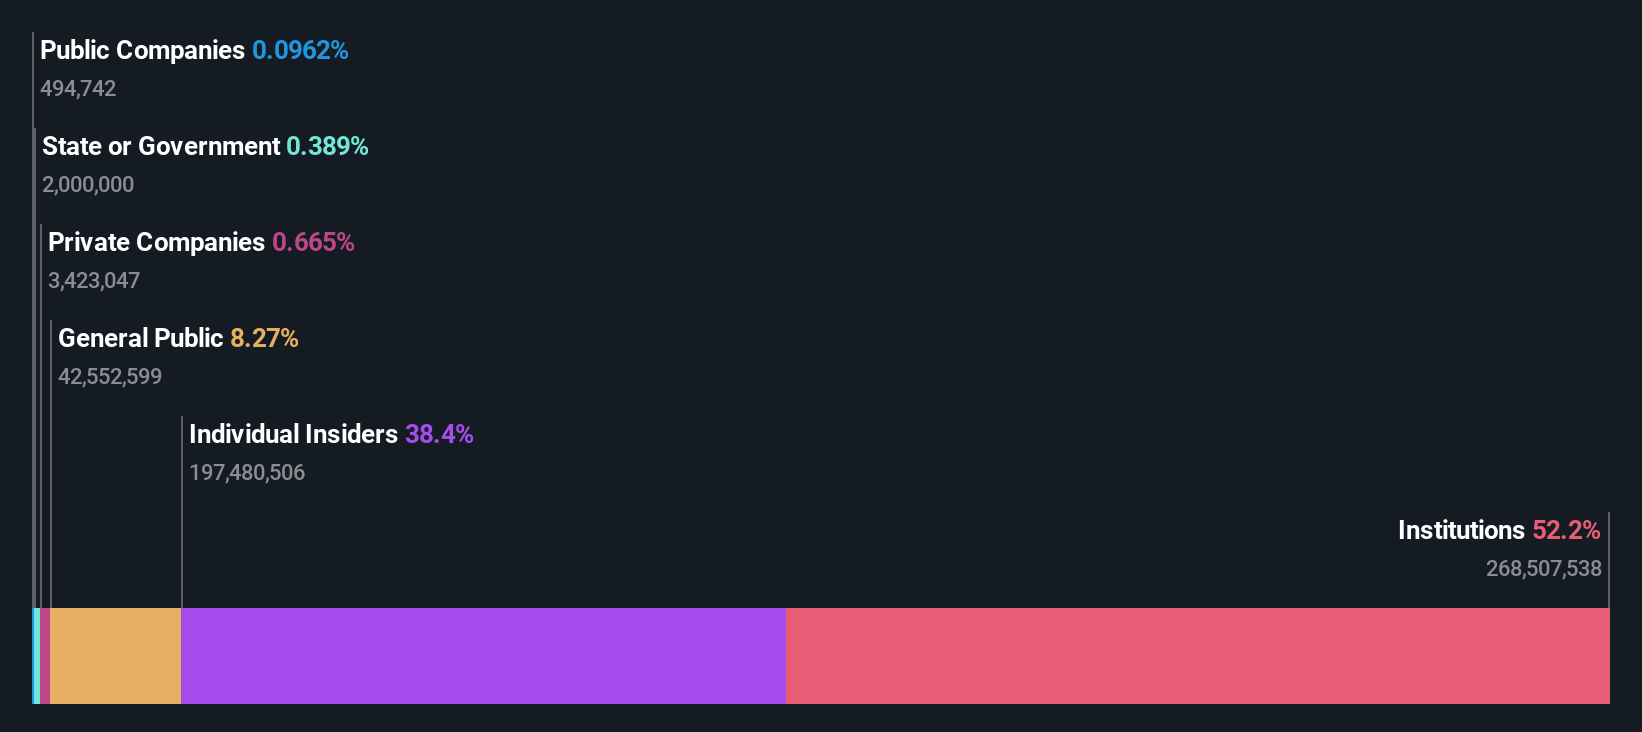
Saga (LSE:SAGA)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Saga plc, with a market cap of £893.08 million, operates in the United Kingdom offering package and cruise holidays, general insurance, and personal finance products and services.
Operations: The company's revenue is generated from various segments, including Insurance Broking (£140.90 million), Travel - Holidays (£185.50 million), Travel - Ocean Cruise (£264 million), and Travel - River Cruise (£53.60 million).
Insider Ownership: 36.5%
Earnings Growth Forecast: 48.6% p.a.
Saga, with substantial insider ownership, is expected to see its earnings grow significantly at 48.6% annually over the next three years, outpacing the UK market average. However, revenue growth of 5.6% per year lags behind more aggressive targets and interest payments remain a concern. Recent board appointments bring strategic expertise in consumer sectors to drive brand differentiation and customer growth, potentially enhancing Saga's competitive position as analysts anticipate a 48.2% stock price increase.
- Click to explore a detailed breakdown of our findings in Saga's earnings growth report.
- In light of our recent valuation report, it seems possible that Saga is trading behind its estimated value.

Where To Now?
- Reveal the 60 hidden gems among our Fast Growing UK Companies With High Insider Ownership screener with a single click here.
- Ready To Venture Into Other Investment Styles? Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com