


Cronos Group Stock And 2 Canadian Penny Stocks With Strong Balance Sheets
Canada’s smaller stocks are trading against a backdrop of higher interest rates after the US Federal Reserve lifted its benchmark again, which keeps a global spotlight on balance sheet strength and funding costs. That puts financially disciplined Canadian penny shares in a different category than highly speculative flyers. This article walks through three such low-priced companies that pair modest share prices with a focus on financial health.
The three featured stocks below are only a small sample of what “financially fit” can look like at the penny end of the market. The full screen surfaces 344 more companies that carry equally detailed narratives on their balance sheets, risks, and funding profiles. To see that broader universe in one place, head straight into the Financially Fit Penny Stocks screener to identify ideas, analyze financial strength, and focus on the penny shares that best match your risk tolerance.
Cronos Group (TSX:CRON)
Overview: Cronos Group is a cannabinoid business that produces and sells branded cannabis products like dried flower, vapes, edibles, and oils.
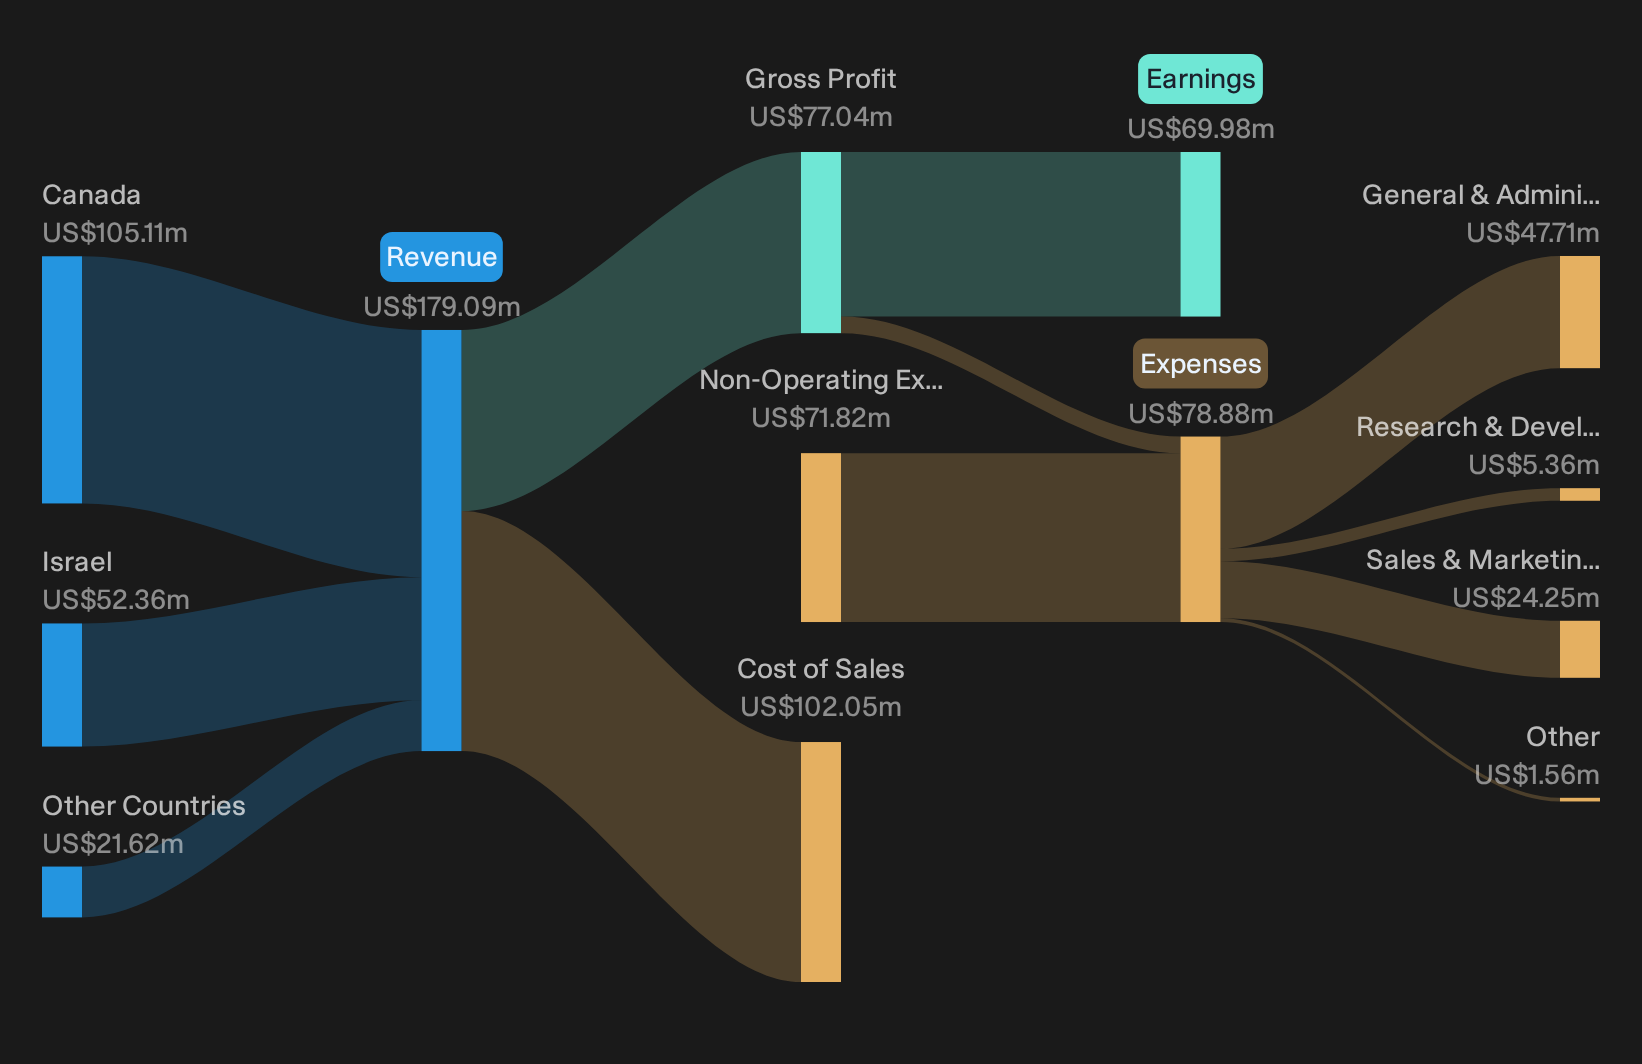
Operations: Cronos Group generates about $179 million from cultivating, manufacturing and marketing cannabis products, primarily in Canada with meaningful sales in Israel.
Market Cap: CA$1.7b
Cronos Group fits the Financially Fit Penny Stocks theme because its cannabis brands convert directly into real-world sales that support financial health and give the business room to fund growth from tangible demand rather than pure speculation.
"The strength and breadth of premium brands (Spinach, Lord Jones, PEACE NATURALS) across flower, vapes, edibles, and concentrates, coupled with industry-leading market shares in high-margin categories, point to sustainable pricing power and enduring consumer loyalty, supporting continued gross margin improvement and resilient long-term earnings growth."
What happens if a single pressure on those margins shifts at the same time as expectations for future earnings cool?
If that margin pressure ever bites, read the full narrative for Cronos Group to see how Cronos Group’s cash, capital allocation and category mix could still keep earnings momentum accelerating.
Omai Gold Mines (TSXV:OMG)
Overview: Omai Gold Mines focuses on acquiring, exploring, and developing its 100%-owned Omai gold project in Guyana as an early-stage precious metals developer.
Market Cap: CA$1.75b
Omai Gold Mines offers pure gold exploration exposure through its under $5 stock and single, 100%-owned Guyanese project. It carries high financial risk today given zero revenue, ongoing losses and a short cash runway, so the real interest for Financially Fit Penny Stocks investors sits in how one unresolved funding and development swing factor ultimately lands on this asset.
That funding swing factor is exactly what the analysis report for Omai Gold Mines unpacks, showing where balance sheet strain could flip into leverage on any future drilling success.

McChip Resources (TSXV:MCS)
Overview: McChip Resources is a Toronto based natural resources investor with petroleum holdings and a key Saskatchewan potash project that anchors its Financially Fit Penny Stocks link.
Operations: McChip Resources generates about CA$4 million from oil and gas exploration and production activities in Canada, reflecting a concentrated domestic revenue base.
Market Cap: CA$4.2 million
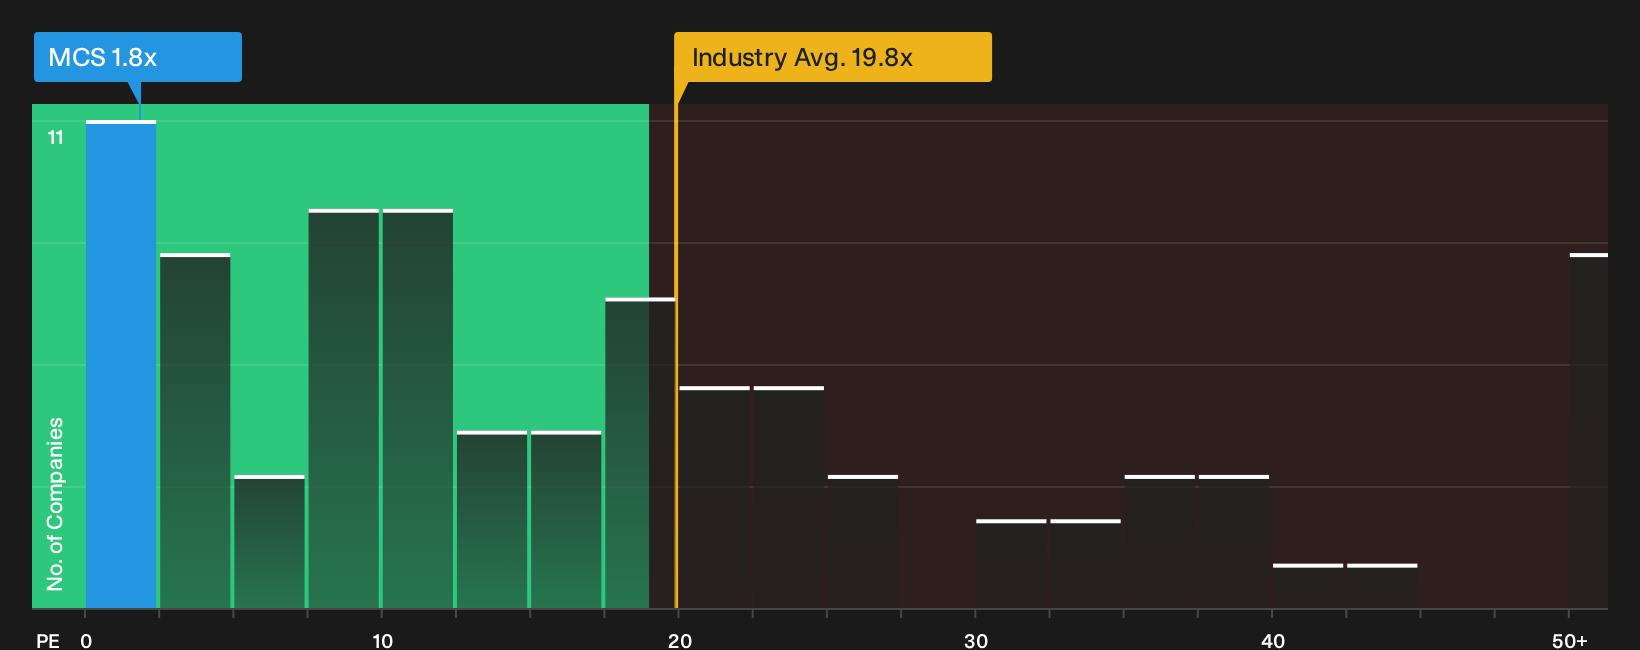
McChip Resources combines a Saskatchewan potash interest with very strong reported profitability metrics and a low P/E of about 1.8x, which is unusual at this size and fits the Financially Fit Penny Stocks angle on earnings quality. However, the impact of any pressure on that small revenue base remains an important consideration.
When that kind of tiny revenue base meets a 1.8x P/E, the 2 key rewards and 3 important warning signs shows whether McChip Resources’ earnings quality is a margin trap or an overlooked engine.
Curious About What You Might Be Missing?
Fresh ideas tend to move first. By the time every ticker is flying, the quiet phase is gone. Scan these under the radar for now opportunities while it matters and consider getting in early.
- Target reliable cash generators that still offer yield potential by scanning a curated mix of potential 1 dividend fortresses before income hunters crowd in.
- Spot early movers in computing breakthroughs by reviewing carefully filtered 25 quantum computing stocks while market attention is still catching up.
- Track potential future grid workhorses by assessing hand picked 40 power grid technology and infrastructure stocks before infrastructure momentum is fully reflected in prices.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com