


VNET Group (VNET) Stock May Trade At A Discount After Its 142% Run
VNET Group has seen its share price swing sharply in recent years, which puts fresh attention on a simple question for anyone looking at the stock today: how much sales back up that US$7.15 price tag.
- Over the past 3 years the share price has gained 141.6%, which puts a lot of weight on whether the underlying revenue base can support that kind of re-rating.
- The recent closing of a large equity investment that leaves the new investor group with about 38.1% of VNET Group may support longer term plans for funding its data center footprint and future sales growth without leaning as hard on public markets.
- There is a second opinion on VNET Group worth weighing. See what analysts think VNET Group's shares could be worth.
The issue now is whether VNET Group's current valuation is adequately supported by its sales when set against the Fair Ratio benchmark.
If you are comparing VNET Group with other data and infrastructure companies, it can be useful to look at its sales-based valuation alongside peers in the 86 AI infrastructure stocks.
Does VNET Group Look Undervalued on Sales?
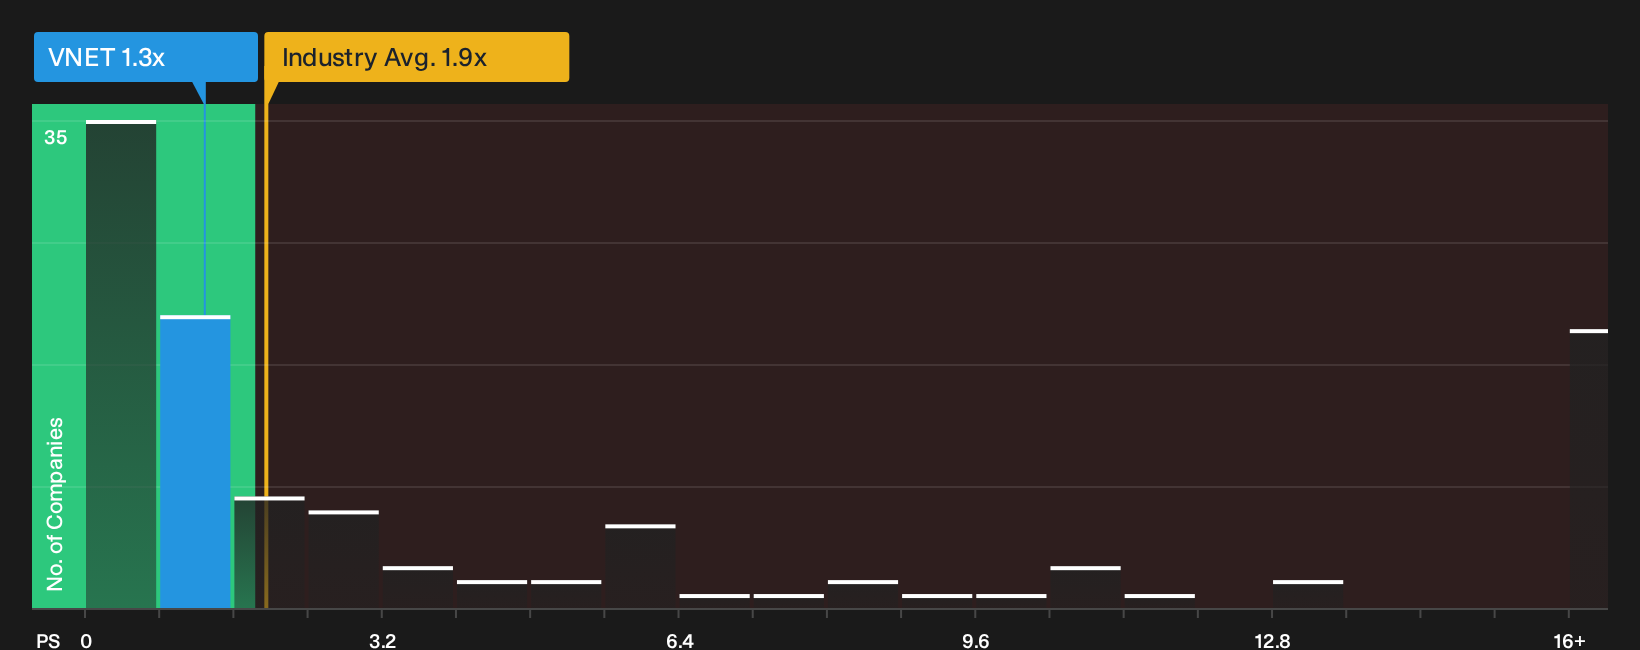
P/S tends to fit VNET Group because investors often frame data center plays around revenue capacity and utilization. At a current P/S of 1.3x, the stock trades below the IT industry average of 1.9x and far under the infrastructure peer group on about 8.4x. This puts a lot of focus on how reliable and repeatable VNET Group's sales base really is.
Because the Fair Ratio adjusts for the firm's growth profile, margins, size and risk, it suggests the present 1.3x P/S screens lower than you might expect on those fundamentals. Despite the recent strategic investment that lifted the new consortium to about 38.1% ownership, the market multiple still prices VNET Group at a discount to peers on headline revenue. That gap only matters if you think the current revenue mix and data center footprint can support stronger cash generation over time, so the P/S alone is just a starting point for judging whether the share price is attractive enough. Explore the numbers behind VNET Group's P/S valuation.
The VNET Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/S puzzle for VNET Group leaves off by spelling out which combinations of revenue growth, profitability and earnings power would need to hold for the current share price to look materially higher or lower. Each scenario links a fair value estimate to a clear storyline about VNET Group's potential catalysts and key risks, so you can later see which version of events is actually unfolding on the Community page.
One of the top community narratives on VNET Group: 49% undervalued
"The partnership with CATL combines VNET Group’s large scale data center development and operations with CATL’s zero carbon new energy technologies…"
Discover why this Narrative puts VNET Group at 49% undervalued.
Before moving on from VNET Group, there is one more factor to weigh
Price, revenue and ownership only tell part of the story for VNET Group. The character of the leadership team and the way their rewards line up with your interests can change the whole picture. See who runs VNET Group and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com