


Darling Ingredients (DAR) Stock May Be Undervalued On Earnings Power
Darling Ingredients has seen a powerful swing in its share price over the past year, and that kind of move naturally puts the focus on what investors are actually paying for in terms of earnings. With the stock coming off a weaker recent patch, the key issue now is how comfortably its current valuation lines up with the profits the business is generating.
- The share price has delivered a 95.5% gain over the past year, which puts a lot of weight on whether that move is backed up by the company’s earnings power.
- The business model turns waste and co-products into higher value ingredients, which can support a view that earnings quality and cash conversion matter as much as headline growth expectations.
- The analysts covering Darling Ingredients have run their own numbers. See what analysts think Darling Ingredients's shares could be worth.
For investors, the debate is whether Darling Ingredients' current share price is justified by its earnings profile when judged against Fair Ratio.
If you want to stress test the same earnings question you are asking of Darling Ingredients across other opportunities, take a look at 29 high quality undervalued stocks.
Does Darling Ingredients Look Undervalued on Earnings?
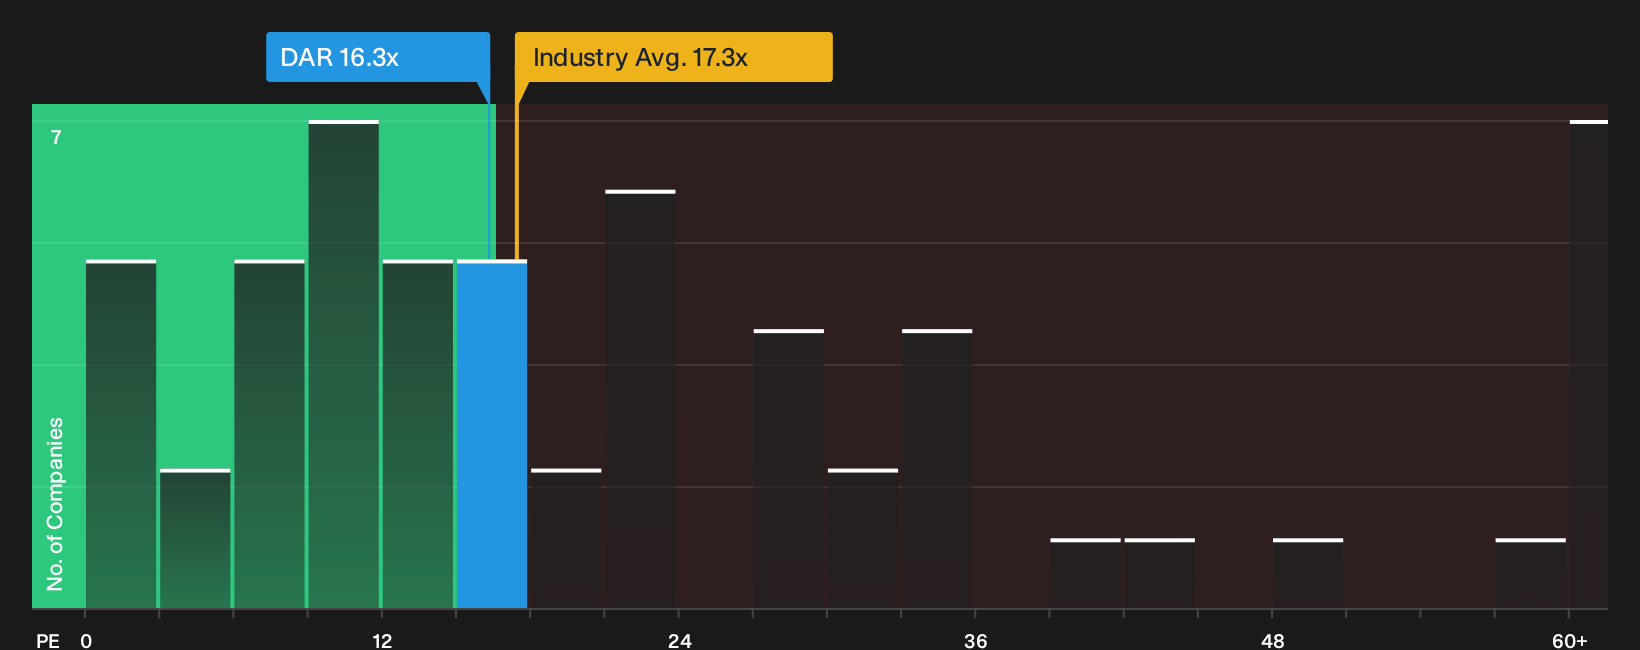
The P/E ratio is a straightforward way to show what investors are paying for each dollar of Darling Ingredients earnings. On this measure, the stock trades on roughly 16.3x, which is slightly below the wider food industry at about 17.3x and well under the peer group closer to 24.4x. That places the shares toward the lower end of the sector’s earnings multiples while still firmly within the range investors often see for established, profitable businesses.
The Fair Ratio model, which adjusts the P/E you might expect for Darling Ingredients by factoring in elements such as its margins, capital intensity, size and risk profile, points to a higher figure than where the stock is now. This leaves the current 16.3x multiple below that tailored benchmark, so the market is pricing the company’s earnings at a discount relative to what this framework suggests could be appropriate. Explore the numbers behind Darling Ingredients's P/E valuation.
The Darling Ingredients Narrative: What Would Justify Today's Price?
Narratives pick up where the Darling Ingredients valuation question leaves off by spelling out which combinations of growth, profitability and earnings would need to hold for the stock to be worth meaningfully more or less than today’s level, based on scenarios discussed on Simply Wall St’s Community page. Rather than leaning on a single multiple or headline model result, each narrative lays out the assumptions behind its view of fair value so you can compare those expectations with actual results as they come through.
One of the top community narratives on Darling Ingredients: 22% undervalued
"Geographic and product diversification, especially through integration in Brazil and expansion in Europe and the U.K., positions Darling to benefit from population growth and rising protein consumption globally..."
Discover why this Narrative puts Darling Ingredients at 22% undervalued.
One more forward-looking check for Darling Ingredients
Price and current earnings only tell part of the story for Darling Ingredients, since professional coverage also sketches out where profits might head over the next few years and gives you another lens to compare with today’s multiples. Explore where analysts expect Darling Ingredients to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com