


Costco Wholesale (COST) Expands On DoorDash, Is The Pullback A Valuation Opportunity?
Costco Wholesale (COST) has expanded its reach through a nationwide launch on the DoorDash Marketplace, giving members same-day access to thousands of warehouse items and adding a fresh angle to the stock’s e-commerce story.
The DoorDash rollout lands as Costco Wholesale’s share price has eased, with a 30 day share price return of down 5.1% and a 90 day move of down 6.4%, even as upcoming earnings and product assortment changes keep the story in focus. For long term holders, the 3 year total shareholder return of 69.3% and 5 year total shareholder return of 112.2% contrast with a 1 year total shareholder return that is down 4.1%, hinting that momentum has cooled recently after a strong multi year run.
Spot opportunities beyond Costco Wholesale by scanning our hand picked list of resilient retailers in the 30 resilient stocks with low risk scores.Costco Wholesale now trades below recent highs while its business keeps adding pieces like the DoorDash rollout. Is this pullback about fundamentals starting to crack, or has sentiment simply swung too far and reset the valuation story?
Most Popular Narrative: 17% Undervalued
Costco Wholesale last closed at $899.41, while the most followed narrative pegs fair value around $1,082.94. This frames the recent pullback as a valuation reset rather than a break in the business story.
Costco plans to continue expanding its warehouse locations, with 28 new openings planned for fiscal year 2025. This expansion is likely to increase membership and sales volume, driving revenue growth.
See why 308 investors see Costco Wholesale as 17% undervalued.
That widely followed framework uses a 7.11% discount rate and assumes Costco Wholesale can lift profit margins from about 3.0% to 3.2%, with earnings reaching $11.6b by around 2029 and the stock trading on a P/E of roughly 50.8x at that point.
Analysts in that narrative are using those inputs, plus revenue assumptions of roughly 7.4% annual growth, to reach a consensus fair value of $1,082.94. They also acknowledge a wide price target range between $740 and $1,315 that underlines how sensitive the outcome is to small shifts in growth or margin views.
Result: Fair Value of $1,082.94 (UNDERVALUED)
Still, the Costco Wholesale story could look very different if higher labor and supply chain costs squeeze margins further or if foreign exchange swings continue to reduce international profitability.
Find out about the key risks to this Costco Wholesale narrative.
Another View: Costco Wholesale Looks Expensive On Earnings
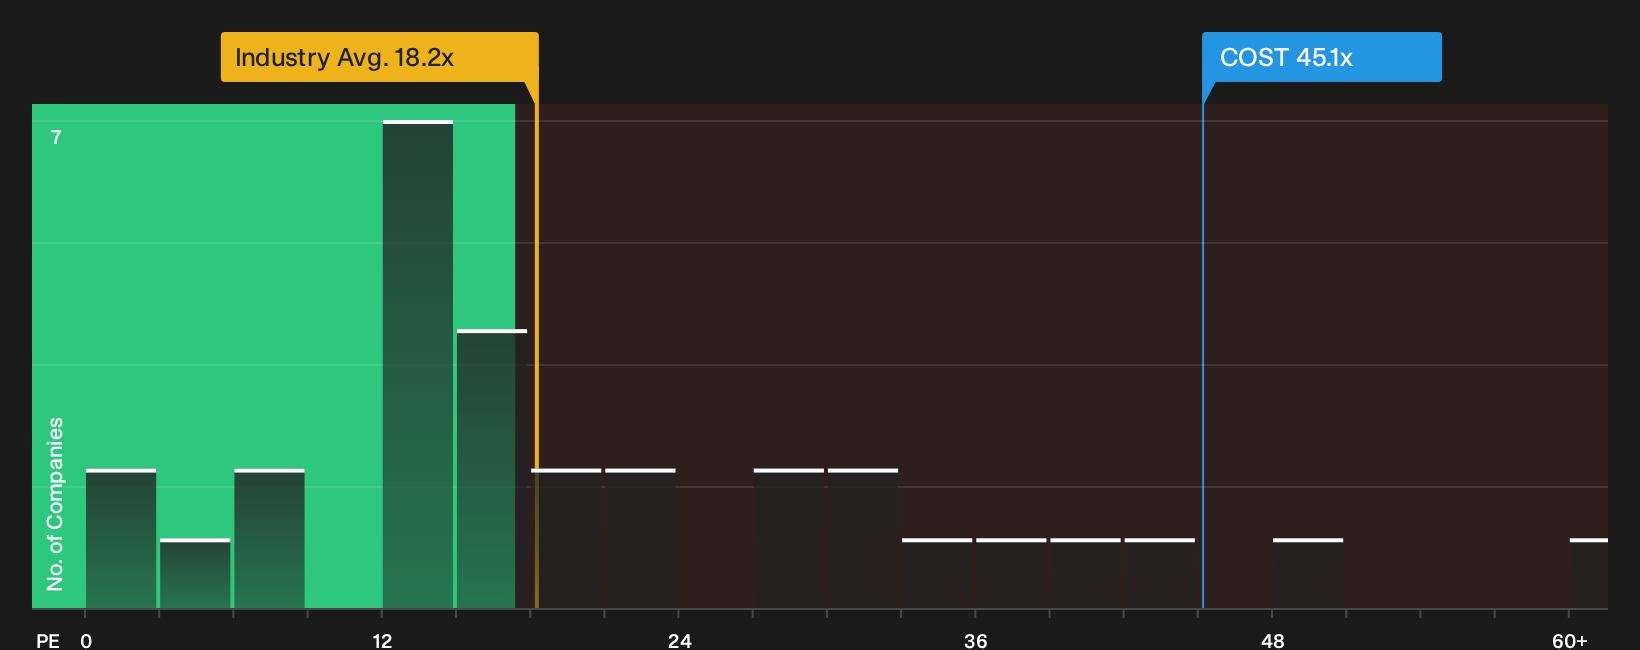
The analyst narrative frames Costco Wholesale as about 17% undervalued, yet the current P/E of roughly 45.1x tells a tougher story. That multiple is more than double the US Consumer Retailing industry at 18.2x and also well above a fair ratio estimate of 35.2x.
In practical terms, you are paying a premium today compared with peers and with where the fair ratio suggests the market could gravitate over time. The key consideration is whether Costco Wholesale can deliver enough quality and consistency to justify that kind of valuation gap.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Costco Wholesale after all this, or leaning one way already? Act while the data is fresh and weigh the upside using the 2 key rewards.
More Costco Wholesale Investment Ideas Worth Your Time
If Costco Wholesale has you thinking harder about price, quality and risk, now is the moment to widen the lens before the next market move passes you by.
Use the Simply Wall Street screener to pressure test your Costco Wholesale view against fresh opportunities and avoid leaving compelling ideas on the table.
- Target sturdier compounding by scanning for companies that look mispriced on quality fundamentals using the 29 high quality undervalued stocks.
- Reinforce your income stream by reviewing businesses that offer resilient payouts through the 7 dividend fortresses.
- Guard your downside first by filtering for financially robust candidates with the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com