


How At Home HPV Screening Will Impact Waters (WAT) Stock
- Everlywell announced in September 2026 that it is partnering with Waters Corporation to support at-home HPV cervical cancer screening in the U.S. using the FDA-cleared Onclarity HPV Self-Collection Kit tested with the BD Onclarity HPV Assay and integrated telehealth follow up.
- Waters also launched the BD FACSDiscover A7 Cell Analyzer globally, extending its flow cytometry platform into higher complexity and high-parameter cell analysis for pharma, CRO, and academic labs, which strengthens its role in research and diagnostic workflows.
- Next, the focus will be on how Waters' at-home HPV collaboration could reshape the broader investment narrative around its diagnostics exposure.
Scan beyond Waters to find other diagnostics and lab-tech stocks quietly building similar momentum with 16 high quality undiscovered gems in this space.
Waters Investment Narrative Recap
To own Waters, you need to believe the combined analytical and diagnostics portfolio can turn strong pharma R&D demand and tighter regulation into steadier recurring revenue, even with current net margins at 3.6% versus 21.6% last year. The at home HPV partnership helps reinforce the idea that Waters can plug its tools into real clinical workflows, but it does not suddenly change the earnings profile.
The key near term swing factor remains execution on the BD Biosciences and Diagnostic Solutions integration, including how reliably Waters can capture the modeled cost and revenue synergies while end markets like academic and government labs stay soft. The largest risk is that integration drag, weaker funding or tariff shifts keep margins strained just as investors are watching for proof that recent shareholder dilution and a high P/S multiple are justified.
Against that backdrop, the Everlywell collaboration looks like the most relevant development. It puts Waters' HPV testing capabilities inside an at home, telehealth connected screening pathway that directly addresses NCQA MY2026 updates and future preventive care guidance. That setup speaks to how Waters' diagnostic technology can be used in reimbursed, guideline driven care rather than remaining confined to research benches.
For catalysts, this matters because it helps frame the proposed BD acquisition as more than just scale. If Waters shows that its HPV and broader diagnostics assays are being adopted in practical programs that help close cervical cancer screening gaps, it gives investors one more operating proof point to weigh against integration risk, margin pressure and the expectation that earnings will grow significantly over the next three years.
What The Waters Earnings Framework Implies
Waters' narrative projects US$7.9b revenue and US$1.4b earnings by 2029. That profile lines up with analysts modeling 19.3% yearly revenue growth and an earnings increase of about US$1.2b from US$166.6m today.
Uncover how Waters' fair value indicates a 3% potential upside to its current price that may not last much longer.
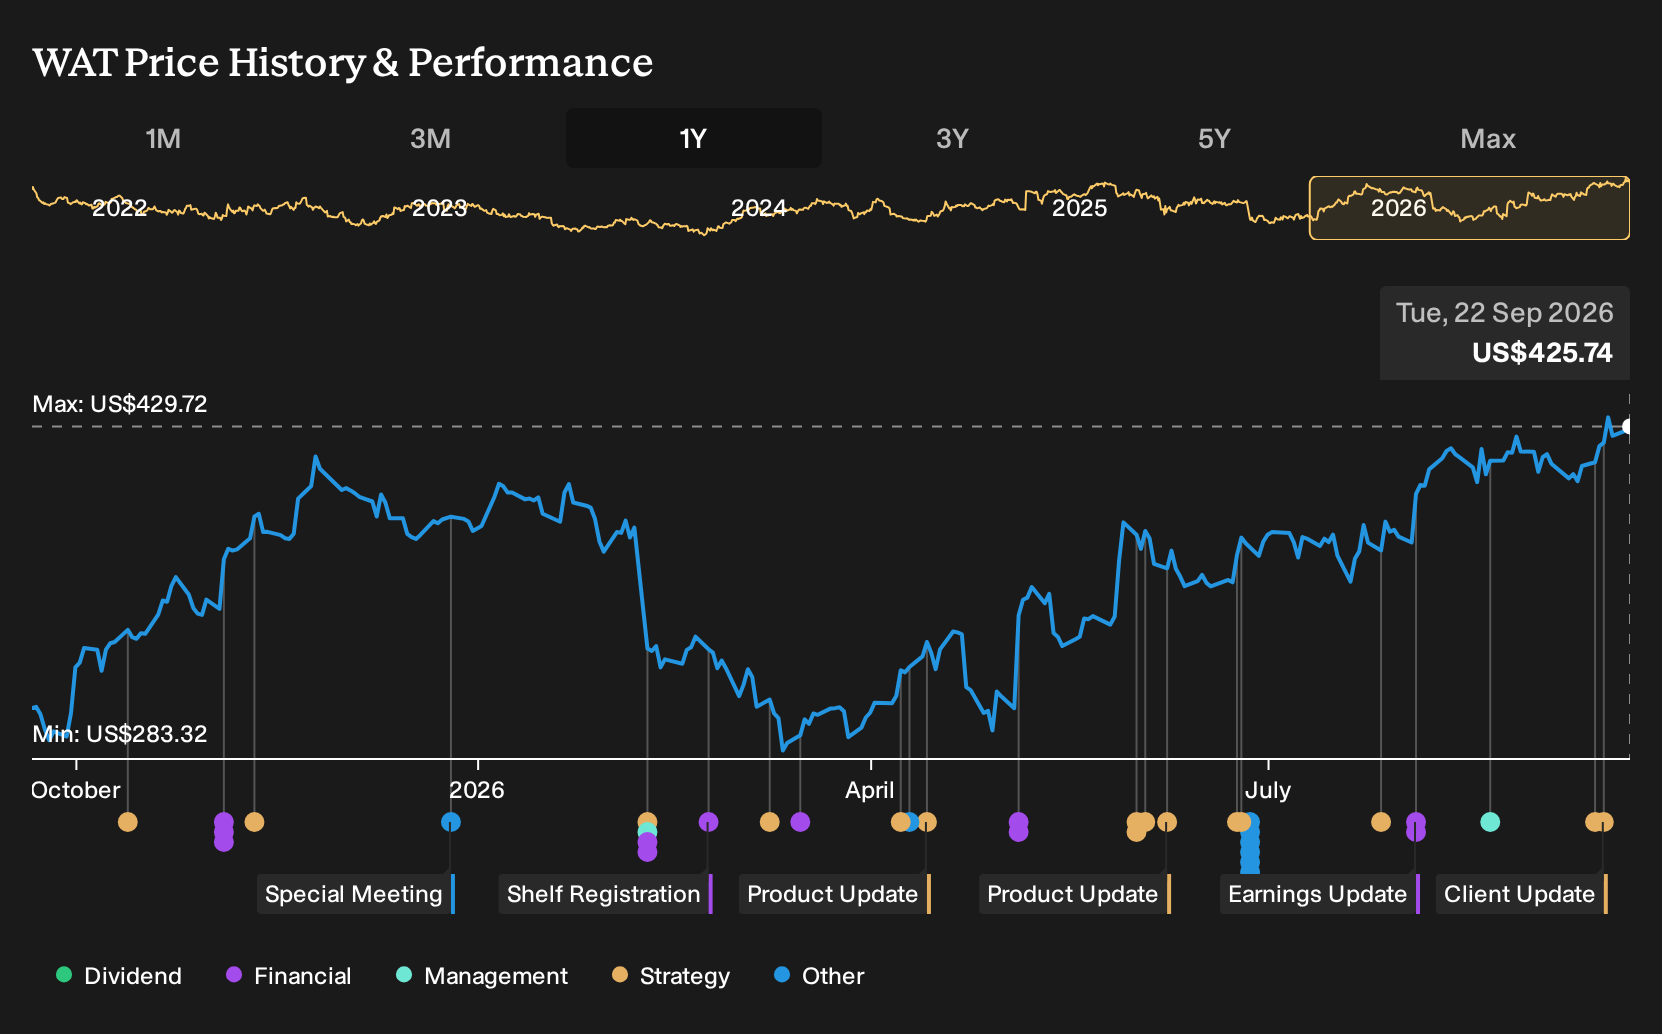
Exploring Other Perspectives
Some of the most optimistic analysts on Waters focus less on integration risk and more on how fast new offerings could scale. Before this Everlywell news, the bullish camp was already penciling in about US$8.7b of revenue and US$1.6b of earnings by 2029. You can treat that as one possible story and compare it against more cautious views.
Explore 3 other Waters fair value estimates, including one that suggests up to 15% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Waters research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Waters. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Waters' overall financial health at a glance.
Looking For More Investment Ideas Beyond Waters?
Once you have a view on Waters, it helps to widen the net and compare it with other potential opportunities that fit different goals and risk levels.
- If you want potential upside with less balance sheet strain, consider screening for companies with stronger finances using our list of solid balance sheet and fundamentals (23 results).
- For investors who care most about finding quality at a reasonable entry point, use the valuation focused screener built around 29 high quality undervalued stocks.
- Income focused readers can zero in on more resilient cash return profiles by filtering for 7 dividend fortresses that might suit a yield oriented approach.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com