


Roche (SWX:ROP) Stock Looks Undervalued After Strong Drug News
Roche Holding has delivered a strong run over the past few years, and recent drug news keeps expectations in focus. The key issue now is whether the current share price lines up with what its earnings can justify. With that backdrop, you need to ask if the recent move in the stock is simply tracking its profit power or leaning more on optimism about what comes next.
- Roche Holding has returned 62.1% over the past 3 years, which puts real weight on the question of whether its earnings profile can support today’s valuation.
- Positive late stage oncology and neurology readouts, along with new research collaborations, may support expectations for future profit streams and influence how much investors are willing to pay for each unit of Roche’s earnings.
- There is a second opinion on Roche Holding worth weighing. See what analysts think Roche Holding's shares could be worth.
The issue now is whether the earnings that Roche Holding generates today, and what investors reasonably expect from them, are enough to justify the current share price.
If you want to test the same earnings question you are asking of Roche Holding across a broader set of ideas, scan through 132 healthcare AI stocks.
Does Roche Holding Look Undervalued on Earnings?
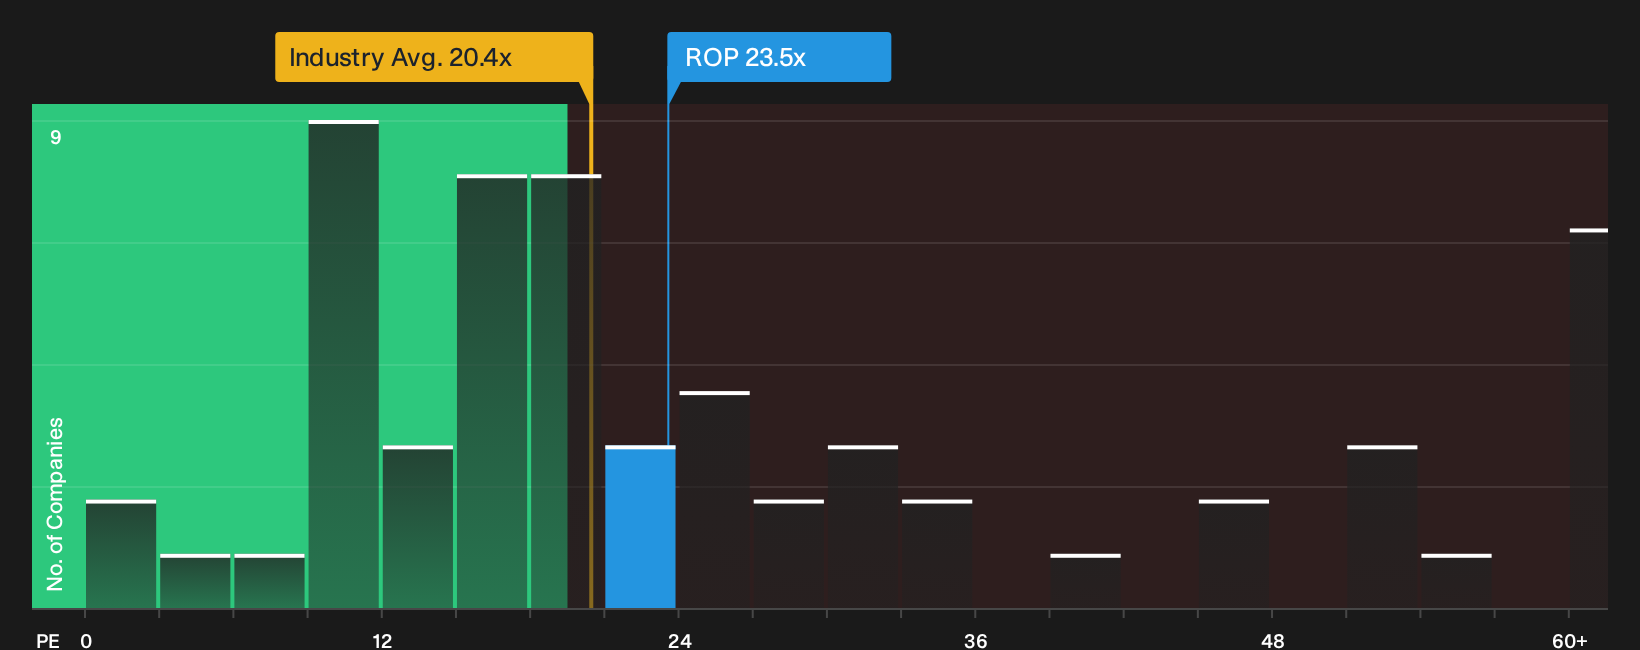
The P/E ratio is a useful shortcut here because Roche Holding is widely followed and earnings remain a central yardstick for how investors frame the business. The stock trades on a P/E of 23.5x, which is slightly above the pharmaceuticals industry average of 22.1x and well below the broader peer group on about 42.0x. That gap to peers indicates investors are paying a more moderate price for each franc of Roche Holding earnings than for many other large pharmaceutical stocks.
Recent positive readouts in oncology and neurology, along with the MediLink collaboration progress, have helped keep attention on Roche Holding. However, the current P/E still sits below the level implied by a more tailored fair multiple that adjusts for the group’s growth profile, margins, scale and risk. That indicates the market price reflects a lower earnings multiple than this framework would suggest, so you would need to decide whether the pipeline, existing franchises and regulatory milestones support narrowing some of that gap. Explore the numbers behind Roche Holding's P/E valuation.
The Roche Holding Narrative: What Would Justify Today's Price?
Narratives for Roche Holding on Simply Wall St’s Community page pick up where the valuation puzzle leaves off by spelling out which future paths for growth, profitability and earnings would need to play out for the current share price to look meaningfully cheap or expensive. Each one treats fair value as a thesis about Roche Holding's business that you can come back to over time and see how well it matches what actually happens.
Community views on Roche Holding cluster around the idea that the stock is roughly fairly valued, with one side seeing more pipeline optionality than the other.
Bull case: roughly fairly valued
"Late stage pipeline breadth, including 10 new molecular entities moving into Phase III and the potential launch of up to 19 medicines by the end of the decade, gives Roche multiple shots on goal..."
Discover why this Narrative puts Roche Holding at roughly fairly valued.
Bear case: roughly fairly valued
"Roche represents a high-quality, lower-risk pharma investment relative to biotech, supported by strong cash flows, market leadership in oncology, and a deep pipeline, however, upside is constrained by loss of exclusivity and pipeline uncertainty..."
Explore why this Narrative puts Roche Holding at roughly fairly valued.
The Roche Holding share price is only one part of the decision
Roche Holding’s valuation tells you what the market pays for its earnings, but the people deciding where that cash goes, how they think, and how they are rewarded can matter just as much. See who runs Roche Holding and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com