


How Columbia Threadneedle Partnership Will Impact Hamilton Lane Stock (HLNE)
- Columbia Threadneedle Investments announced in September 2026 a collaboration with Hamilton Lane to pair public market and multi-asset capabilities with Hamilton Lane's private markets platform, alongside a preliminary SEC filing for the Columbia Hamilton Lane Growth Innovation Fund, a public private growth equity interval fund aimed at the wealth channel.
- The tie-up gives Hamilton Lane a route to bring its private markets expertise into advisor-led wealth portfolios, potentially deepening fee-based relationships where clients want a single product that blends public securities, private assets and institutional-style portfolio management.
- We will now look at how this Columbia Threadneedle wealth-channel partnership could influence Hamilton Lane's existing investment narrative and growth focus.
Hamilton Lane Investment Narrative Recap
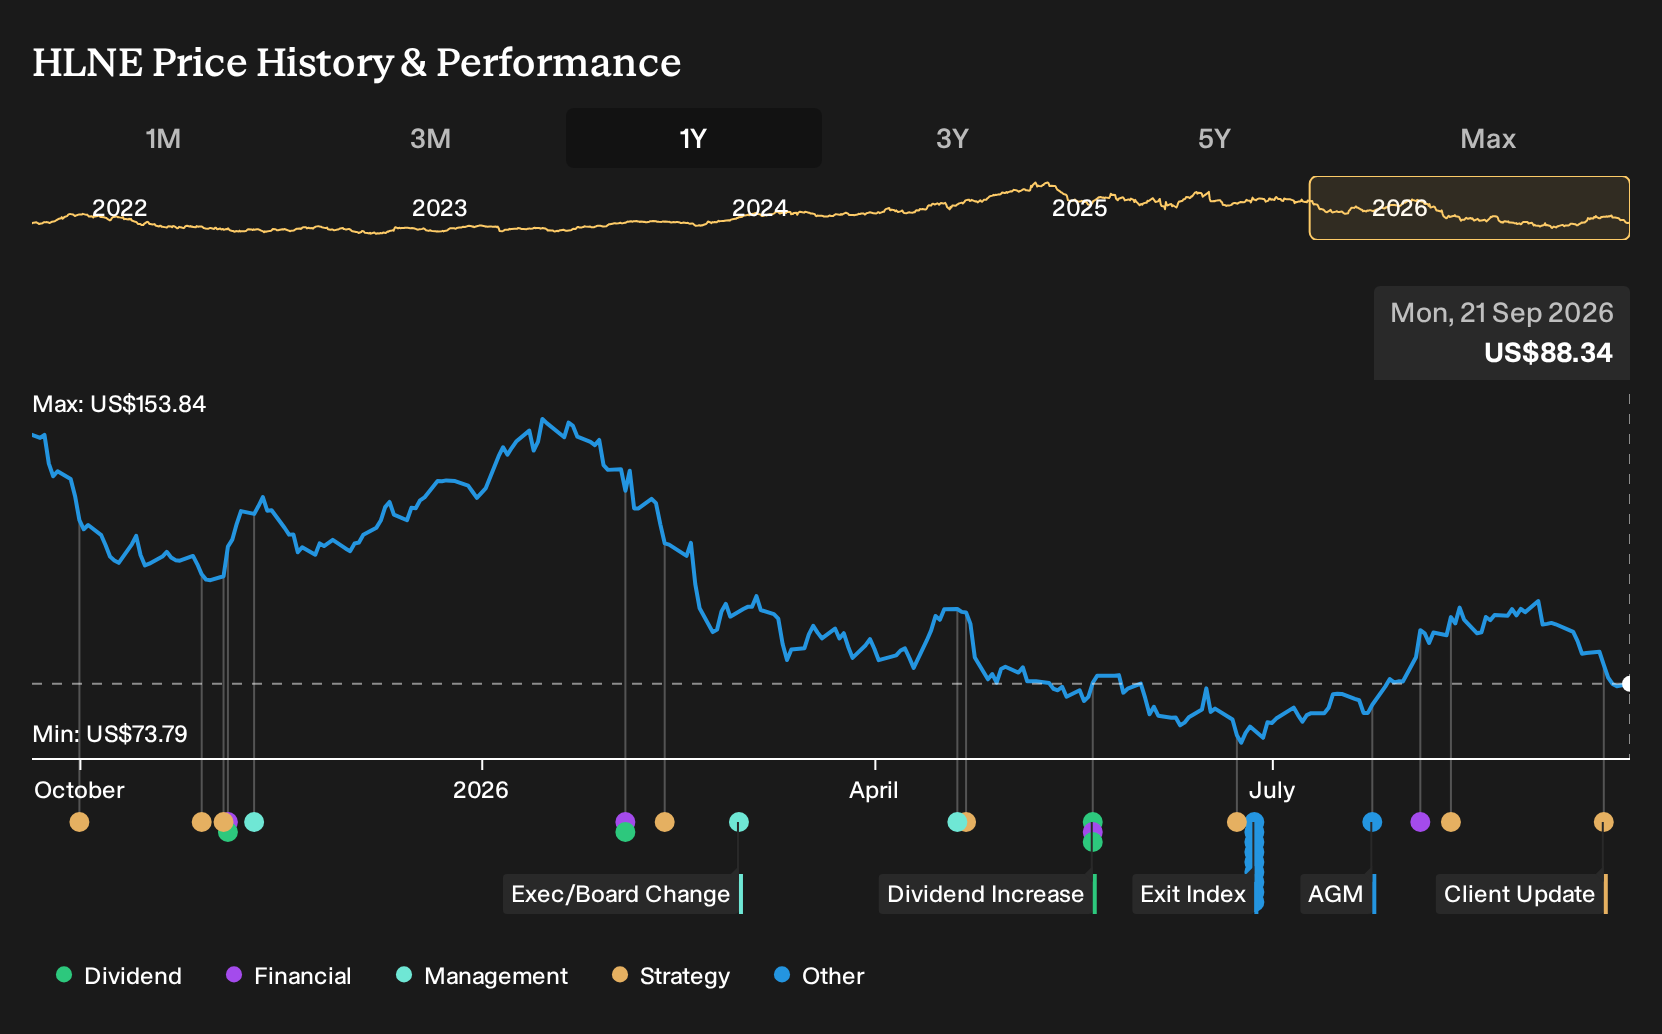
Hamilton Lane asks you to believe that private markets can keep attracting capital across cycles and that this manager can keep winning mandates through evergreen funds, separate accounts and wealth partnerships. The short term swing factor is whether fundraising and fee earning assets stay healthy after a year where the share price fell about 39% while fundamentals like revenue of roughly $858 million and net income of $275.9 million hold investor attention.
The biggest business risk right now is that fee pressure, regulation and heavier distribution deals raise costs faster than fee revenue grows, which could squeeze margins that recently sat around 32.1%. The Columbia Threadneedle collaboration looks additive to distribution but, on the information available today, does not obviously change these near term risk and reward drivers.
The Columbia Hamilton Lane Growth Innovation Fund filing is the announcement that most clearly ties to this story. It takes the existing push in evergreen products and wealth platforms and tries to package private and public growth equity in a single interval vehicle that advisors can realistically use in client portfolios.
Execution around that fund will feed directly into the catalysts analysts already focus on, such as expanding fee earning AUM, evergreen inflows and technology supported distribution. Weak take up would reinforce concerns about competition in retail private markets access and could highlight how difficult it is to scale complex wealth partnerships without adding meaningful operational complexity or eroding pricing power.
Hamilton Lane's narrative projects US$1.1b revenue and US$496.8 million earnings by 2029. This assumes 13.9% yearly revenue growth and an earnings increase of about US$247.6 million from US$249.2 million today.
Discover why Hamilton Lane's fair value indicates a 47% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view zooms in on Hamilton Lane’s Evergreen platform as the real swing factor. The most optimistic analysts had already penciled in revenue of about US$1.2b and earnings of US$521.2 million by 2029, before this Columbia Threadneedle news. You can treat this partnership as a fresh test of that upbeat story and compare it with your own expectations.
Explore 9 other Hamilton Lane fair value estimates, including one that suggests as much as 201% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hamilton Lane research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hamilton Lane. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hamilton Lane's overall financial health at a glance.
Looking for more Hamilton Lane style ideas?
If the Hamilton Lane story has you thinking about portfolio quality, it can help to scan a wider set of businesses that share similar strengths or offer very different risk and return profiles.
- For investors who want potential growth without ignoring balance sheet strength, consider starting with a 7 elite penny stocks with strong financials that already pass strict financial filters.
- If valuation discipline is your anchor, scan a 30 high quality undervalued stocks that combine solid fundamentals with prices that sit below many traditional metrics.
- For a focus on resilience, broaden your watchlist with a 30 resilient stocks with low risk scores that screen well on financial health and business quality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com