


MP Materials (MP) Shares Moved, What Is Drawing Attention Now?
Why MP Materials Is Back In Focus
MP Materials (MP) returns to the spotlight as it prepares to speak at Morgan Stanley's 14th Annual Laguna Conference, with investors weighing its expanding role in the U.S. rare-earths supply chain.
Recent trading tells a mixed story. MP Materials’ share price has slipped over the past month with a 30 day share price return of 16.74% down and is also weaker year to date. However, the 3 year total shareholder return of about 152% shows long term holders have still seen strong gains.
That pullback, alongside a 1 year total shareholder return decline of about 32%, comes as the business ramps magnet production, delivers units to General Motors for testing, and leans on government backed contracts with the Department of Defense and Apple. Together, these developments appear to be reshaping how investors think about both its growth potential and risk profile.
Compare MP Materials’ rare-earth story with other government backed critical-minerals plays by scanning our hand picked 36 best rare earth metal stocks that are also tied into the supply chain rebuild.
MP Materials now trades well below both analyst targets and an implied fair value, yet the stock has slid in recent months as execution and rare earth pricing risks stay front of mind. Is that discount a sign of caution, or is it an opportunity?
Most Popular Narrative: 34% Undervalued
On the numbers currently in focus, the most followed narrative pegs MP Materials' fair value at $75.28, compared with a last close of $50. This frames the stock as materially discounted while analysts still anchor their work to rare earth demand, government support, and downstream expansion.
The company is expanding its vertically integrated processing and magnet manufacturing capacity with the "10X" plant and a modular recycling facility. Together with significant CapEx support from Apple and the DoD, this is expected to capture more value-added margins and potentially improve net profit and operating leverage as they ramp downstream operations.
See why 190 investors see MP Materials as 34% undervalued.
Result: Fair Value of $75.28 (UNDERVALUED)
Still, the MP Materials story can change quickly if the rapid build out of new facilities runs into delays, or if key contracts are renegotiated on less favourable terms.
Find out about the key risks to this MP Materials narrative.
Another View On MP Materials’ Valuation
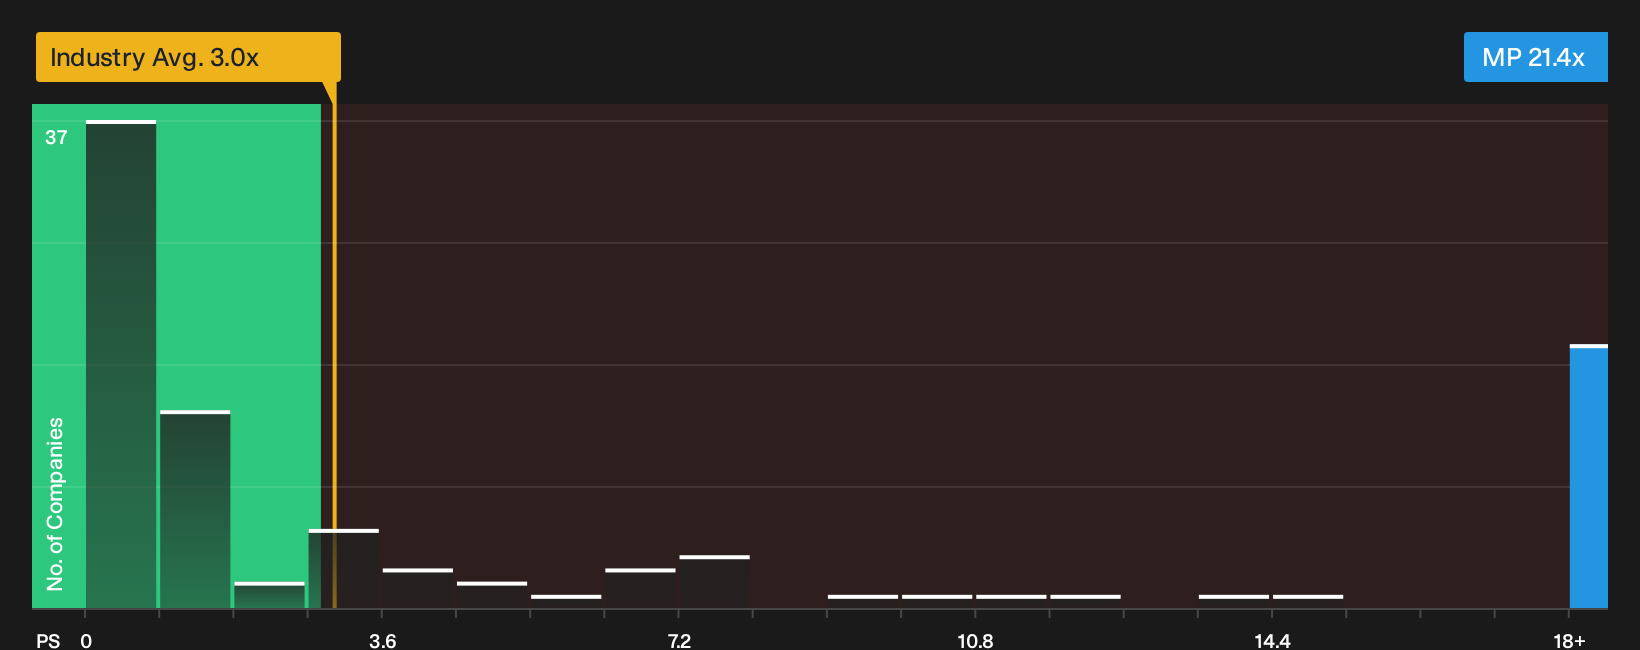
The narrative so far leans on fair value estimates and analyst targets that frame MP Materials as heavily discounted. A different lens tells a sharper story. On current numbers, MP trades on a P/S ratio of 21.4x, while the fair ratio is 7x and the US Metals and Mining industry sits near 3x. For investors, that gap means paying a much higher price for each dollar of present revenue, even if future growth expectations look strong on paper. How comfortable are you with that premium?
Before leaning on any single ratio, it is worth stepping back and asking whether the earnings and cash flow outlook you believe in really justifies a valuation this far above both peers and the fair ratio, or if sentiment has simply moved faster than the fundamentals.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Questioning whether the cautious tone around MP Materials fully captures the upside case? Act quickly, stress test the thesis, and weigh the 3 key rewards.
Looking for more investment ideas beyond MP Materials?
Do not stop at MP Materials. Broaden your watchlist now and you might spot opportunities others only notice after the move has already played out.
- Target potential mispricing by scanning a curated set of companies using the 30 high quality undervalued stocks.
- Protect your downside first by reviewing a 30 resilient stocks with low risk scores that focuses on resilience when markets turn choppy.
- Hunt for future leaders early by checking a 17 high quality undiscovered gems before they hit every analyst’s radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com