


Did Analyst Day Updates Just Shift Infratil (NZSE:IFT) Stock's Investment Narrative?
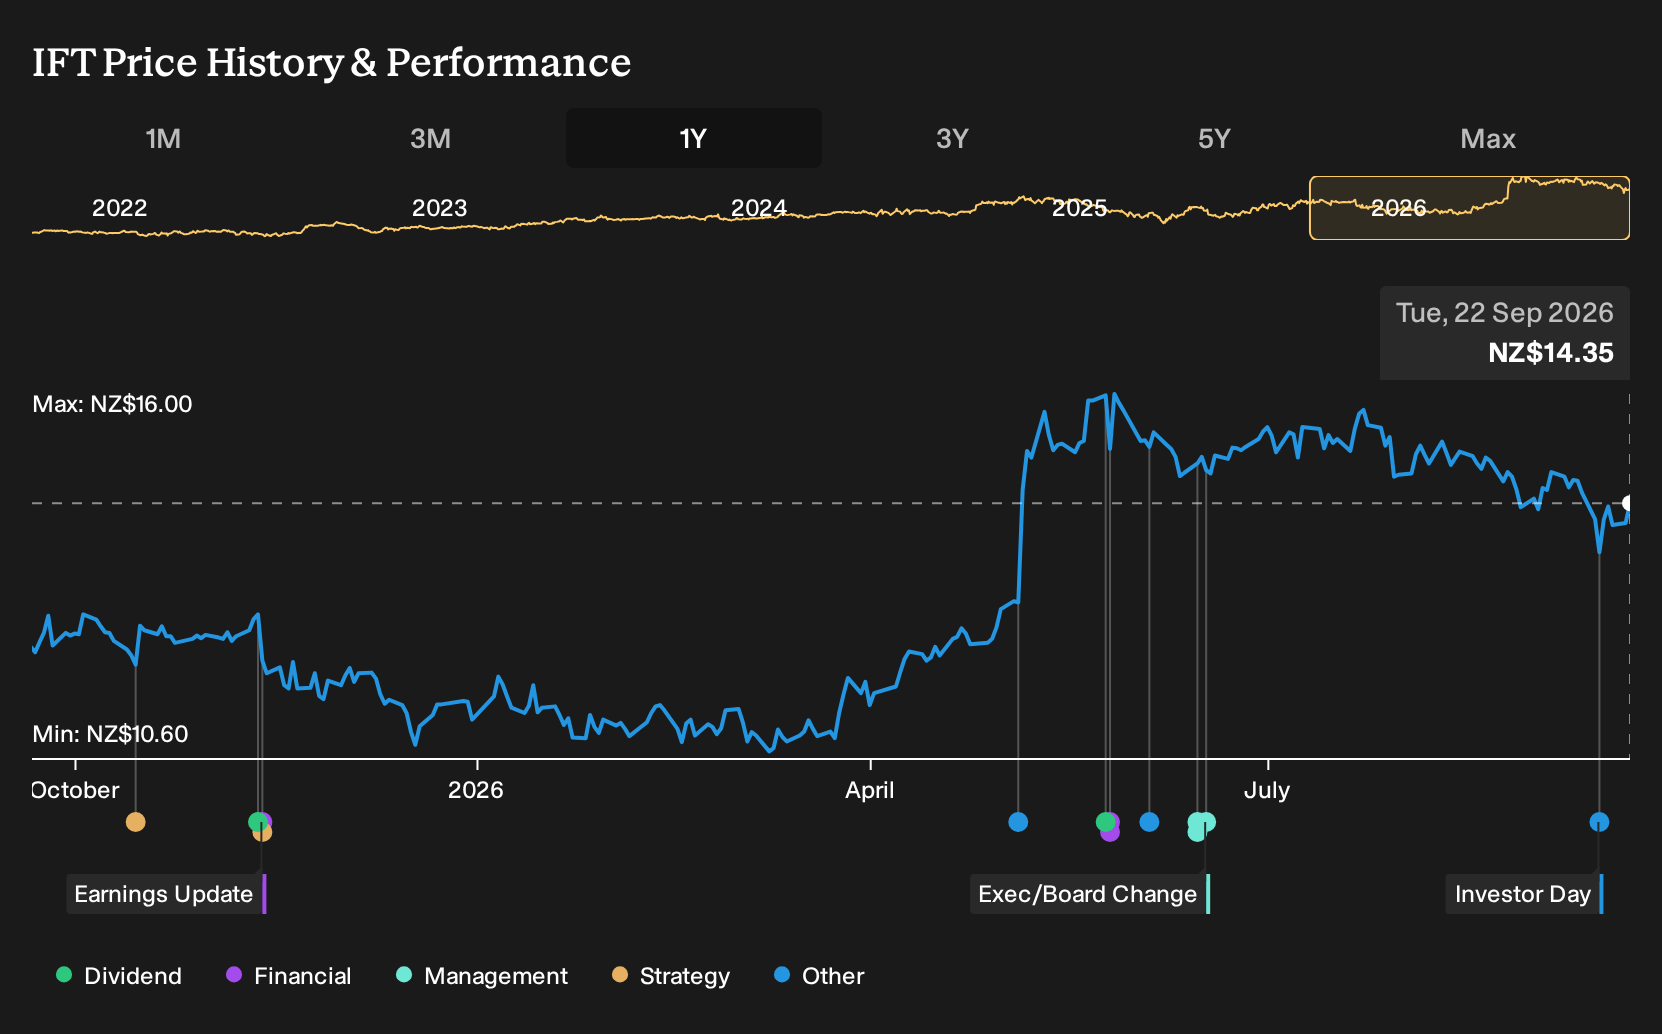
- Infratil recently held an Analyst and Investor Day, where management walked through current operations, capital allocation priorities, and portfolio positioning across its infrastructure holdings.
- The event gave investors a closer look at how Infratil is considering growth projects, cost discipline, and regulatory exposure across its key platforms.
- Now the focus shifts to how Infratil's investment narrative evolves in light of the additional detail shared at its Analyst and Investor Day.
Scan how Infratil frames its capital allocation playbook, then compare that approach with a curated 230 resilient stocks with low risk scores that prioritise resilient balance sheets and disciplined investment plans.
Infratil Investment Narrative Recap
For Infratil, you need to believe in a long runway across digital infrastructure, renewables, and social assets, and in management’s ability to recycle capital between platforms as conditions change. The Analyst and Investor Day sharpened that picture but did not radically alter it. The near term story still leans on progressing data center capacity, tidying up energy exposure, and bedding in newer healthcare holdings.
The most immediate catalyst remains execution at CDC and across power and customer contracts. The biggest current risk sits around capital intensity and funding, especially with interest costs not well covered by earnings and all liabilities coming from higher risk borrowing. The Investor Day mainly clarified these trade offs rather than changing them.
Infratil highlighted CDC as a core engine, with earlier commentary already flagging customer negotiations for hundreds of megawatts of capacity as a key driver. The recent Investor Day effectively becomes the freshest update on how management is lining up power, capex, and contract timing around that pipeline. For a shareholder, the practical question is whether those negotiations convert into firm deals at a sensible return.
That same disclosure also shines a light on risk. Delays in CDC customer contracts, the Manawa and Contact merger approval, or Longroad’s project cadence in the U.S. could push out revenue recognition while debt servicing continues. When thinking about catalysts, it is less about a single headline and more about whether Infratil can line up approvals, contracts, and financing on roughly the timetable discussed at the Investor Day.
Infratil Analyst Assumptions In Focus
Analysts sketch a fairly specific set of expectations for Infratil that you can treat as a reference point rather than a blueprint. The consensus view points to revenue rising by 1.9% a year over the next 3 years and profit margins moving from 7.7% today to 13.9% in the same window. That path then feeds into a 2029 earnings estimate of NZ$513.6m, with a wide spread between the highest and lowest forecasts that signals real disagreement about how CDC, Longroad and One NZ will perform.
On earnings, the current figure of NZ$269.6m would need to almost double to hit the NZ$513.6m consensus mark by June 2029, which is roughly a 1.9x step up from today. Analysts also fold in modest dilution, with shares on issue expected to grow by about 2.01% per year for the next 3 years as Infratil funds its project pipeline. That equity growth, combined with the earnings bridge, is what underpins the implied P/E shift from 56.3x today to 44.9x in 2029, still above the 32.3x level ascribed to the wider AU Diversified Financial industry.
Bringing those pieces together, the consensus framework effectively asks you to assume Infratil can reach about NZ$3.7b of revenue and NZ$513.6m of earnings by 2029 while justifying a 44.9x P/E multiple on those earnings, based on a discount rate of roughly 7.5% to 7.53%. That is quite a specific bundle of beliefs about growth, margins, capital structure and valuation multiples. The useful exercise for any investor is not to accept it at face value but to test where your own expectations around CDC contracts, energy approvals and U.S. renewables differ from that picture.
Infratil's narrative projects NZ$3.7b revenue and NZ$513.6m earnings by 2029. This rests on revenue growing 1.9% per year and earnings rising by about NZ$244m from NZ$269.6m today.
Discover why Infratil's fair value points to a 22% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Fair value estimates for Infratil from the Simply Wall St Community span from NZ$2.60 to NZ$17.81 across 3 separate views, so private investors are clearly not aligned. These opinions were formed before the September 2026 Analyst and Investor Day, so updated information on CDC contracts and regulatory approvals could shift those projections meaningfully. Readers should weigh these contrasting expectations against their own assessment of Infratil’s execution risks and potential catalysts, and then explore several alternative viewpoints before acting.
Explore 2 other Infratil fair value estimates, including one that suggests as much as 24% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Infratil research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Infratil. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Infratil's overall financial health at a glance.
Looking For More Investment Ideas Beyond Infratil?
Once you have a view on Infratil, it can help to widen the lens and compare its profile with other listed businesses that fit different risk, income, and quality filters using the Simply Wall St Screener.
- For investors who want income to play a bigger role in returns, consider stocks with robust payout profiles using the 160 dividend fortresses.
- If capital preservation and balance sheet strength matter most to you, focus on companies with conservative leverage and healthy liquidity through the list of solid balance sheet and fundamentals (197 results).
- Readers looking for companies that the market may be overlooking can scan a 616 high quality undiscovered gems that screens for quality fundamentals paired with limited coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com