


Why Kestra Medical Technologies (KMTS) Is Back In Focus
Why Kestra Medical Technologies Is Back In Focus
Kestra Medical Technologies (KMTS) moved into the spotlight after first quarter results showed sales of US$30.97 million, a net loss of US$44.09 million, and an updated fiscal 2027 revenue outlook of US$141 million.
The first quarter update and higher 2027 revenue outlook have arrived after a mixed stretch for Kestra Medical Technologies, with a 19.72% 90 day share price return, an 8.23% decline over 30 days, and a 1 year total shareholder return that is down 3.05%.
Scan how Kestra Medical Technologies compares with other high-growth healthcare names by checking the hand-picked 37 healthcare AI stocks that are already catching renewed interest after earnings updates.
Kestra Medical Technologies recently followed a sharp 90-day rebound with a wider quarterly loss and a higher 2027 revenue target. Do you lean into the current price, or wait for a cheaper entry point to the same story?
Most Popular Narrative: 17% Undervalued
The most followed narrative pegs Kestra Medical Technologies at a fair value of $30 per share, compared with a last close of $24.77. That gap rests on a view that the business can turn rapid top line expansion into a much more efficient model over time.
This narrative assumes Kestra Medical Technologies can translate fast growing revenue of US$95 million in FY26 and a guided US$137 million in FY27 into much higher earnings over time, yet the company still reported a net loss of US$38.8 million in Q4 FY26 and US$131.6 million for FY26, with adjusted EBITDA losses widening as operating costs rose. If revenue growth slows or operating expenses continue to rise faster than gross profit, losses could remain large and delay any improvement in net margins.
See why 1 investors see Kestra Medical Technologies as 17% undervalued.
Result: Fair Value of $30 (UNDERVALUED)
Still, the narrative around Kestra Medical Technologies depends on turning large annual losses into better efficiency, and any slowdown in ASSURE WCD adoption could quickly test that thesis.
Find out about the key risks to this Kestra Medical Technologies narrative.
Another View On Kestra Medical Technologies’ Valuation
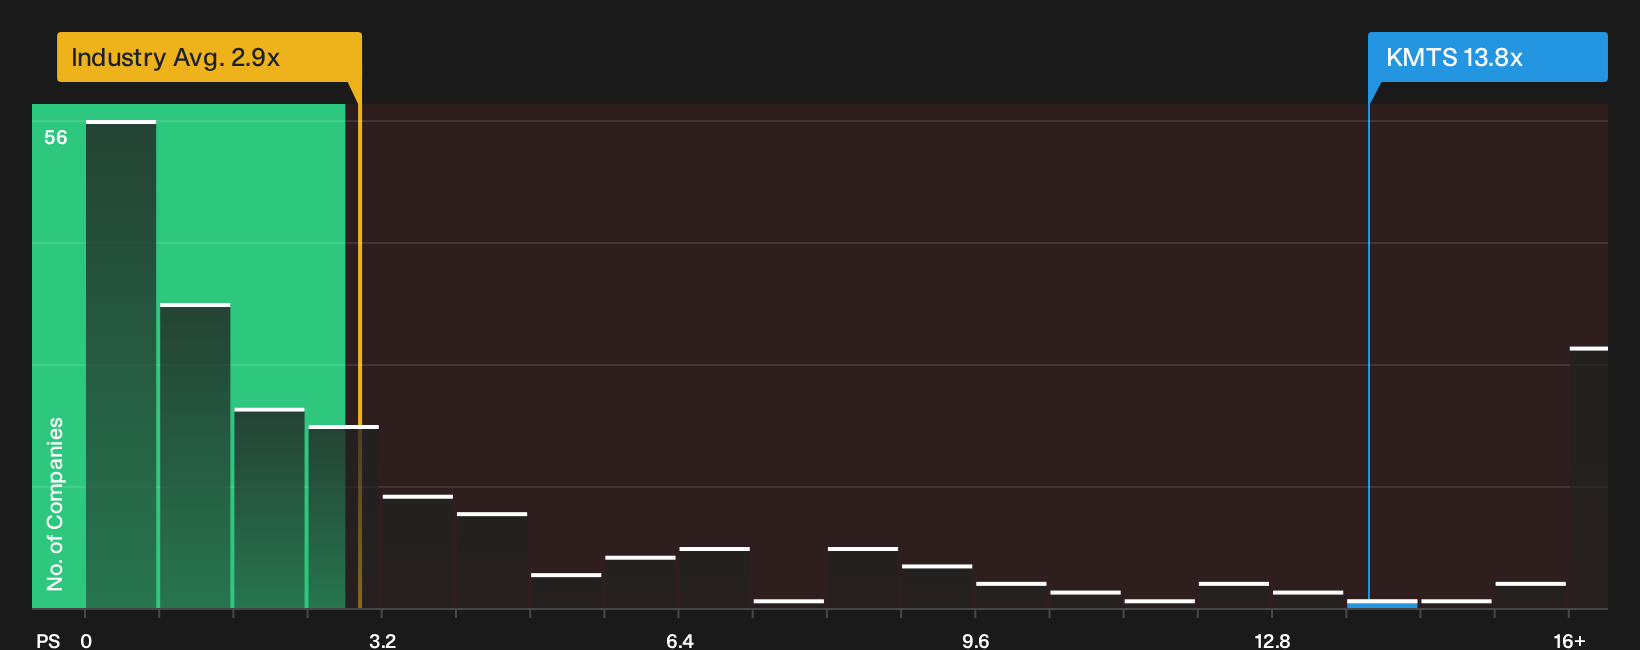
On a simple P/S lens, Kestra Medical Technologies trades at about 13.8x, while the US Medical Equipment group sits near 2.9x and direct peers around 1.2x. The fair ratio estimate is 4.4x. That is a wide premium. Is that rich multiple a cushion for growth, or is the margin for error shrinking fast?
See what the numbers say about this price in our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Kestra Medical Technologies can easily skew your view, so move quickly, review the figures yourself, and weigh both sides through the 2 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Kestra Medical Technologies?
If Kestra Medical Technologies has your attention, do not stop here. Fresh opportunities keep opening up, and the sooner you review them the more options you keep on the table.
- Target potential mispricing by scanning companies that screen as 30 high quality undervalued stocks and see where the market may be slow to react.
- Focus on resilience by reviewing a list of solid balance sheet and fundamentals (23 results) that can help you spot businesses built to handle tougher conditions.
- Hunt for early-stage potential by filtering through 17 high quality undiscovered gems before broader attention starts to crowd the opportunity.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com