


THOR Industries (THO) Earnings Weakened, Is The Stock Cheap Or Fully Valued?
Thor Industries (THO) just reported fourth quarter and full year results that showed lower quarterly sales, sharply reduced net income and weaker earnings per share compared with the prior year period.
THOR Industries’ latest earnings release appears to have kept pressure on sentiment, with the share price at US$69.94 and a year to date share price return down 33.66%, while the 1 year total shareholder return has declined 29.58%. This signals fading momentum despite the brief 1 day share price rebound of 3.20% after the news.
Scan how THOR Industries compares with other RV and auto-related plays by focusing on a curated group of 17 high quality undiscovered gems that the market may be underpricing right now.
Thor Industries now trades well below recent levels after weaker earnings, yet still carries meaningful scale and brand power in RVs. Does that reset tip the risk reward balance toward buyers, or keep caution in charge as valuation comes into focus?
Price-to-Earnings of 13.9x: Is it justified?
On a P/E of 13.9x at a last close of $69.94, THOR Industries screens cheaper than many direct peers but not outright cheap relative to the wider auto universe. The share price has fallen sharply this year, yet the multiple still sits in a zone where investors need to weigh whether recent earnings strength or longer term weakness carries more weight.
The P/E ratio compares the current share price to annual earnings per share and gives a quick sense of how much investors are paying for each dollar of profit. For a manufacturer like THOR Industries with cyclical end markets, that gauge often reflects what the market expects from the next phase of the RV cycle rather than just the last set of results.
Recent data shows a mixed picture. Earnings grew 17.8% over the past year and are forecast to grow 16.9% per year, which points to some recovery in profitability after several difficult years in which earnings declined 30.7% per year on average. Against that backdrop, a P/E of 13.9x sits below the estimated fair P/E of 17.1x, which suggests the valuation could move closer to that fair ratio if the recent improvement in earnings quality and margins proves durable.
Relative to peers, the story is more nuanced. THOR Industries is described as good value versus a peer average P/E of 19.9x, which is a sizable gap. Yet the same 13.9x multiple is slightly expensive compared with the Global Auto industry average of 13.7x and still lower than the broader US market at 18.2x. The market is effectively pricing THOR Industries as cheaper than similar RV focused companies but not meaningfully below the global auto group. This leaves the fair P/E ratio as an important reference point for investors weighing how much rerating room might be left.
Explore the SWS fair ratio for THOR Industries.
Result: Price-to-Earnings of 13.9x (UNDERVALUED)
Still, Thor Industries faces clear risks if RV demand weakens further or dealer inventories stay elevated, which could pressure earnings and keep the P/E discount lingering.
Find out about the key risks to this THOR Industries narrative.
Another View on Thor Industries: Our DCF Check
The P/E gap paints THOR Industries as inexpensive, yet the SWS DCF model points the other way. In this framework, the estimated future cash flow value sits at $33.26 per share, far below the current $69.94 price and this flags the stock as overvalued on this lens. Which signal should carry more weight for you right now?
For a closer look at how this long term cash flow view is built and why it diverges from the earnings based multiple, Look into how the SWS DCF model arrives at its fair value.
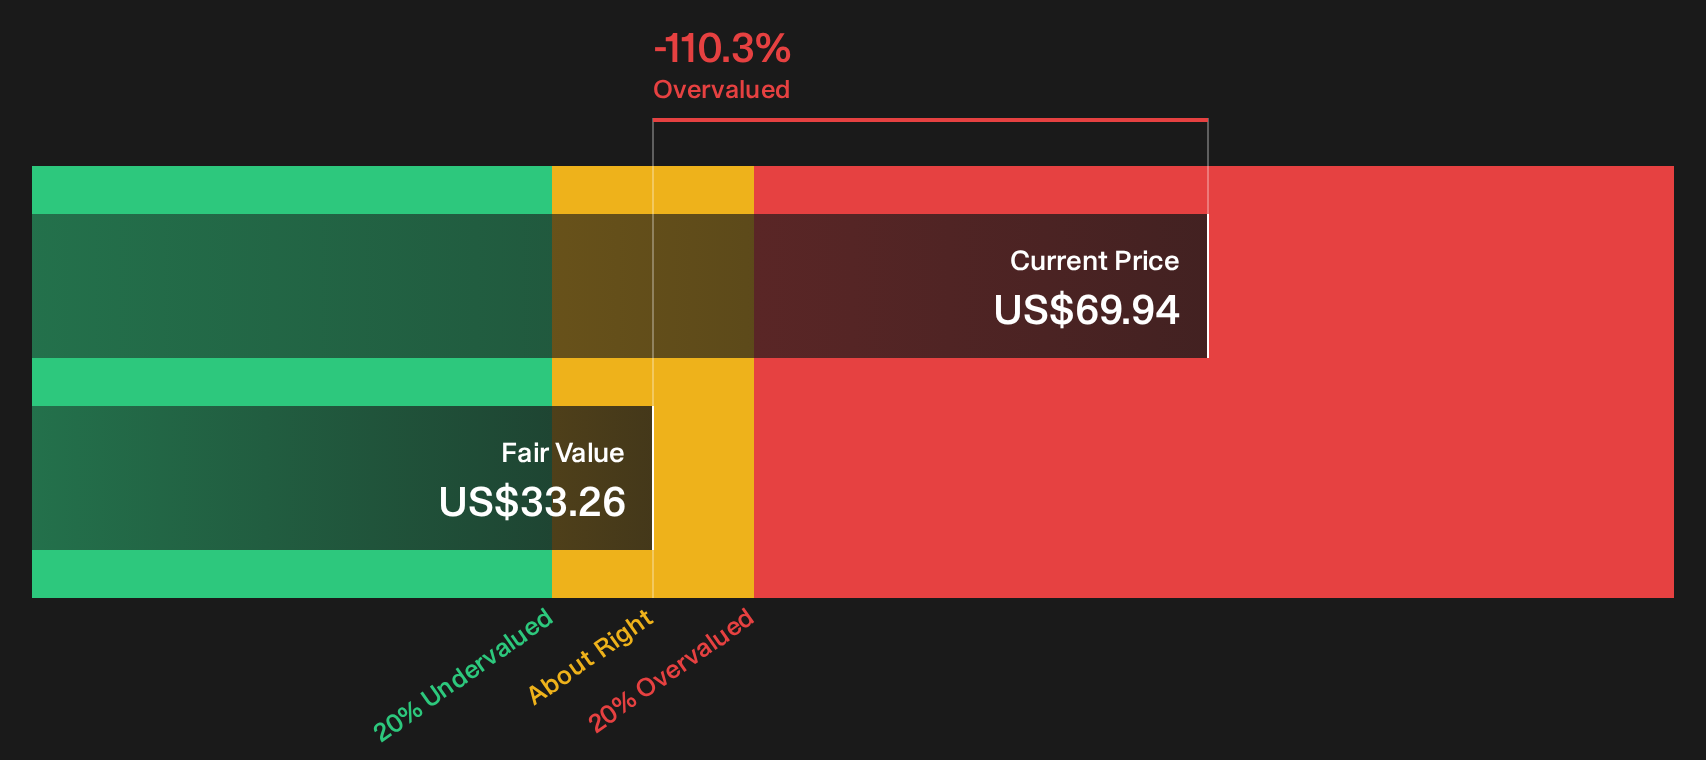
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out THOR Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Thor Industries is clearly split, so treat this as a prompt to check the numbers yourself and decide quickly where you stand. To understand why some investors still see upside potential in the business, review the 4 key rewards
Looking for more Thor Industries investment ideas?
If Thor Industries has you reassessing your portfolio, now is the moment to broaden your watchlist and uncover other opportunities before the market moves first.
- Zero in on quality at a discount and scan a curated 30 high quality undervalued stocks that may offer stronger fundamentals for every dollar you commit.
- Build a steadier income stream by reviewing a focused 7 dividend fortresses that could complement or balance a position in a cyclical business like Thor Industries.
- Dial back portfolio risk by assessing a carefully filtered 30 resilient stocks with low risk scores so you are not relying on just one cyclical RV stock to set the tone.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com