


3 UK Financial Stocks Retail Investors Are Watching As Gilt Yields Stay Elevated
UK gilt yields around 5.23% and August borrowing of £18.3b have dragged government finances back into the spotlight, which puts every broker, dealer and bond specialist under a far brighter beam. When the state pays more to borrow, pricing, trading volumes and investor attention can all shift quickly. This piece picks out three UK Gilt Market Intermediaries and Dealers stocks that are closely tied to that story and explores how the current backdrop might affect each one.
The three UK Gilt Market Intermediaries and Dealers stocks below are just a starting sample, while the full screen surfaced 10 more companies with equally detailed gilt-linked narratives that are not covered here. To go wider and identify your own highest conviction angles on this theme, head straight to the UK Gilt Market Intermediaries and Dealers screener.
Schroders (LSE:SDR)
Schroders plugs into the UK Gilt Market Intermediaries and Dealers theme through its fixed income and wealth franchises, which use gilts as building blocks for client portfolios, then rotate that capital into higher risk assets when conditions allow.
Schroders is a global investment manager and adviser, with about £2.7b of revenue from Asset Management and £852 million from Wealth Management, plus smaller segment items, and a market value near £9.3b.
"The group's disciplined transformation program, including portfolio simplification, operating model efficiencies, and cost reduction initiatives, has already reduced expenses, with a clear trajectory to further improve the cost‑to‑income ratio, directly boosting net margins and operating leverage."
What happens if a single pressure on Schroders' fee pool tightens just as that efficiency story meets changing demand for gilt-linked solutions.
That pivot point is exactly where Schroders could surprise you, so read the full narrative for Schroders to see how the gilt story may be masking the real engine here.

Ashmore Group (LSE:ASHM)
Ashmore Group brings the UK Gilt Market Intermediaries and Dealers theme into emerging markets, using bond trading and debt-focused portfolios as its core engine. It manages £139.3 million of revenue from investment management services and carries a market value close to £1.4b.
That tilt toward sovereign and corporate debt in less familiar markets is exactly what can move from quiet backwater to centre stage when gilt yields spike and government balance sheets come under scrutiny.
"Strategic initiatives such as the growing equities business and alternative assets are expected to be margin enhancing over time, potentially leading to higher net margins and earnings as demand shifts towards these higher-margin offerings."
What really matters now is how one subtle shift in client risk appetite reshapes the mix of fees Ashmore Group can earn from that platform.
That fee mix is exactly what the full narrative for Ashmore Group unpacks, showing where Ashmore Group could be quietly decoupling from headline gilt angst.

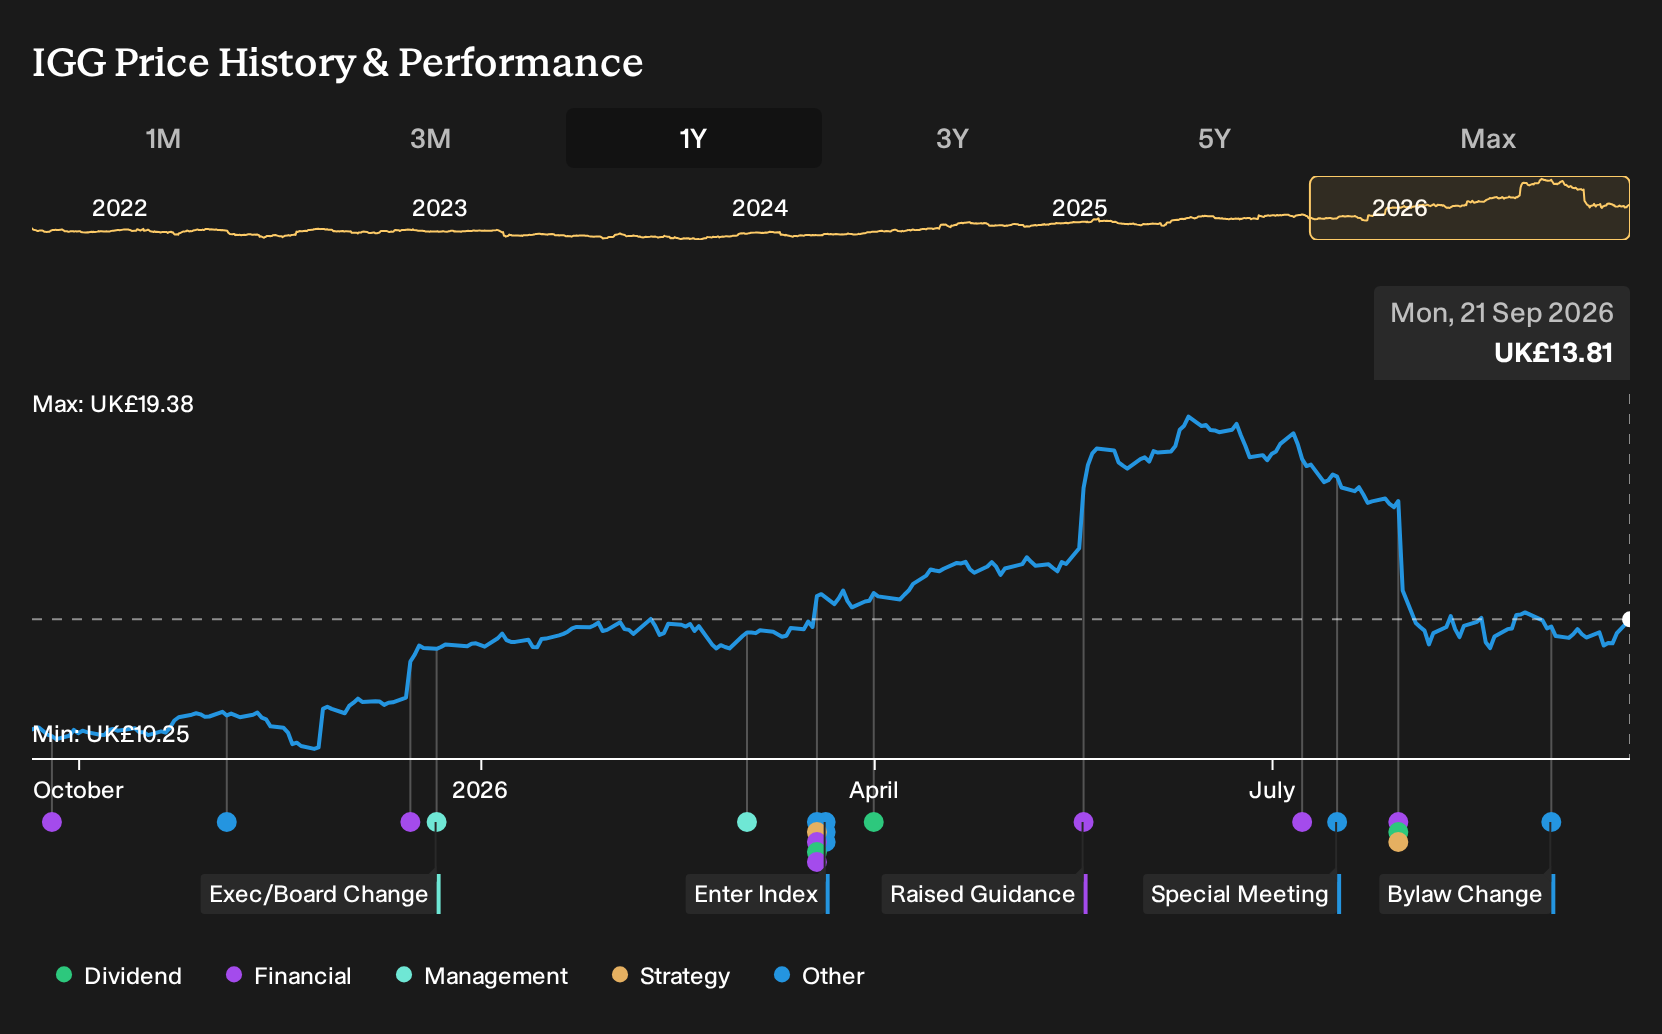
IG Group Holdings (LSE:IGG)
IG Group Holdings ties tightly into the gilt intermediaries theme because its trading platforms sit wherever clients want to express views on interest rates, macro moves and government debt. This makes its business naturally sensitive to spikes in bond volatility and volumes.
IG Group Holdings is a £4.6b fintech that runs online trading and investing platforms across derivatives, FX, equities, ETFs, fixed income products and crypto, as well as education content for retail and institutional clients worldwide.
"The ongoing global digitalization of financial services and rising retail investor participation, especially among younger demographics, are significantly expanding IG Group's addressable market."
What really moves the dial is how one quiet shift in trading activity turns into either a powerful tailwind for revenue or a drag on margins.
If that inflection in trading intensity matters to you, read the full narrative for IG Group Holdings to see how IG Group Holdings could potentially use volatility to enhance its earnings power.
Seeking Alternatives Before The Crowd
Fresh ideas move first. By the time momentum is flying and headlines catch up, early entry points are gone. Scan these under the radar lists while it matters and act now.
- Spot potential income ideas by scanning the 1 dividend fortresses before yields respond to increased interest and pricing tightens around the most resilient payers.
- Track early waves in automation by reviewing the curated 95 robotics and automation stocks while expectations are still forming and growth narratives are not fully reflected.
- Follow structural demand in electrification by reviewing the focused 17 top copper producer stocks before supply stories gain wider attention and valuations start to adjust.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com