


3 Growth Companies With High Insider Ownership And Up To 65% Revenue Growth
The United States market has shown a positive trend recently, climbing 1.8% in the last week and up 13% over the past year, with earnings projected to grow by 17% annually in the coming years. In this environment, growth companies with substantial insider ownership can be particularly appealing as they often indicate strong confidence from those closest to the business, potentially aligning well with ongoing market optimism.
Top 10 Growth Companies With High Insider Ownership In The United States
| Name | Insider Ownership | Earnings Growth |
| Uxin (UXIN) | 34.3% | 69.4% |
| Upstart Holdings (UPST) | 14.0% | 68.4% |
| Standard Nuclear (STDN) | 18.8% | 61.3% |
| Precigen (PGEN) | 11.7% | 55.4% |
| Nu Holdings (NU) | 22.8% | 22.5% |
| Karman Holdings (KRMN) | 14.4% | 56.2% |
| Himax Technologies (HIMX) | 29.2% | 70.2% |
| Dave (DAVE) | 16.7% | 23.6% |
| Carlyle Group (CG) | 27.4% | 22% |
| Almonty Industries (ALM) | 10.8% | 38% |
Let's uncover some gems from our specialized screener.
REalloys (ALOY)
Simply Wall St Growth Rating: ★★★★★☆
Overview: REalloys Inc. is a North American company specializing in rare earth metals and permanent magnets, with a market cap of $569.84 million.
Operations: The company's revenue is generated entirely from its Metals & Mining - Miscellaneous segment, amounting to $1.87 million.
Insider Ownership: 35.6%
Revenue Growth Forecast: 65.8% p.a.
REalloys Inc. demonstrates significant growth potential with a forecasted revenue increase of 65.8% annually, outpacing the US market's average. Despite recent financial losses, its strategic initiatives, including a partnership with JS Link to develop a rare earth magnet manufacturing platform and collaborations with the U.S. Army for mineral processing facilities, position it well for future expansion. The company's inclusion in multiple indices highlights its growing prominence in the sector despite current financial volatility and limited insider trading activity.
- Get an in-depth perspective on REalloys' performance by reading our analyst estimates report here.
- Insights from our recent valuation report point to the potential overvaluation of REalloys shares in the market.

Corcept Therapeutics (CORT)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Corcept Therapeutics Incorporated is a biopharmaceutical company focused on discovering and developing treatments for severe endocrinologic, oncologic, metabolic, and neurologic disorders in the United States, with a market cap of $11.92 billion.
Operations: The company's revenue is primarily generated from the discovery, development, and commercialization of pharmaceutical products, amounting to $830.81 million.
Insider Ownership: 10.7%
Revenue Growth Forecast: 25.6% p.a.
Corcept Therapeutics is poised for significant growth, with revenue and earnings expected to increase substantially above market averages. Despite recent insider selling, the company has raised its 2026 revenue guidance to US$1.1 billion-US$1.2 billion, reflecting confidence in its business strength. The European Medicines Agency's positive recommendation for relacorilant enhances its growth prospects in oncology treatment markets. However, profit margins have declined compared to last year, indicating potential challenges ahead despite robust growth forecasts.
- Click here and access our complete growth analysis report to understand the dynamics of Corcept Therapeutics.
- The analysis detailed in our Corcept Therapeutics valuation report hints at an deflated share price compared to its estimated value.
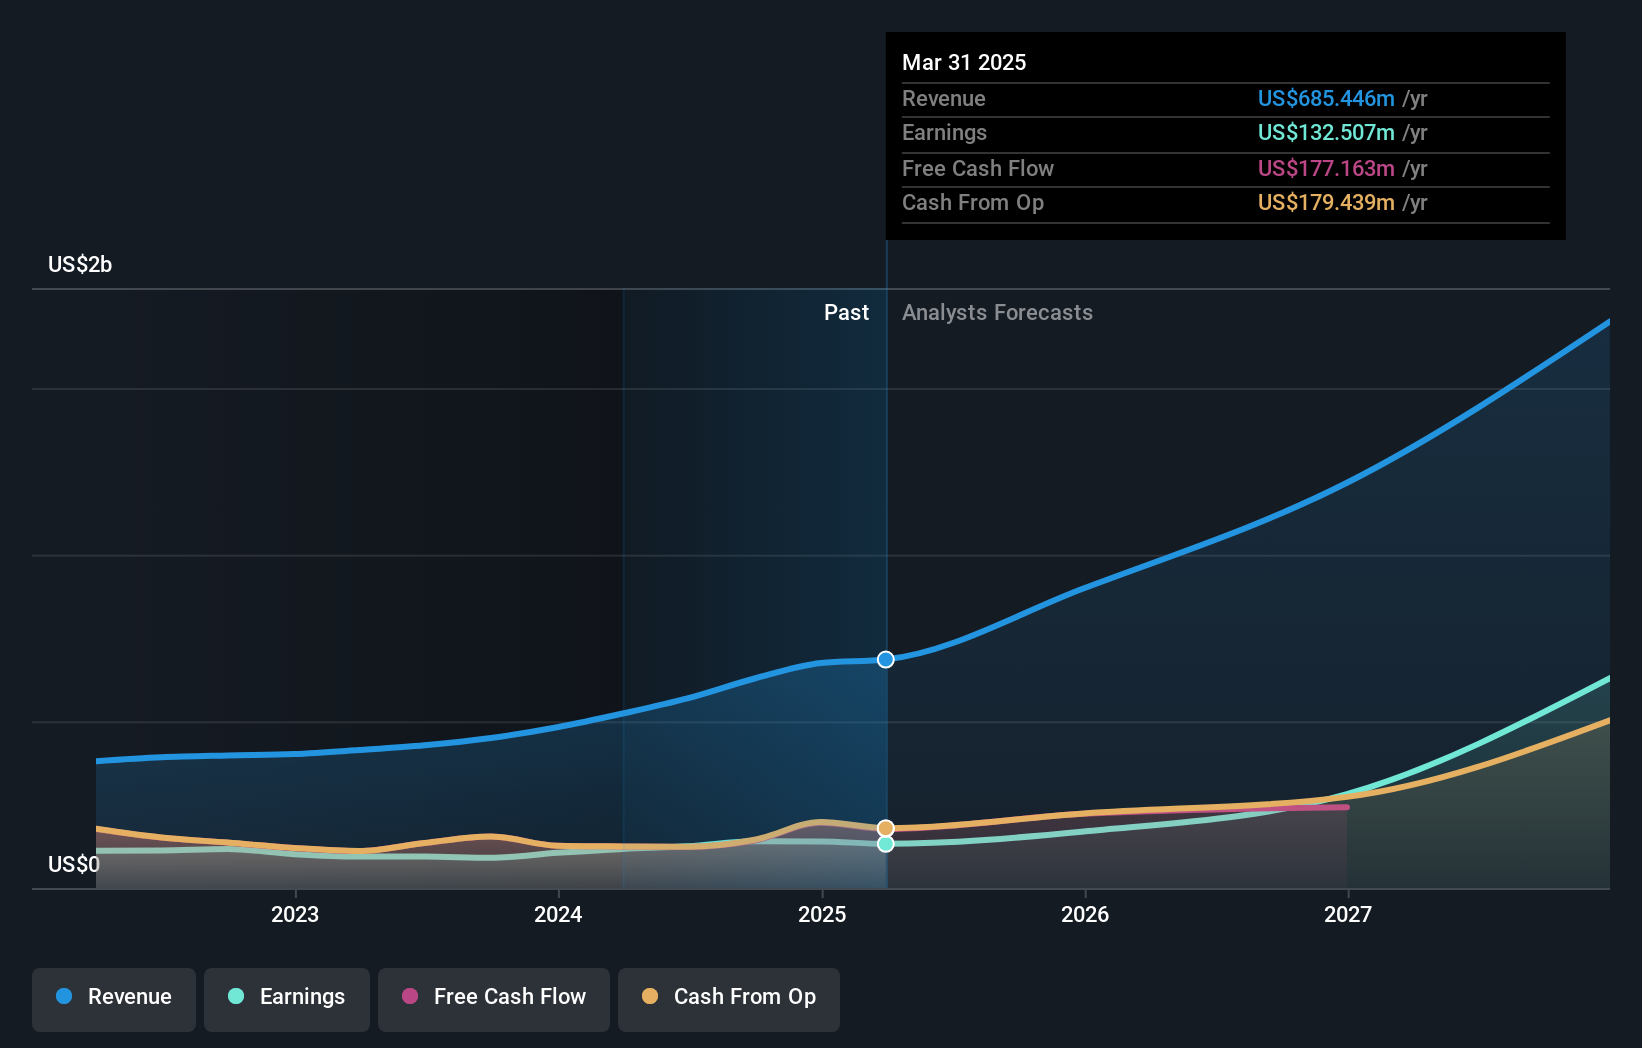
Hesai Group (HSAI)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Hesai Group develops, manufactures, and sells three-dimensional LiDAR solutions across Mainland China, Europe, North America, and internationally with a market cap of $2.58 billion.
Operations: Hesai Group generates revenue through the development, manufacturing, and sale of three-dimensional LiDAR solutions across various global markets including Mainland China, Europe, and North America.
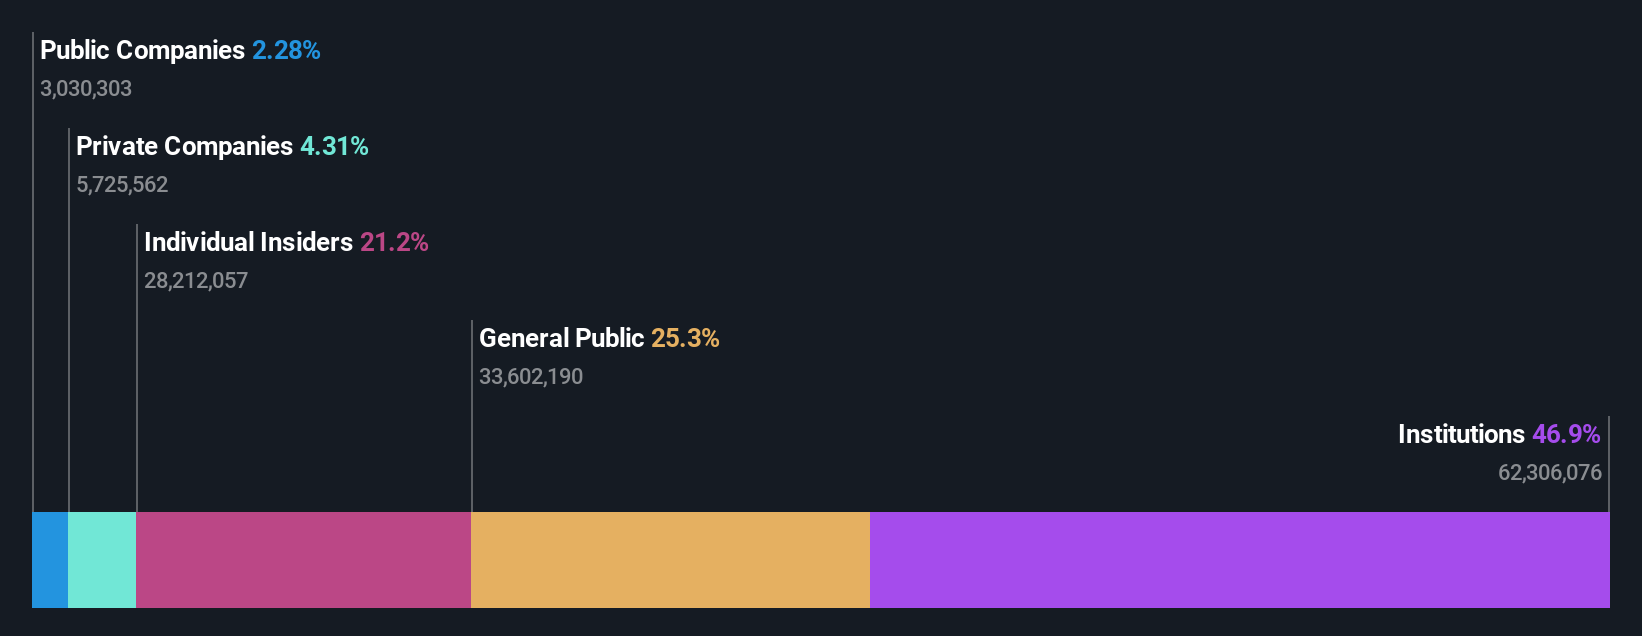
Insider Ownership: 17.4%
Revenue Growth Forecast: 25.6% p.a.
Hesai Group demonstrates strong growth potential, with earnings expected to increase significantly at 30.5% annually, outpacing the US market. Revenue is also forecasted to grow at a rapid 25.6% per year. Recent earnings showed substantial improvement, with net income rising from CNY 44.09 million to CNY 70.55 million in Q2 2026. Despite being dropped from the S&P Global BMI Index, analysts agree on a potential stock price rise of 63.2%, trading below fair value estimates by 14.3%.
- Click to explore a detailed breakdown of our findings in Hesai Group's earnings growth report.
- The valuation report we've compiled suggests that Hesai Group's current price could be inflated.
Seize The Opportunity
- Click this link to deep-dive into the 179 companies within our Fast Growing US Companies With High Insider Ownership screener.
- Contemplating Other Strategies? Rare earth metals are the new gold rush. Find out which 36 stocks are leading the charge.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com