


Will $0.75 Dividend Reaffirmation Change Annaly Stock's Narrative
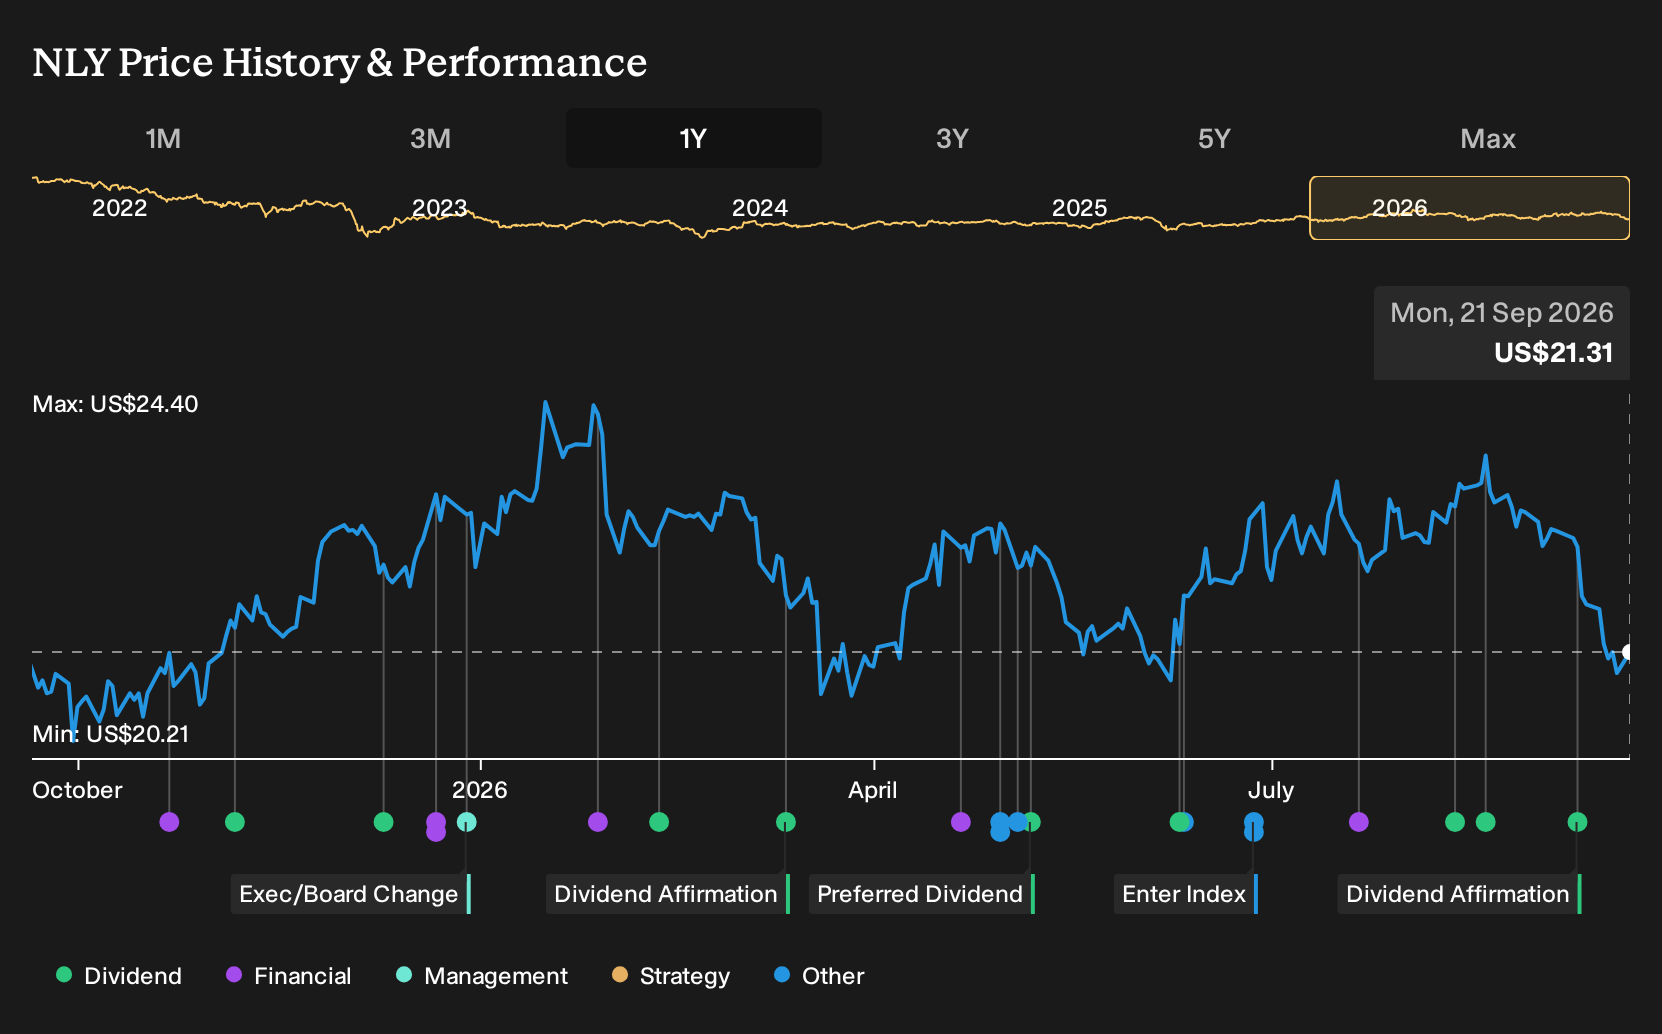
- Annaly Capital Management declared a Q3 2026 cash dividend of $0.75 per share, paid on October 30 to shareholders of record on September 30, with the ex dividend date also on September 30, an event that has already occurred.
- The mortgage REIT trades on a P/E of about 5.7x, which is close to peers yet below the broader sector. Internal models and recent equity raises point to earnings support that some investors view as inconsistent with this multiple.
- We will examine how Annaly Capital Management's investment narrative interacts with the reaffirmed $0.75 dividend and the current valuation debate.
Annaly Capital Management Investment Narrative Recap
To own Annaly Capital Management, you need to be comfortable with a mortgage finance model that lives and dies on interest rate moves, spread behavior, and hedging discipline. You are effectively backing management’s ability to manage agency MBS, residential credit, and MSR exposure while financing mostly through higher risk wholesale funding.
The reaffirmed Q3 2026 dividend of US$0.75 per share signals confidence in earnings available for distribution, but it does not change the key short term swing factor. The main catalyst remains how quickly improved financing costs and economic leverage show up in run rate earnings. The biggest risk is prolonged rate volatility that keeps hedging costs elevated and pressures spreads.
The most relevant announcement for this dividend discussion is the combination of the US$0.75 payout with Annaly Capital Management’s roughly 5.7x P/E, which sits close to peers and below the broader Mortgage REITs sector on about 8.3x. That gap has led some investors to frame the stock as potentially undervalued relative to its earnings profile.
Viewed next to the company’s Fair Ratio model output, which points to a higher P/E than the market is giving today, the reaffirmed dividend keeps attention on execution. The key question for catalysts is whether improved financing costs, MSR opportunities, and equity already raised translate into earnings that consistently support that payout while offsetting risks from rate volatility and mortgage spread moves.
What The Analyst Case Implies For Annaly Capital Management
Annaly Capital Management's narrative projects US$2.7 billion revenue and US$2.3 billion earnings by 2029. This assumes 3.7% yearly revenue growth and an earnings increase of about US$400 million from US$1.9 billion today.
Uncover how Annaly Capital Management's fair value indicates a 13% potential upside to its current price before the market closes the discount.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$24 and about US$28 per share, all above Annaly Capital Management’s recent US$21.05 price. Those private investors focus on revenue and earnings potential. You then need to weigh that optimism against interest rate volatility, mortgage spread risk, and housing market uncertainty. Explore the full spread of views before forming your own stance.
Explore 2 other Annaly Capital Management fair value estimates, including one that suggests potential upside of up to 32% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Annaly Capital Management research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Annaly Capital Management. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Annaly Capital Management's overall financial health at a glance.
Looking For More Investment Ideas Beyond Annaly Capital Management?
If Annaly Capital Management helps frame how you think about income, risk, and valuation, it can be useful to line that view up against a wider set of stocks that share some of those traits but with different balance sheets, payout profiles, or risk scores.
- For investors who want income with a focus on resilience, scan a 7 dividend fortresses to find opportunities that aim to pair higher yields with more durable cash flows.
- If capital preservation matters as much as return potential, compare Annaly Capital Management with a 30 resilient stocks with low risk scores that scores well on stability and downside control.
- When you want to cast a wider net beyond well known tickers, broaden your watchlist with a 17 high quality undiscovered gems that combines quality fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com