


How Investors Are Reacting To Georg Fischer (SWX:GF) FTSE All World Removal
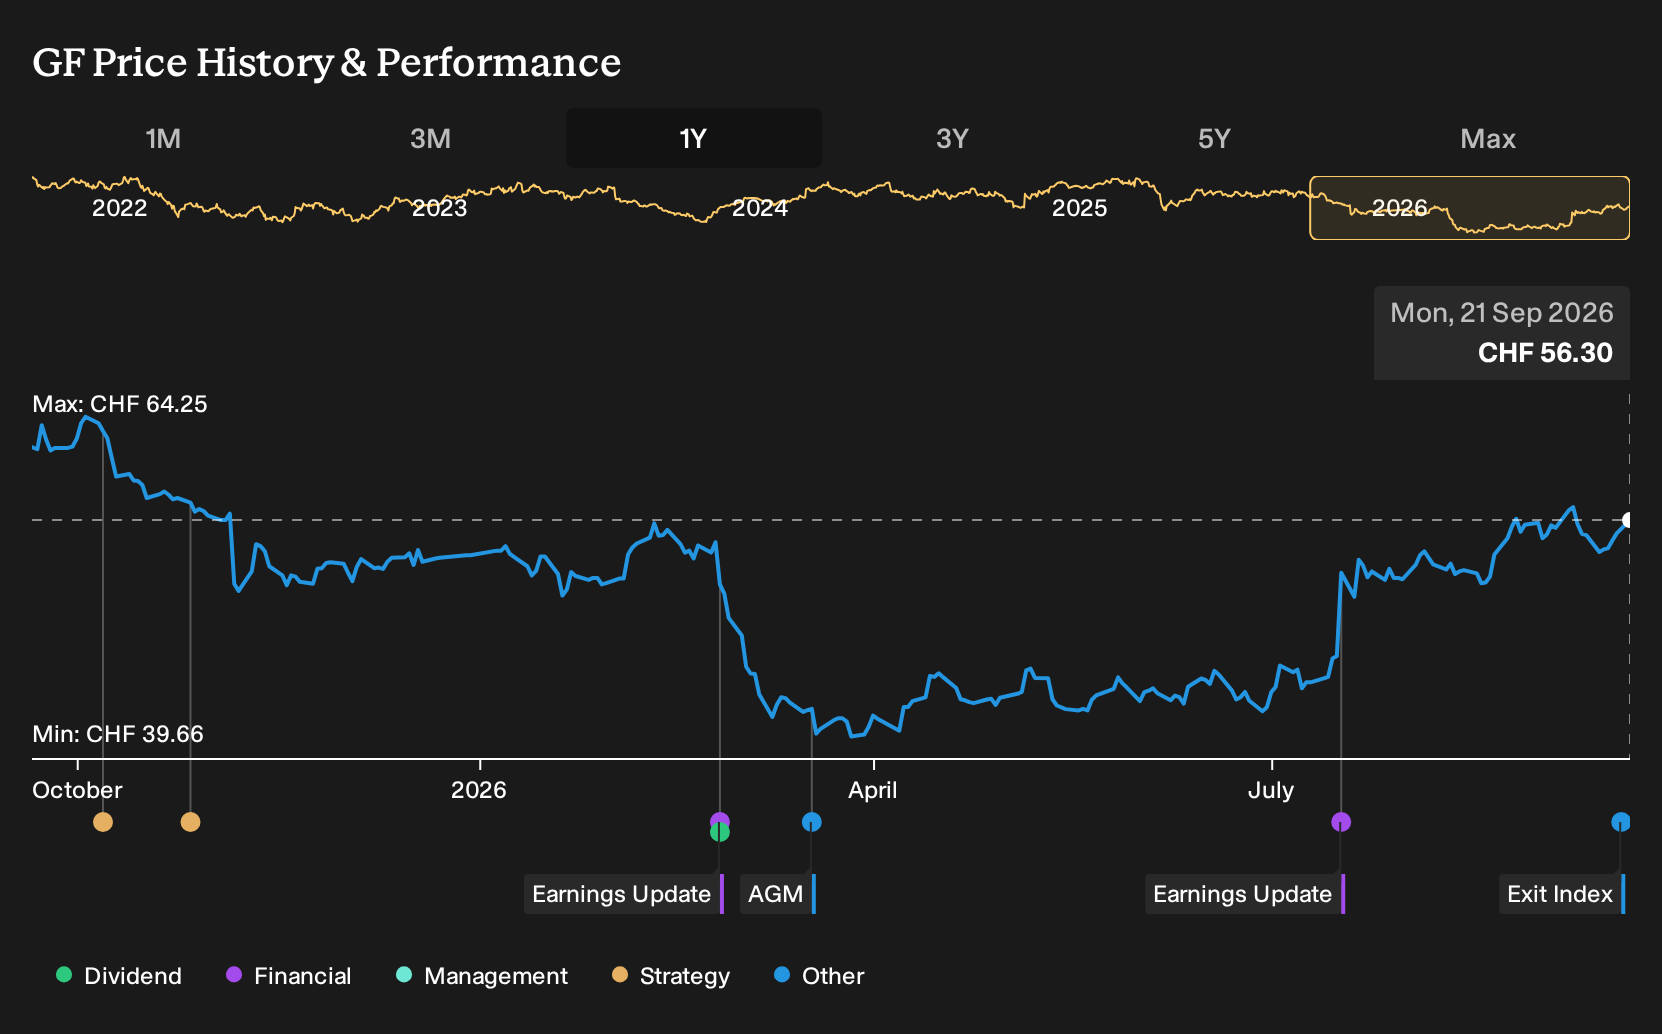
- Georg Fischer was removed from the FTSE All-World Index (USD) on 19 September 2026, reducing its presence in a widely tracked global benchmark.
- The exclusion may add pressure to Georg Fischer’s shift toward higher-margin flow solutions, as passive index demand and visibility both decline.
- This article examines how Georg Fischer’s investment narrative interacts with its FTSE All-World exclusion and what that may mean for investors.
Broaden your options by checking Georg Fischer against a curated 174 high quality undervalued stocks that could be better placed to attract index flows and passive capital over time.
Georg Fischer Investment Narrative Recap
To own Georg Fischer you need to be comfortable with a business that is still reshaping itself around flow solutions while currently reporting a loss of CHF 55.0 million on CHF 3.1b in revenue. The short term story hinges on making that portfolio transition pay off in higher quality earnings. Losing FTSE All-World inclusion may affect short term trading flows, but it does not change the operational work ahead.
The biggest near term risk sits in execution and funding. Interest costs are not well covered by earnings and the dividend is not fully supported by profits or free cash flow. On top of that, exposure to cyclical construction and infrastructure demand and volatile FX can still unsettle the path to cleaner profitability.
There are no fresh company announcements directly tied to the FTSE All-World exit, so the most important context remains the existing plan to become a focused Flow Solutions group. That roadmap relies on integrating acquisitions like Uponor and VAG and on ongoing portfolio simplification away from legacy casting and machining activities.
For you this means watching operational delivery rather than index status. Progress on synergies, order intake in water and building flow systems, and any updates on financing costs and dividend coverage will matter more for the medium term catalyst than the benchmark removal itself, even if passive flows shift around the stock in the short run.
Georg Fischer Consensus Setup Behind The Numbers
Georg Fischer's analyst playbook hinges on a clear set of forecasts that you can pressure test for yourself. The current loss of CHF 55.0 million is expected to flip to earnings of CHF 450.3 million by 2029, with profit margins moving from a reported loss position of 1.8% to 12.7%. To get there, the sell side assumes revenue grows by 4.9% a year over the next three years and that share count edges down by about 0.17% annually, which helps earnings per share, but only at the margin.
On these projections, the stock would be trading on a P/E of 13.5x 2029 earnings, compared with a current multiple of 76.7x that is skewed by today’s loss making base. That future P/E also sits below the 21.6x level cited for the GB Machinery industry. For you, the anchor question is simple: does a 4.9% yearly climb in revenue, a swing of CHF 505.3 million in earnings, and a double digit margin profile feel realistic for a flow focused group that is still digesting acquisitions and restructuring?
Georg Fischer's narrative projects CHF 3.6 billion revenue and CHF 450.3 million earnings by 2029. This requires 4.9% yearly revenue growth and an earnings increase of CHF 505.3 million from a current loss of CHF 55.0 million.
Uncover why Georg Fischer's fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Georg Fischer leans heavily on semiconductor and data center demand as a potential positive swing factor. The most optimistic analysts were already pencilling in revenue of about CHF 3.5b and earnings of roughly CHF 413.8 million by 2029 before this index removal. You should treat those pre event assumptions as flexible and compare them with your own expectations as sentiment shifts after the FTSE All World exit.
Explore 3 other Georg Fischer fair value estimates, including one that suggests it could be worth just CHF 58.81.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Georg Fischer research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Georg Fischer. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Georg Fischer's overall financial health at a glance.
Looking for more Georg Fischer investment ideas?
If the Georg Fischer story leaves you wanting a wider watchlist, it can help to set up a few targeted screens so you are not relying on a single stock or narrative.
- For investors who care most about quality businesses trading below what their fundamentals might justify, start with a curated 174 high quality undervalued stocks that keeps the focus on financial strength as well as pricing.
- If capital protection and steadier profiles matter to you, filter for 229 resilient stocks with low risk scores that score well on resilience so any single setback is less likely to dominate your portfolio.
- When you want fresh ideas beyond the usual large caps, broaden your radar with a 616 high quality undiscovered gems that highlights under-followed companies with solid underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com