


Is Reaffirmed Revenue Guidance Altering The Investment Case For Enova International (ENVA)?
- Enova International announced on 14 September 2026 that it withdrew applications with U.S. banking regulators for its planned Grasshopper Bancorp acquisition. The company also reaffirmed Q3 2026 revenue growth guidance of around 25% and full year 2026 growth of 20% to 25%.
- The combination of withdrawing a bank acquisition attempt and reiterating strong revenue expectations highlights Enova International’s focus on organic growth and its existing digital lending platform, rather than near term balance sheet expansion.
- We will now look at how Enova International’s reaffirmed double digit revenue outlook affects its broader investment narrative and risk balance.
Scan how Enova International’s decision reshapes your watchlist, and spot peers facing similar regulatory trade offs in our hand picked 30 resilient stocks with low risk scores group.
Enova International Investment Narrative Recap
To own Enova International, you need to believe its online lending engine and credit models can keep converting demand into profitable originations without relying on bank-style balance sheet optionality. The reaffirmed 20% to 25% revenue growth outlook for 2026 indicates that, in the near term, the core thesis still centers on execution on the existing platform.
The biggest short-term swing factor remains credit performance across nonprime borrowers. That side of the story does not materially change with the Grasshopper Bancorp withdrawal. The key risk is still any combination of tighter consumer lending rules or funding stress that could limit Enova International’s underwriting flexibility and unit economics.
The clearest announcement to focus on right now is the reaffirmed guidance for around 25% Q3 revenue growth and 20% to 25% for the full year 2026. For you as a shareholder or watcher, that shapes expectations around how effectively Enova International is using its technology and data capabilities to support both consumer and small business volume.
Those targets also intersect directly with the catalysts analysts highlight, including faster projected revenue growth compared with the broader US market and expectations for strong earnings expansion. The guidance update provides a current check on whether that high growth narrative still aligns with real-world origination trends, credit conditions, and any tightening in consumer finance regulation.
Enova International's current analyst narrative points to US$9.6b in revenue and US$665.0m in earnings by 2029, built on assumed yearly top line expansion of 78.3% and an earnings increase of about 1.9x from US$355.5m today.
Uncover how Enova International's fair value indicates a 62% potential upside to its current price that may not last much longer.
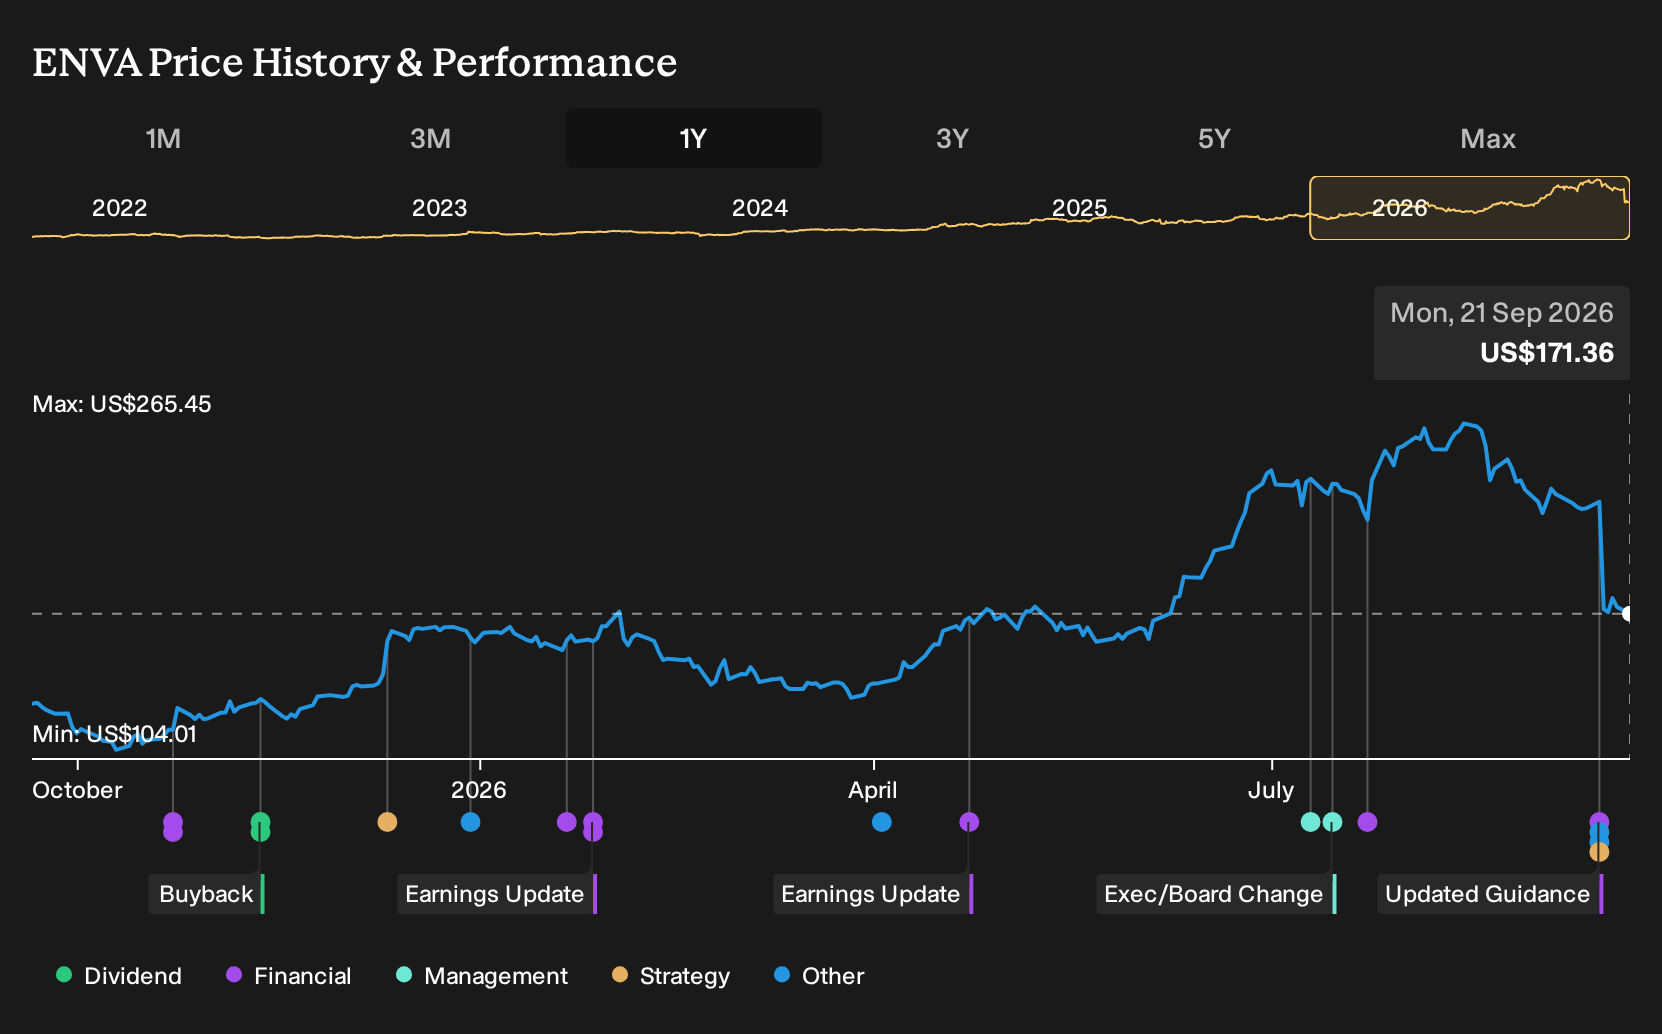
Exploring Other Perspectives
One alternate angle on Enova International focuses on the earnings risk from the Grasshopper deal no longer contributing the expected funding benefits. The most pessimistic analysts were already building in only about US$9.1b of 2029 revenue and US$657.9m of earnings, with a lower assumed 10.8x P/E, so your view on this withdrawal could either push that narrative even further or soften it. You can use that range to stress test your own assumptions and see where you sit on the spectrum.
Explore 2 other Enova International fair value estimates, including one that suggests as much as 44% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Enova International research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Enova International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enova International's overall financial health at a glance.
Looking for more Enova International investment ideas?
Once you have a view on Enova International, it can help to compare it with other opportunities using the Simply Wall St Screener so you can see where it fits in your broader watchlist.
- For investors who care most about balance sheet strength and staying power, scan our list of solid balance sheet and fundamentals (23 results), which filters for financial resilience and fundamental support.
- If income is a priority, widen your watchlist to companies with meaningful yield and payout support by checking out the 7 dividend fortresses in one place.
- When you want to get ahead of the crowd, cast a wider net across underfollowed opportunities using the 17 high quality undiscovered gems and see which lesser known stocks align with your thesis.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com