


Asian Market Stocks That May Be Trading Below Estimated Intrinsic Value
In recent weeks, the Asian markets have experienced a mixed performance, with Japan's stock indices rising due to easing oil prices and China's technology shares rebounding despite ongoing domestic demand challenges. Amid this landscape, investors might find opportunities in stocks that appear undervalued relative to their estimated intrinsic value, as these can potentially offer attractive entry points when market conditions stabilize.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Wacom (TSE:6727) | ¥842.00 | ¥1598.66 | 47.3% |
| Shizuki Electric (TSE:6994) | ¥1208.00 | ¥2298.03 | 47.4% |
| Rakus (TSE:3923) | ¥1082.00 | ¥2063.55 | 47.6% |
| PAL GROUP Holdings (TSE:2726) | ¥1486.00 | ¥2881.64 | 48.4% |
| Niterra (TSE:5334) | ¥7218.00 | ¥13807.95 | 47.7% |
| Ichikoh Industries (TSE:7244) | ¥565.00 | ¥1074.33 | 47.4% |
| HD Hyundai Energy SolutionsLtd (KOSE:A322000) | ₩118600.00 | ₩223397.20 | 46.9% |
| Dongwon Industries (KOSE:A006040) | ₩35500.00 | ₩70431.14 | 49.6% |
| Cheil Worldwide (KOSE:A030000) | ₩17430.00 | ₩34324.41 | 49.2% |
| AK Medical Holdings (SEHK:1789) | HK$4.915 | HK$9.57 | 48.7% |
Here we highlight a subset of our preferred stocks from the screener.
Cuckoo Holdings (KOSE:A192400)
Overview: Cuckoo Holdings Co., Ltd. and its subsidiaries manufacture and sell electric heaters and daily necessities both in South Korea and internationally, with a market cap of ₩839.12 billion.
Operations: Cuckoo Holdings Co., Ltd. generates revenue through the manufacturing and sale of electric heaters and daily necessities across both domestic and international markets.
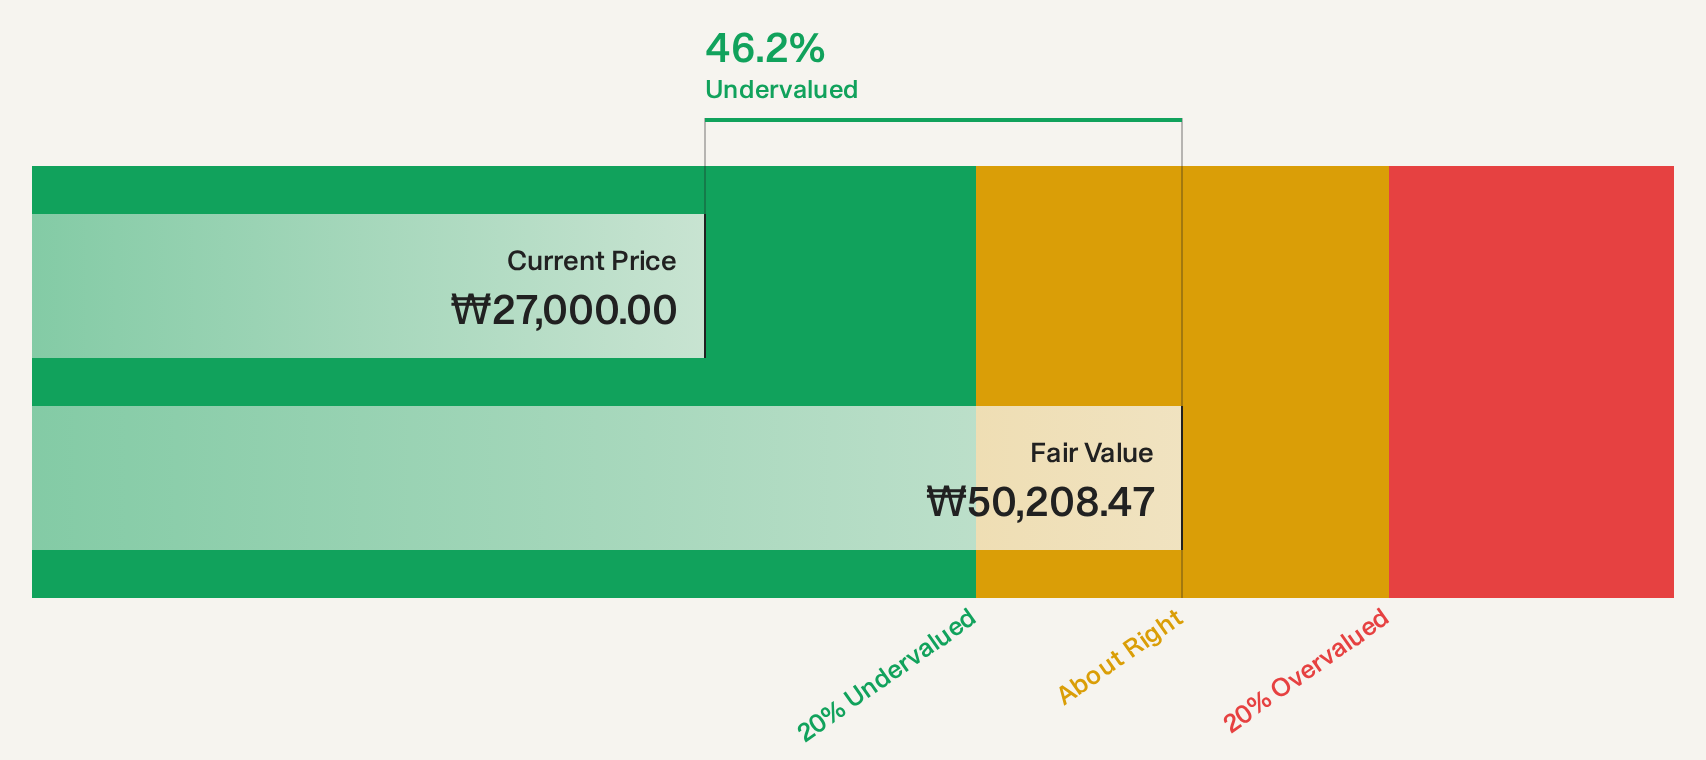
Estimated Discount To Fair Value: 46.4%
Cuckoo Holdings is trading at ₩27,000, significantly below its estimated future cash flow value of ₩50,409.03. Despite recent earnings growth of 40.6%, revenue growth is expected to lag behind the market at 6.2% annually, with earnings forecasted to decline by 0.3% per year over the next three years. The stock trades at a substantial discount of 46.4% below fair value and offers good relative value compared to peers and industry standards.
- Our growth report here indicates Cuckoo Holdings may be poised for an improving outlook.
- Dive into the specifics of Cuckoo Holdings here with our thorough financial health report.
Marco Polo Marine (SGX:5LY)
Overview: Marco Polo Marine Ltd. is an integrated marine logistics company operating in Singapore, Indonesia, Taiwan, Thailand, Malaysia, and internationally with a market cap of SGD524.50 million.
Operations: The company's revenue is derived from Ship Chartering Services, which generated SGD92.56 million, and Ship Building and Repair Services, contributing SGD51.57 million.
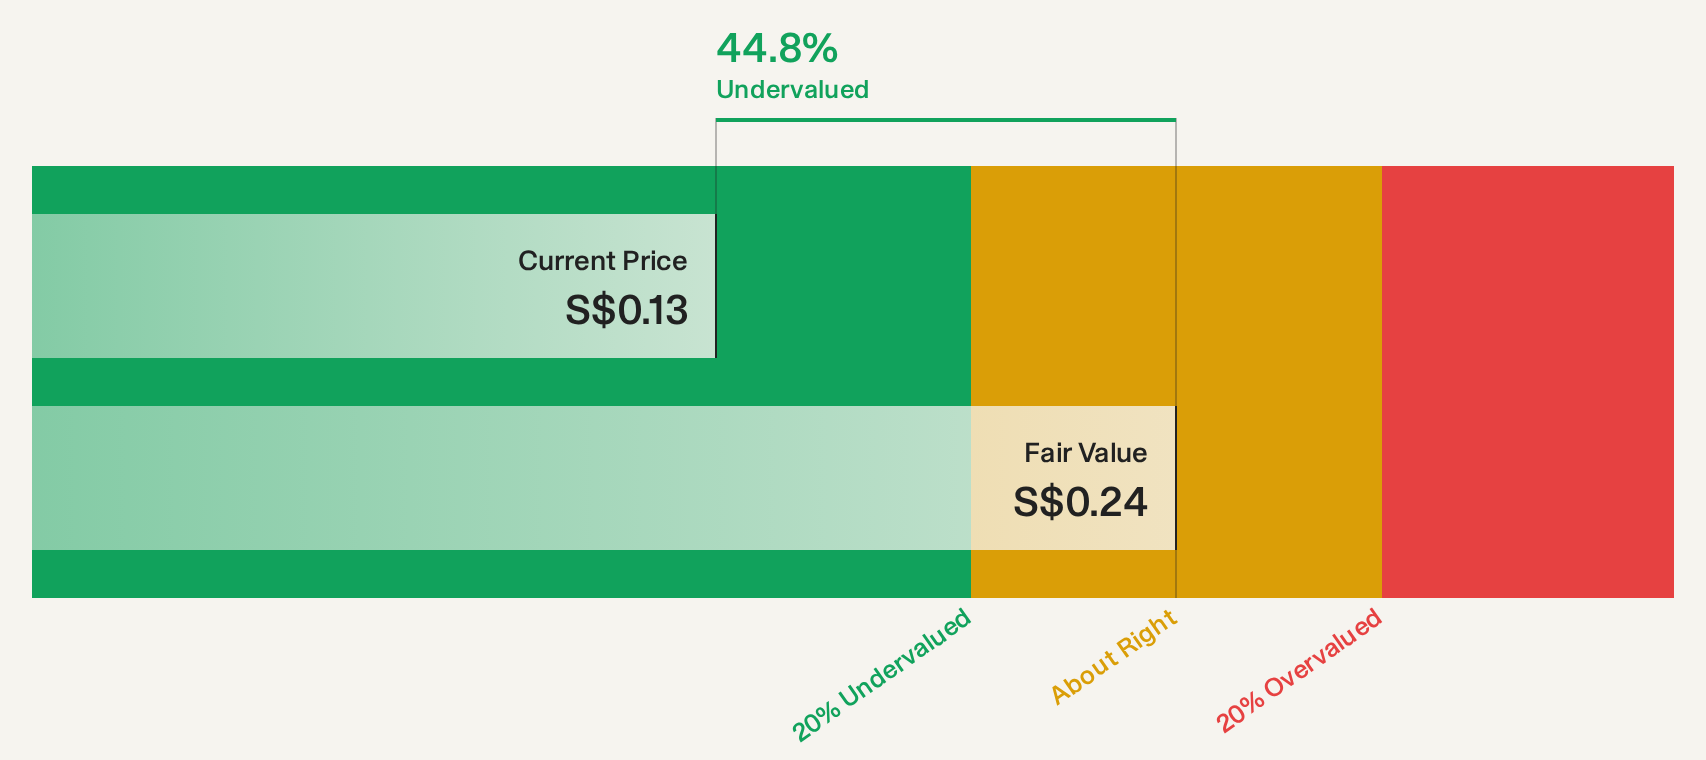
Estimated Discount To Fair Value: 44.1%
Marco Polo Marine is trading at S$0.13, below its estimated future cash flow value of S$0.24, suggesting undervaluation. Despite a forecasted earnings decline of 3.4% annually over three years, revenue is expected to grow at 19.67% per year, outpacing the Singapore market's average growth rate. Analysts agree on a potential stock price increase of 55.4%, and it trades at 44.1% below fair value estimates, highlighting its appeal based on cash flow analysis despite some large one-off items impacting results.
- Our expertly prepared growth report on Marco Polo Marine implies its future financial outlook may be stronger than recent results.
- Unlock comprehensive insights into our analysis of Marco Polo Marine stock in this financial health report.
ZYNP (SZSE:002448)
Overview: ZYNP Corporation is involved in the research, development, manufacture, and sales of automotive components both in China and internationally, with a market cap of CN¥6.75 billion.
Operations: The company's revenue primarily comes from Auto Parts Manufacturing, which generated CN¥3.91 billion.
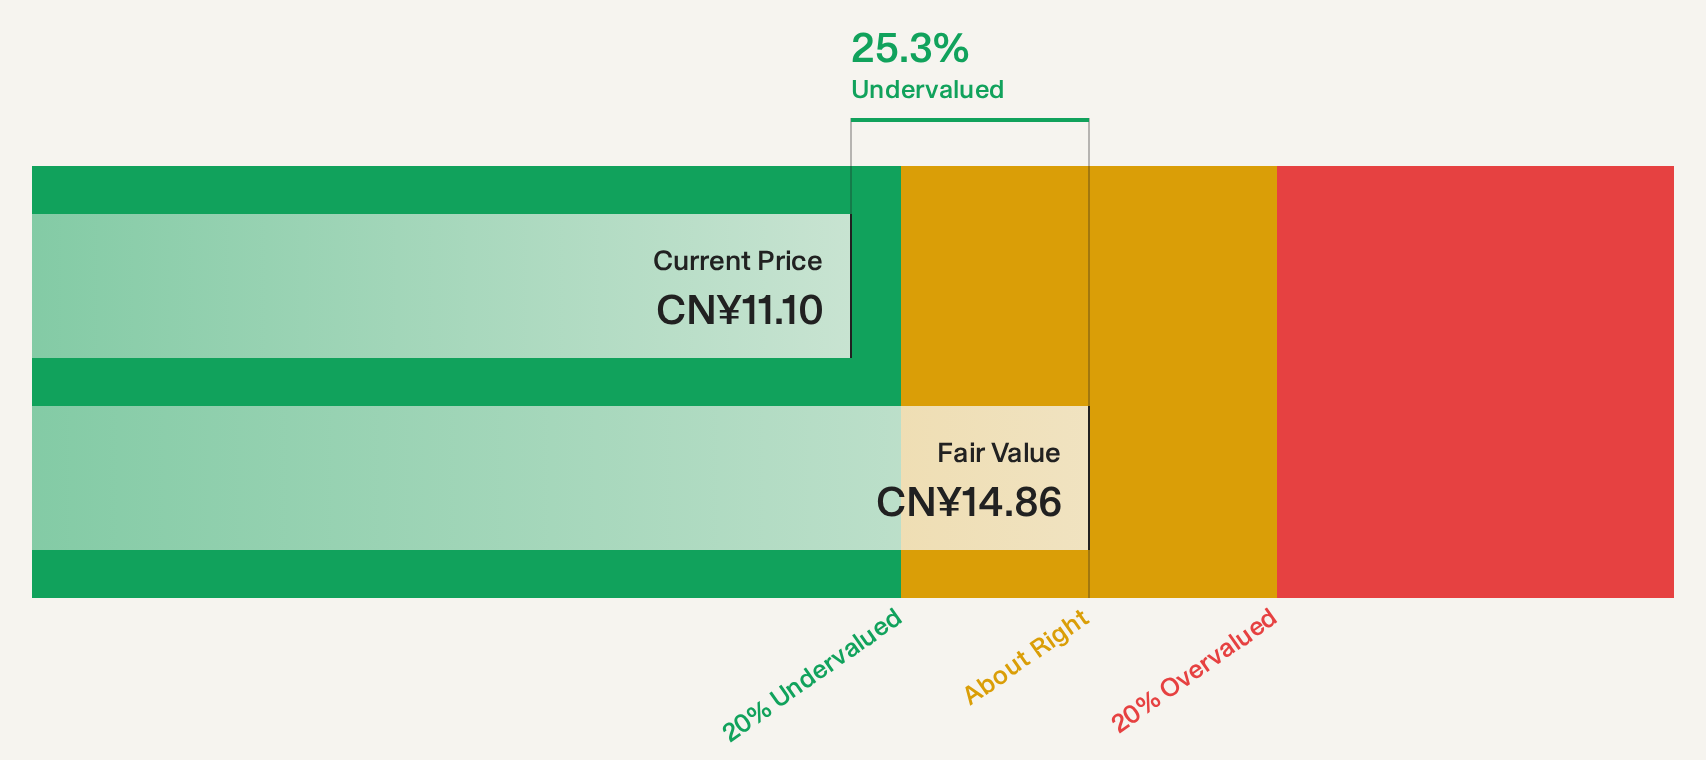
Estimated Discount To Fair Value: 23%
ZYNP Corporation, trading at CN¥11.47, is valued below its estimated future cash flow value of CN¥14.9, indicating potential undervaluation. The company's earnings grew by 100.2% over the past year and are forecast to continue growing at 15.96% annually despite being slower than the market average. Recent half-year earnings showed significant revenue growth to CNY 2,467.36 million from CNY 1,942.78 million a year ago, supporting its attractive valuation relative to peers and industry standards.
- In light of our recent growth report, it seems possible that ZYNP's financial performance will exceed current levels.
- Take a closer look at ZYNP's balance sheet health here in our report.
Make It Happen
- Unlock our comprehensive list of 78 Undervalued Asian Stocks Based On Cash Flows by clicking here.
- Have you diversified into these companies? Leverage the power of Simply Wall St's portfolio to keep a close eye on market movements affecting your investments.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com