


3 Energy Stocks To Watch As Oil And Gas Volatility Reshapes Returns
Energy markets are being pulled in several directions at once as geopolitics, inflation, central bank caution and supply chain snags all collide, and that mix is quietly reshaping risk and opportunity for large integrated oil, gas and energy producers. If you care about how shocks in oil and gas ripple through portfolios, this is a moment to pay attention. This article walks through three stocks from our screener that appear positively exposed to these cross currents and explains why they may deserve a closer look.
The three examples below are just a first pass, and the full screen surfaced 13 more large integrated producers with equally compelling narratives that are not covered here. To go straight to the source and identify your own high-conviction ideas, analyze the full universe through the Global Integrated Oil & Gas and Energy Producers screener.
Enerflex (TSX:EFX)
Enerflex plugs directly into the screener’s theme by supplying the modular natural gas and power systems that keep upstream projects running, with most of its roughly $2.6b in revenue coming from North America at $1.7b, and the business valued at about CA$3.9b.
Enerflex matters in this screen because it is not just exposed to natural gas price swings. It sells the infrastructure that producers rely on when they commit fresh capital to gas and power projects, which is where the most attractive economics can sit during volatile cycles.
"Increased regulatory and customer focus on emissions reductions and produced water management is driving demand for Enerflex's technology and services, seen in the performance and expansion of produced water projects in Oman, which should underpin margin strength and potentially grow average project value."
The key question is how one unresolved pressure on future pricing power and service mix ultimately shapes Enerflex’s ability to turn that demand into durable profitability.
That pricing power question is exactly what the full narrative for Enerflex unpacks, revealing how capital intensity, contract quality and emissions projects could be quietly reshaping Enerflex’s earnings profile.

Headwater Exploration (TSX:HWX)
Headwater Exploration is a pure-play upstream producer that gives direct exposure to moves in oil and gas prices through its focus on heavy crude and natural gas in Canada. It generated about CA$592 million from exploration, development and production, all in Canada, and carries a market value near CA$3.3b.
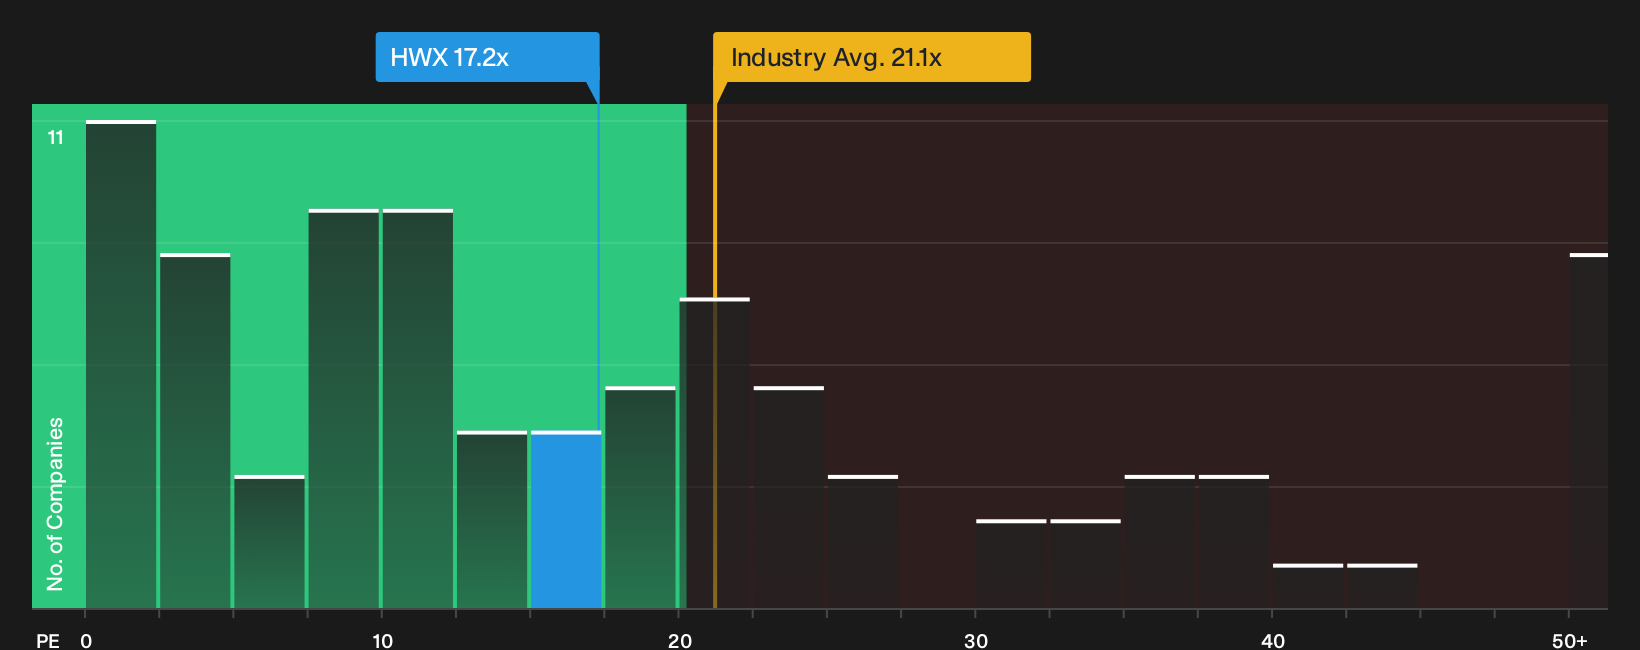
Headwater Exploration is closely linked to the Global Integrated Oil & Gas and Energy Producers theme because every dollar of its business comes from finding and pumping hydrocarbons, so cash flow responds quickly when commodity prices swing. With high ROE, a P/E below peers and a recently announced all-stock merger that would create a larger Clearwater-focused producer, investors are effectively assessing what happens when one unseen pressure shapes how much of that price volatility flows through to future returns.
That merger question is exactly what the 3 key rewards and 1 important warning sign helps you probe. It examines where valuation, scale and integration risk might be pulling in different directions.
HD Hyundai (KOSE:A267250)
HD Hyundai anchors the screener’s integrated energy theme through its oil refining arm, while also running shipbuilding and marine engineering that brought in about ₩37.5b, essential oil refining at roughly ₩51.6b, and construction equipment at around ₩13.2b, with a market cap near ₩14.9t.
HD Hyundai offers significant scale in integrated energy through its refining and heavy industrial arms, which can be attractive when oil price volatility boosts downstream earnings. One key consideration is how pressure on funding costs and capital-heavy projects affects potential returns from that cycle exposure.
Those capital demands put funding and execution under the microscope, which is exactly what the 5 key rewards and 1 important warning sign begins to unpack for HD Hyundai’s exposure to the energy cycle.

Seeking Alternatives Before The Crowd
Fresh ideas move first, and late money often gets caught chasing momentum while early entries are already flying. Scan new themes while it matters and get in early.
- Spot potential breakouts in smaller companies before attention floods in by running a focused search across 20 elite penny stocks with strong financials curated for financial strength and resilience.
- Ride the momentum behind next-generation computing by reviewing 25 quantum computing stocks that could benefit as demand for advanced processing power builds out across multiple industries.
- Track cash generating businesses with meaningful yield by scanning 2 dividend fortresses that pair substantial income potential with balance sheets built to handle shocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com