


Is Nokian Renkaat Oyj (HLSE:TYRES) Fully Valued After Its New Hakkapeliitta 01 Launch?
Nokian Renkaat Oyj (HLSE:TYRES) just linked product history with fresh technology as it marked 90 years of Hakkapeliitta winter tires and rolled out the new Hakkapeliitta 01 with adaptive studs.
The product milestone lands after a powerful run in Nokian Renkaat Oyj’s shares, with a 90-day share price return of 32.53% and a year-to-date gain of 65.91%. The 1-year total shareholder return of 105.11% contrasts with a 5-year total shareholder return that is down 33.88%, suggesting momentum has improved recently compared with the longer-term record.
Scan Nokian Renkaat Oyj’s winter-tire catalyst alongside other potential breakouts by comparing it with a curated 616 high quality undiscovered gems that share strong fundamentals yet still fly under most radars.
After such a sharp rerating in Nokian Renkaat Oyj, with stronger recent returns set against a weaker 5 year record, does the current valuation still offer enough potential to justify the risk buyers take from here?
Most Popular Narrative: 20% Overvalued
The most followed valuation story on Nokian Renkaat Oyj pegs fair value at €13.33, which sits below the latest close of €16.01. This means the current share price leans ahead of that central estimate and places more weight on execution going right.
The long term goal to reach €1.8b to €2b net sales with segment EBITDA above 24% and segment operating profit above 15% by 2029 requires a large uplift from a Q1 2026 segment EBITDA margin of 10.8%. Any slowdown in execution on price mix or efficiency plans would leave earnings and return metrics short of current expectations.
See why 2 investors see Nokian Renkaat Oyj as 20% overvalued.
Result: Fair Value of €13.33 (OVERVALUED)
Still, if Nokian Renkaat Oyj delivers on its €1.8b to €2b net sales ambition and pushes segment EBITDA above 24%, this overvaluation argument could weaken quickly.
Find out about the key risks to this Nokian Renkaat Oyj narrative.
Another View: SWS DCF Signals Undervaluation
The analyst narrative argues that Nokian Renkaat Oyj looks about 20% overvalued at €16.01 versus a €13.33 fair value, yet the SWS DCF model points the other way. On that framework, estimated future cash flows equate to about €17.96 per share. This frames the current quote as roughly 11% below that mark. Which lens do you find more convincing for your own valuation work?
Look into how the SWS DCF model arrives at its fair value.
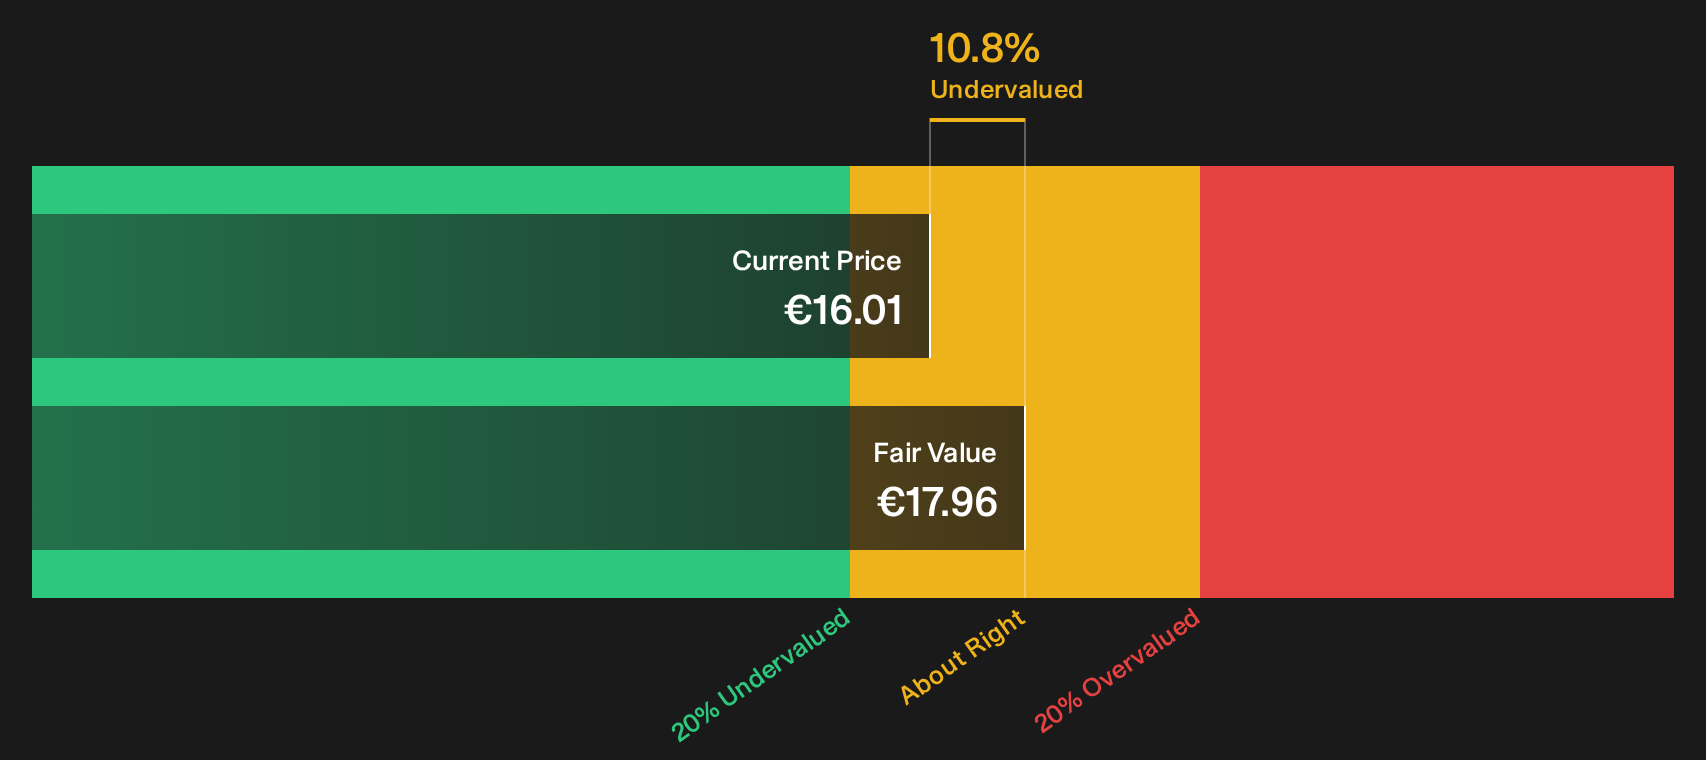
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nokian Renkaat Oyj for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 174 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Momentum in Nokian Renkaat Oyj looks strong on the surface. If you want to move quickly, test that story against the data and weigh both the upside and the risk signals in the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond Nokian Renkaat Oyj?
Do not stop with a single story like Nokian Renkaat Oyj. A wider watchlist can highlight new opportunities before they move and reveal blind spots you might miss.
- Target steadier compounding by scanning a 162 dividend fortresses that focus on meaningful income potential backed by stronger underlying fundamentals.
- Zero in on quality at a sensible entry point using a 174 high quality undervalued stocks that combines financial strength with appealing pricing signals.
- Protect the downside first by reviewing a 229 resilient stocks with low risk scores built around resilient balance sheets and more controlled risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com