


Is $2.5b Shareholder Payout Plan Altering The Investment Case For H World Group (HTHT)?
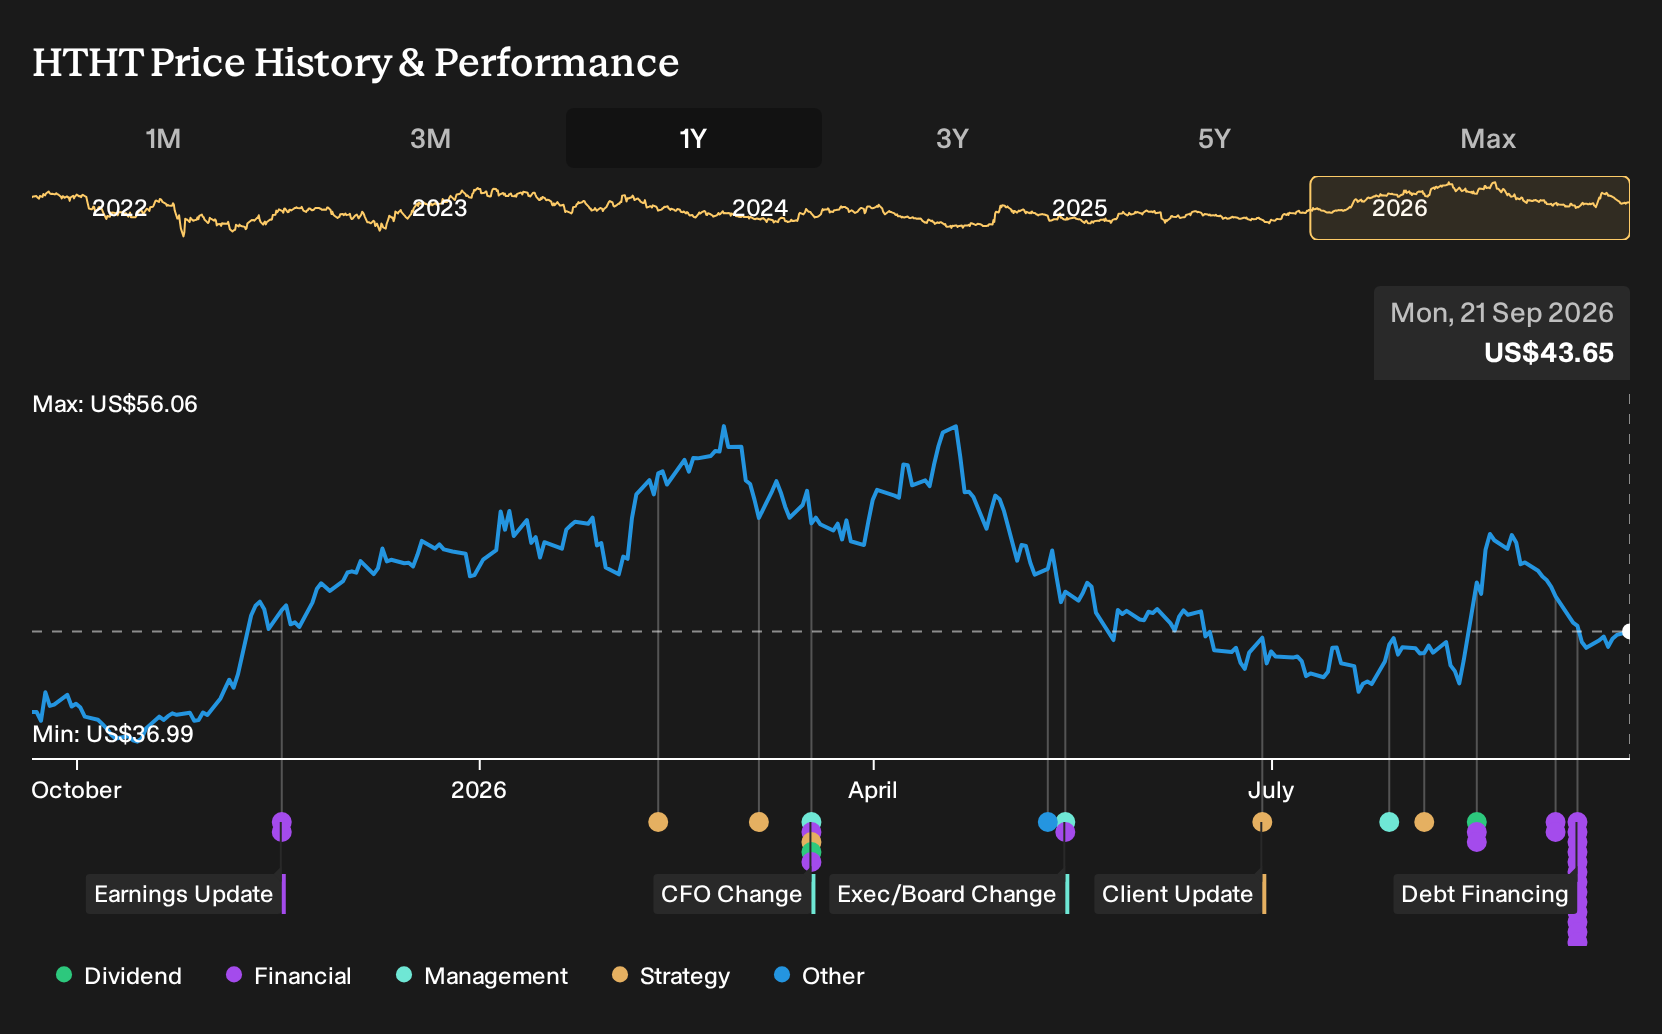
- H World Group completed a CNY 3.35b offshore senior unsecured bond issue priced at 2.25% and maturing in 2031, with the notes expected to list in Hong Kong and sold to non U.S. investors under Regulation S.
- The new CNY bonds add fixed rate funding that can support H World Group’s franchise heavy expansion and its recently approved US$2.5b shareholder payout plan.
- We will look at how H World Group’s investment narrative is reshaped by this low coupon CNY 3.35b bond financing and payout.
Scan how H World Group’s low coupon bond and fresh payout plan compare with other potential breakout opportunities in our hand picked 30 high quality undervalued stocks universe.
H World Group Investment Narrative Recap
To own H World Group, you basically need to believe its large manachised and franchised network can keep turning room nights and fees into consistent cash, even if RevPAR stays under pressure. The fresh CNY 3.35 billion at 2.25% extends fixed rate funding and supports near term execution on the hotel pipeline and digital initiatives without relying on more expensive capital.
The key short term catalyst remains execution on network expansion and upgrades while protecting margins as newer formats put pressure on legacy hotels. The biggest risk remains overexpansion into weaker lower tier markets and potential underutilization. The new bond itself does not materially change that demand and utilization risk, although it does increase focus on disciplined capital allocation.
The most relevant announcement here is the completed CNY 3.35 billion 2.25% senior unsecured bond maturing in 2031, issued to non U.S. investors. Fresh proceeds earmarked for general corporate purposes sit alongside an approved US$2.5 billion payout plan, so investors may monitor how H World Group balances shareholder distributions with funding for refurbishments and new openings.
Underwriters such as Goldman Sachs, J.P. Morgan, Bank of China and others on the deal indicate broad institutional interest in the credit, which in turn supports the asset light expansion story if deployment remains disciplined. As a potential catalyst, the bond gives H World Group more room to prioritize digitalization, loyalty and network growth. The operational test is whether RevPAR pressure, cannibalization of older hotels and significant supply additions are managed tightly enough that this new funding supports earnings quality rather than stretching the balance sheet.
H World Group Forecasts Behind the Bond and Payout Story
H World Group's current debt raise and payout plan sit alongside analyst projections that its revenue grows by 5.8% per year over the next three years, with earnings expected to move from CN¥5.0b today to CN¥7.2b by 2029 as profit margins shift from 19.3% to 23.5%.
H World Group's narrative projects CN¥30.7b revenue and CN¥7.2b earnings by 2029. This is built on 5.8% yearly revenue growth and an earnings increase of about CN¥2.2b from the current CN¥5.0b level.
Uncover why H World Group's fair value indicates a 37% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame H World Group’s huge hotel pipeline as the real catalyst. Before this bond news, they were modelling revenue climbing to CN¥33.2b and earnings near CN¥8.0b by 2029. Those views were set without this funding in mind, so you may want to compare how those expectations could shift now.
Explore another H World Group fair value estimate, including one that suggests a potential upside of up to 61% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your H World Group research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for H World Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate H World Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond H World Group?
Once you have a view on H World Group, it can help to compare it with other businesses that have different risk and return profiles using the Simply Wall St Screener.
- If capital preservation is high on your checklist, you could filter for companies with steadier profiles using our 30 resilient stocks with low risk scores.
- If you want income on top of potential price moves, you could scan for payment-heavy opportunities using the 7 dividend fortresses.
- If you are looking for potentially mispriced quality, you could compare H World Group with candidates in our 17 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com