


How Investors May Respond To UCB (ENXTBR:UCB) Breakthrough Therapy Status
- UCB reported that the FDA previously granted Breakthrough Therapy Designation to CIMZIA for preventing placenta-mediated adverse pregnancy outcomes in high-risk pregnant women with antiphospholipid syndrome who are positive for lupus anticoagulant, supported by preliminary IMPACT study data.
- The designation highlights a rare, underserved indication where CIMZIA could potentially extend its immunology footprint into high-complexity obstetric care, which aligns closely with UCB’s focus on specialty biologics and rare diseases.
- We will now look at how UCB's investment narrative could shift as CIMZIA gains Breakthrough Therapy status in high-risk APS pregnancies.
UCB Investment Narrative Recap
To own UCB, you need to believe the group can keep turning its neurology and immunology focus into durable cash flows despite pricing pressure and looming biosimilars. The big swing factor in the near term is execution on newer launches like BIMZELX, which need to offset pressure on mature drugs such as CIMZIA as competition and rebates build.
The CIMZIA Breakthrough Therapy Designation in high risk APS pregnancies looks directionally positive for the franchise but is not yet a clear short term earnings driver. The bigger immediate risk still sits with U.S. pricing, rebate intensity and any late stage R&D setbacks that could challenge the current growth and margin profile.
The APS related Breakthrough Therapy and prior Orphan Drug designations for CIMZIA align with UCB’s emphasis on specialty biologics and rare conditions. That supports an operating model that leans on high complexity indications and deeper physician engagement instead of broad primary care volume, which can matter when payers push harder on price.
BTD also brings closer FDA engagement and potentially faster review, which can affect how quickly any future indication might contribute if CIMZIA secures approval. You should still weigh this against existing risks around patent expiries, biosimilars and alternative therapies that could chip away at demand for chronic biologic treatments across the portfolio.
UCB's narrative projects €10.7b revenue and €2.8b earnings by 2029. This is based on an assumed 11.3% yearly revenue growth and an earnings increase of €1.2b from €1.6b today.
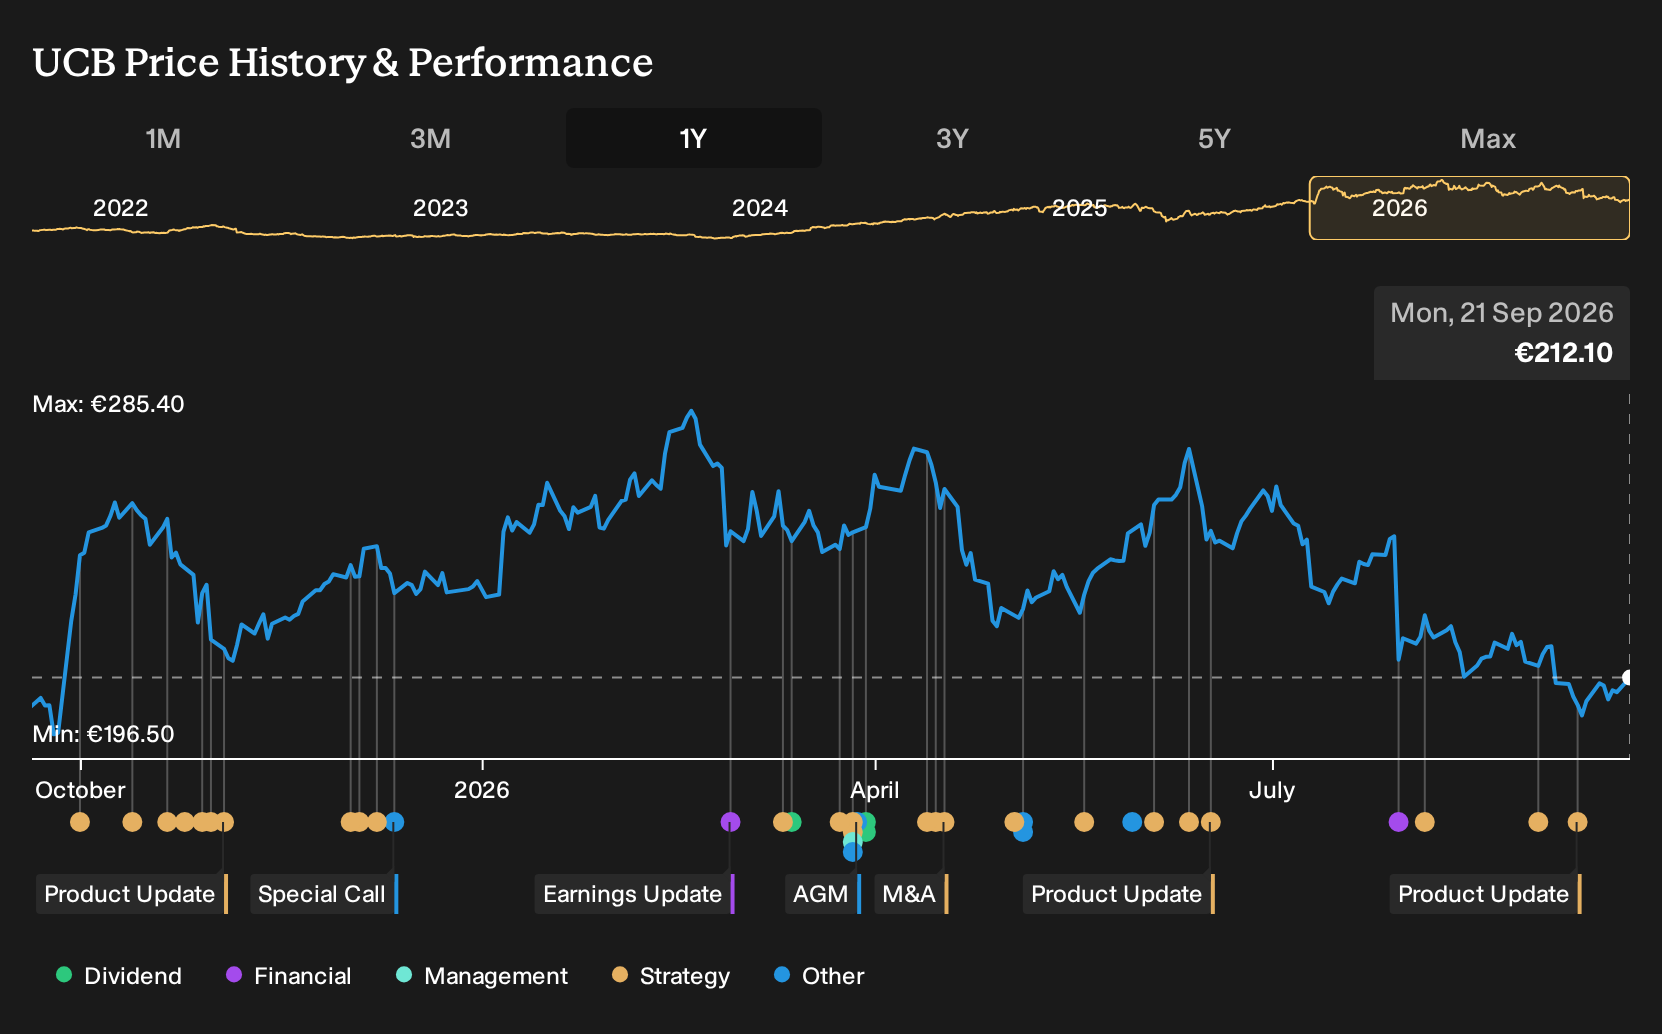
Uncover why UCB's fair value indicates a 36% potential upside to its current price, which could narrow quickly as more investors focus on UCB's pipeline.
Exploring Other Perspectives
Some of the most optimistic analysts already framed UCB as a “decade of growth” story, banking on revenue reaching about €11.5b and earnings of roughly €3.6b by 2029. You might see CIMZIA’s Breakthrough Therapy news as a fresh test of that upbeat view and a reason to compare several competing narratives side by side.
Explore 4 other UCB fair value estimates, including one that suggests up to 192% potential increase from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your UCB research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for UCB. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UCB's overall financial health at a glance.
Looking For More Investment Ideas Beyond UCB?
Once you have a view on UCB, it can help to widen the lens and compare it with other listed businesses that share similar quality traits or different risk profiles. The Simply Wall St Screener gives you a quick way to filter the market down to a focused watchlist that fits how you like to invest.
- If resilience matters most to you, you can start with companies that pair sturdier balance sheets with cleaner fundamentals by scanning this list of solid balance sheet and fundamentals (198 results) tailored to that profile.
- For those hunting for mispriced quality, you can filter for financially sound businesses trading below their estimated worth using a curated 174 high quality undervalued stocks that aims to cut through market noise.
- If you prefer stability over drama, you may look at companies with stronger risk scores and steadier characteristics by running through this 229 resilient stocks with low risk scores built around durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com