


EVT (ASX:EVT) Review Of A$800 Million Asset Sales Puts Fair Value Back In Focus
EVT Limited (ASX:EVT) has begun a wide-ranging review of its group structure after flagging around A$800 million of non core property for possible sale, a move closely watched by investors.
EVT shares have shown mixed momentum into this announcement. The 1 day share price return of 1.66% and year to date share price gain of 7.08% contrast with a 30 day share price return that is down 4.40%. The 3 year total shareholder return of 32.93% points to a stronger longer run track record than the 1 year total shareholder return of 3.42%.
Scan how EVT compares with other asset heavy restructurers by reviewing the hand picked list of solid balance sheet and fundamentals (12 results) now under pressure to re-rate on portfolio moves like this.
EVT now faces a simple trade off. The question is whether the prospect of recycling A$800 million of non core property into higher return projects still leaves more upside than downside at today’s share price, once valuation is on the table next.
Most Popular Narrative: 19% Undervalued
The most followed narrative pegs EVT's fair value at A$16.62 per share, above the last close of A$13.46. This puts the spotlight firmly on how management uses that A$800 million of potential property proceeds.
Analyst consensus expects capital unlocked from the 525 George Street divestment to drive growth, but this likely understates the potential for a dramatic balance sheet transformation. A substantial proportion of EVT's $2.3 billion property book is underutilized, and continued recycling of these assets on top of 525 could unlock capital for reinvestment at much higher returns, accelerating both revenue and earnings expansion well beyond current assumptions.
See why 0 investors see EVT as 19% undervalued.
Result: Fair Value of A$16.62 (UNDERVALUED)
Still, the bullish EVT narrative leans heavily on blockbuster film supply and premium cinema demand. Both of these could disappoint and leave high capex harder to justify.
Find out about the key risks to this EVT narrative.
Another View: EVT Looks Expensive On Earnings
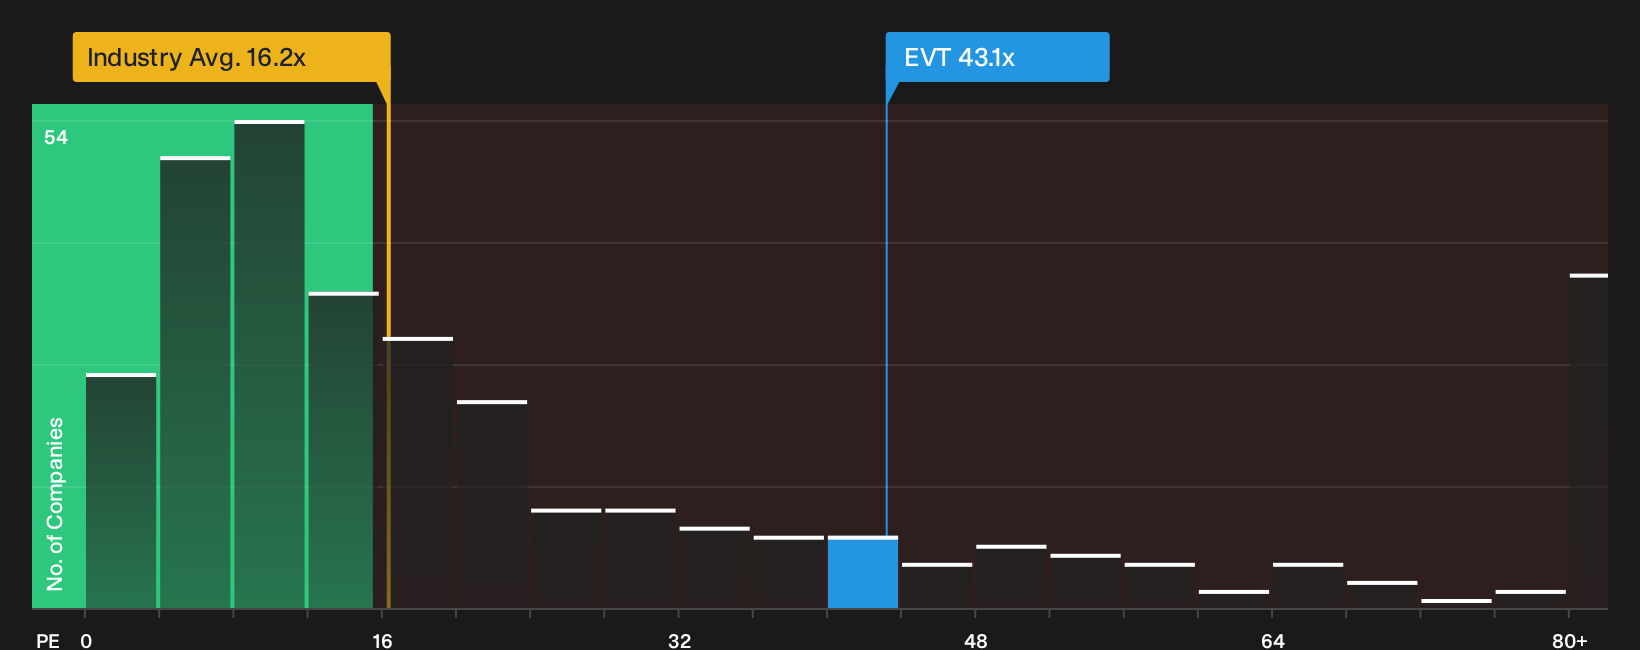
That A$16.62 fair value hinges on growth and margin forecasts. On simple earnings multiples, EVT screens differently. The current P/E of 43.1x is far higher than the global entertainment group average of 16.2x and above the peer set at 24.5x.
The fair ratio for EVT is 23.4x, which is much closer to those peer numbers. That gap means anyone paying today’s multiple is accepting less room for disappointment on future profits and interest costs.
So the question becomes simple: Are you comfortable paying a premium P/E for EVT when the fair ratio points closer to the pack, or do you prefer to wait for that gap to narrow?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around EVT can easily pull you in either direction. Move quickly to review the full picture and weigh both sides through the 2 key rewards and 2 important warning signs.
Looking for more EVT investment ideas?
If EVT has your attention, do not stop here. Use the Simply Wall Street Screener to compare fresh ideas and pressure test whether EVT still deserves a place in your portfolio.
- Target potential mispricing by reviewing the 6 high quality undervalued stocks that combine quality fundamentals with compressed valuations.
- Strengthen your income stream by assessing the 4 dividend fortresses that aim to pair higher yields with resilient payouts.
- Reduce portfolio stress by focusing on the 7 resilient stocks with low risk scores that score well on financial health and earnings stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com