


Intel (INTC), What Is Driving Fresh Attention Now?
Intel (INTC) has moved back into focus after a series of recent partnerships related to edge artificial intelligence, secure agent communication, and advanced chip manufacturing, raising fresh questions about how the stock reflects these collaborations.
Intel’s recent partnerships have arrived during a sharp swing in sentiment. The stock has posted a 30 day share price return of 20.57% and a year to date share price gain of 175.77%. The 1 year total shareholder return of 277.61% points to powerful momentum that has only recently begun to cool after a 90 day share price decline of 17.90%.
Scan where Intel’s recent AI surge sits in the wider chip story by comparing it with hand-picked 88 AI infrastructure stocks powering the same buildout in data centers and at the edge.
Intel now trades at US$108.60 with analyst targets clustered closer to US$116 and intrinsic models pointing well below that. The key question is which of those anchors comes closest to fair value once the recent surge is stripped back.
Most Popular Intel Narrative: 78.3% Undervalued
Intel’s most followed valuation story puts fair value far above the recent close of $108.60, framing the current price as a steep discount and putting a lot of weight on long term cash generation and architecture advantages.
Reasons I bought Intel:
• x86 software. a lot of existing software has been created for the x86 architecture and additionally has likely been optimized to run on intel cpus due to them having been the consistent market leader for so long, which gives them an advantage over AMD.
• This is most noticed when comparing applications using IBOT or Intel Compiler
See why 72 investors see Intel as 78% undervalued.
According to Suen, the narrative behind that view pegs Intel’s fair value at $500.93 based on a discount rate of 11.31% and assumes the stock is 78.3% undervalued relative to that estimate. That sits in clear tension with an intrinsic value estimate of $79.62 from SWS DCF work, which points to a very different picture of what Intel’s future cash flows might support at today’s price.
Result: Fair Value of $500.93 (UNDERVALUED)
Still, Intel faces real pressure if the advantages of x86 software erode faster than expected, or if its foundry buildout fails to attract enough high-volume customers.
Find out about the key risks to this Intel narrative.
Another View: Intel Through The Cash Flow Lens
Intel’s crowd-favorite story leans on a fair value of $500.93, yet the SWS DCF model lands in a very different place. On that framework, the stock screens as overvalued, with a future cash flow value estimate of $79.62 versus the current $108.60 price. Which anchor feels more realistic when the narrative heat cools?
Look into how the SWS DCF model arrives at its fair value.
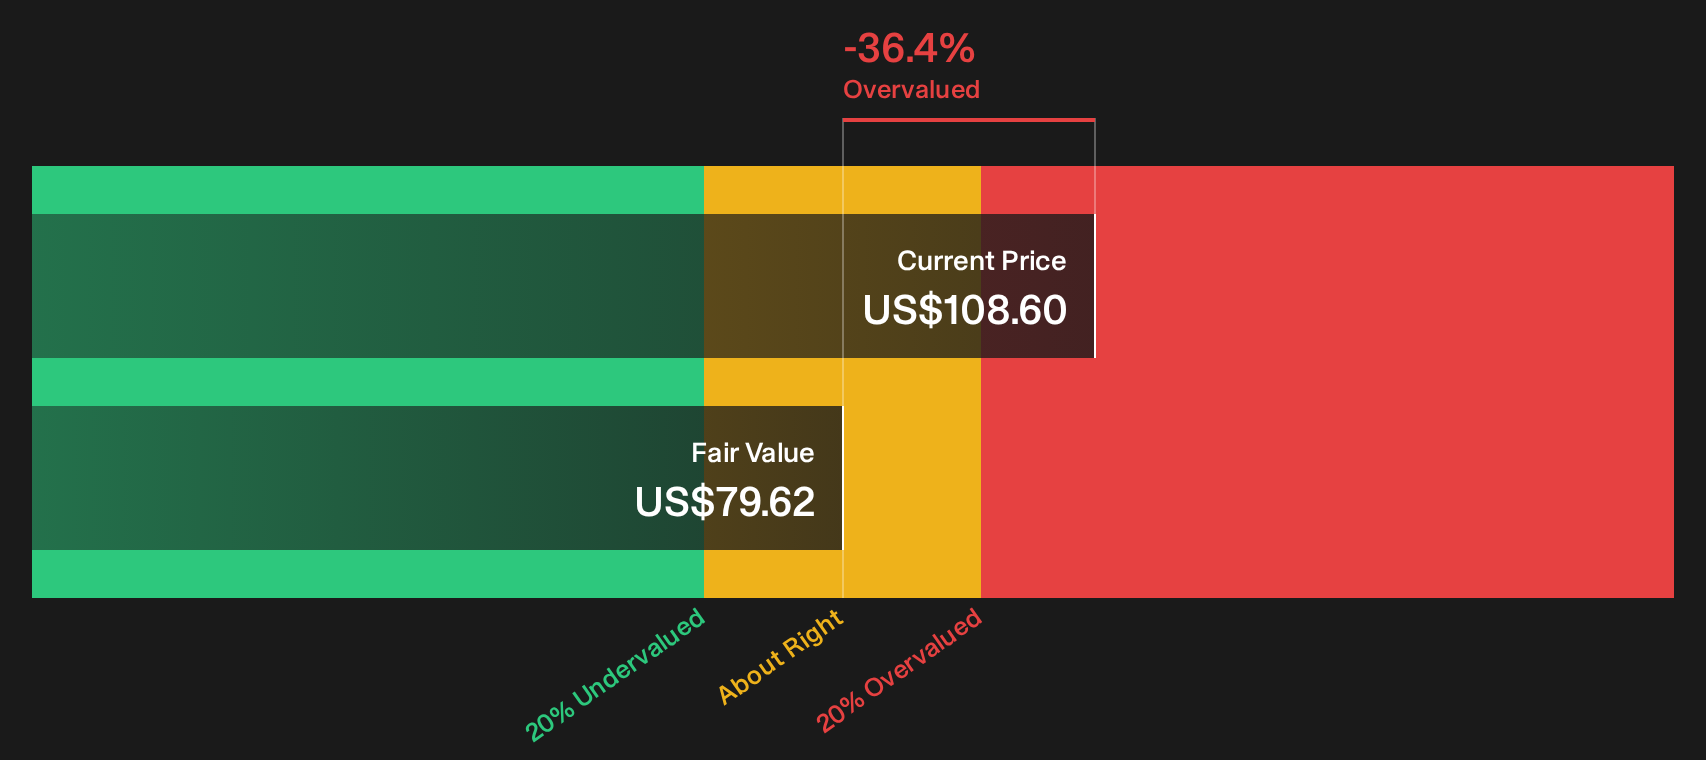
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Intel for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
So after all this optimism and debate around Intel, are you comfortable with where you land on it today, or still undecided and watching closely? Act quickly, pressure test the upside story for yourself, and then weigh it against the 1 key reward.
Looking for more investment ideas beyond Intel?
If you feel Intel is only one piece of your watchlist, now is the moment to widen the lens and line up your next potential moves.
- Explore potential mispricings by scanning a curated pool of companies that currently look beaten down yet appear fundamentally sound through the 35 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses with a history of robust payouts and durability using the 7 dividend fortresses.
- Reduce portfolio stress by filtering for companies with cleaner balance sheets and healthier foundations via the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com