


Kawasaki Kisen Kaisha (TSE:9107) After Its Buyback, Is The Stock Fully Valued
Kawasaki Kisen Kaisha (TSE:9107) has just wrapped up a sizeable share repurchase programme, buying back 44,429,000 shares, or 7.15% of its stock, for ¥122,480.51b.
At a share price of ¥3,497.0, Kawasaki Kisen Kaisha is giving investors a 90-day share price return of 38.60% and a year-to-date share price gain of 60.60%, while the 5-year total shareholder return of 437.96% points to strong longer term momentum. Recent buyback headlines appear to have reinforced this.
Compare Kawasaki Kisen Kaisha's buyback-fuelled momentum with other transport and logistics plays by scanning our curated list of list of solid balance sheet and fundamentals (21 results) for your next idea.
After a buyback that removed 7.15% of the float and a share price that has already sprinted higher, is most of Kawasaki Kisen Kaisha’s upside now in the rear-view mirror, or does valuation still leave room ahead?
Most Popular Narrative: 27% Overvalued
Against a last close of ¥3,497, the most followed narrative pegs Kawasaki Kisen Kaisha’s fair value at about ¥2,756. This implies the recent buyback-fuelled rally has taken the share price well ahead of that estimate while still assuming only moderate growth and disciplined capital returns.
The analysts have a consensus price target of ¥2756.36 for Kawasaki Kisen Kaisha based on their expectations of its future earnings growth, profit margins and other risk factors.
Given the current share price of ¥3427.0, the analyst price target of ¥2756.36 is 24.3% lower. Despite analysts expecting the underlying business to improve, they seem to believe the market's expectations are too high.
See why 2 investors see Kawasaki Kisen Kaisha as 27% overvalued.
Result: Fair Value of ¥2,756 (OVERVALUED)
Still, Kawasaki Kisen Kaisha’s high equity ratio and long term energy transport charters could cushion earnings swings and call into question the current overvaluation story.
Find out about the key risks to this Kawasaki Kisen Kaisha narrative.
Another View: Cash Flows Point To Undervaluation
Price targets say Kawasaki Kisen Kaisha looks 27% overvalued at around ¥3,497, yet our DCF model points the other way. Based on projected cash flows, the estimate comes in at about ¥3,859 per share, which is roughly 9% above the current quote. That difference presents a different question for investors to consider.
Look into how the SWS DCF model arrives at its fair value.
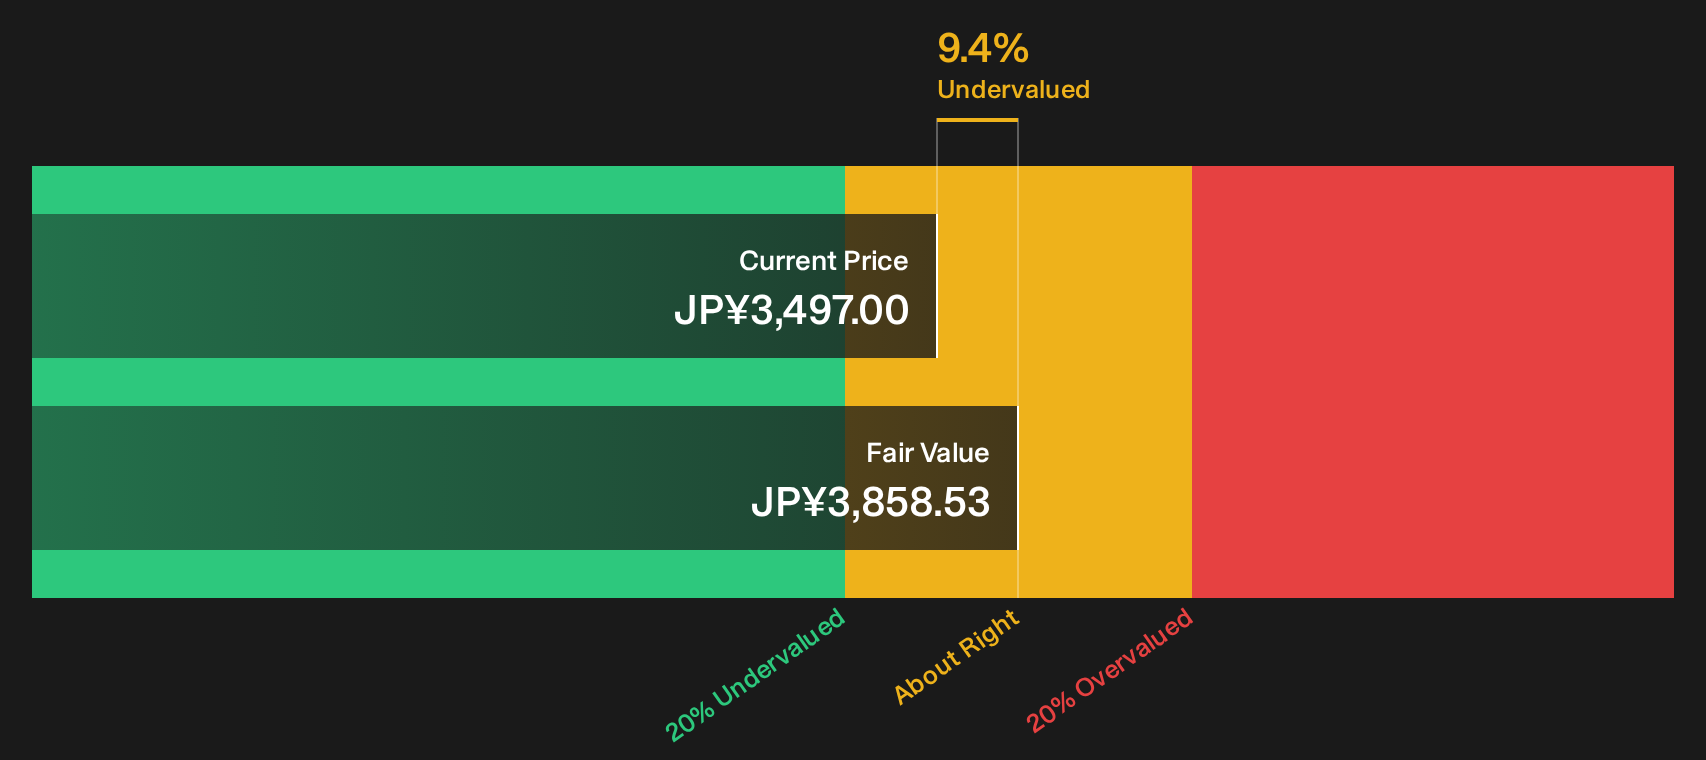
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kawasaki Kisen Kaisha for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mixed picture around Kawasaki Kisen Kaisha leaves you torn, move quickly, review the full breakdown, and weigh both sides using the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Kawasaki Kisen Kaisha?
If Kawasaki Kisen Kaisha has sharpened your focus on capital allocation, do not stop here. Widen your opportunity set with a few targeted screeners today.
- Target resilience first and look for companies with strong finances and steady footing by reviewing the 21 resilient stocks with low risk scores.
- Seek quality at a reasonable entry point and build your watchlist with potential mispriced opportunities through the 75 high quality undiscovered gems.
- Prioritise a blend of value and financial strength by scanning the 17 high quality undervalued stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com