


Chervon Holdings (SEHK:2285) Gets A New CEO After A Sharp Rally But Still Looks Pricey
Chervon Holdings (SEHK:2285) just made a sweeping leadership change that puts long time power tool executive Joseph Galli Jr. in the CEO seat, with Jeffrey P. Campbell stepping in to guide industrial and commercial sales.
The leadership reshuffle comes at a time when Chervon Holdings’ shares have picked up momentum, with a 30 day share price return of 23.53% and a 90 day gain of 57.50% from a latest close of HK$25.2. The 1 year total shareholder return of 16.53% points to a more measured longer term outcome overall.
Scan how other power tool and equipment players are reacting to leadership shifts and momentum moves by running through our curated list of 96 robotics and automation stocks aligned with Chervon Holdings' segment focus.
After a 57.50% move over 90 days and leadership now reshaped around Joseph Galli Jr., the real puzzle for Chervon Holdings is simple: Is most of the rerating already in the price, or is investors’ upside case only getting started?
Preferred Price-to-Earnings of 15x: Is it justified?
Valuation on Chervon Holdings today leans heavily on what investors are willing to pay for its earnings, and the current answer is a P/E of 15x based on the latest HK$25.2 close.
The P/E ratio compares the HK$25.2 share price to the earnings attributable to each share, which gives a quick read on how rich or cheap the stock looks relative to its profits. For a power tools and outdoor equipment manufacturer with global reach and HK$1,744.4m in revenue and HK$108.7m in net income, that multiple indicates what the market is pricing in for future earnings power.
Compared to the Hong Kong Consumer Durables industry average P/E of 11x, the 15x tag on Chervon Holdings suggests investors are paying a clear premium for this business. The market is also valuing the stock above an estimated fair P/E of 10.7x, which points to a richer level than the ratio some models indicate the shares could trend toward if sentiment cools or earnings do not keep pace.
At the same time, that higher valuation sits against a mixed earnings profile. The firm is forecast to grow earnings by 18.79% per year, which is quicker than the Hong Kong market expectation of 11.4% but still below the 20% threshold some investors use for very rapid expansion. Net profit has also declined 6.7% per year over the past 5 years, and earnings fell 25.7% over the last year, while return on equity is currently a modest 10% and forecast to reach 13.4%. Those numbers mean the market is paying up relative to both the sector average P/E and the fair ratio, even though historical profit trends have been under pressure.
Explore the SWS fair ratio for Chervon Holdings.
Result: Price-to-Earnings of 15x (OVERVALUED)
Still, earnings pressure over the past year and the premium 15x P/E leave Chervon Holdings exposed if profit growth or sentiment on consumer durables softens.
Find out about the key risks to this Chervon Holdings narrative.
Another View on Chervon Holdings Using Cash Flows
The P/E story paints Chervon Holdings as expensive, yet the SWS DCF model goes even further and points to HK$25.2 trading above an estimated future cash flow value of HK$9.7. That is a wide gap. Is this a warning that expectations have run well ahead of fundamentals?
Look into how the SWS DCF model arrives at its fair value.
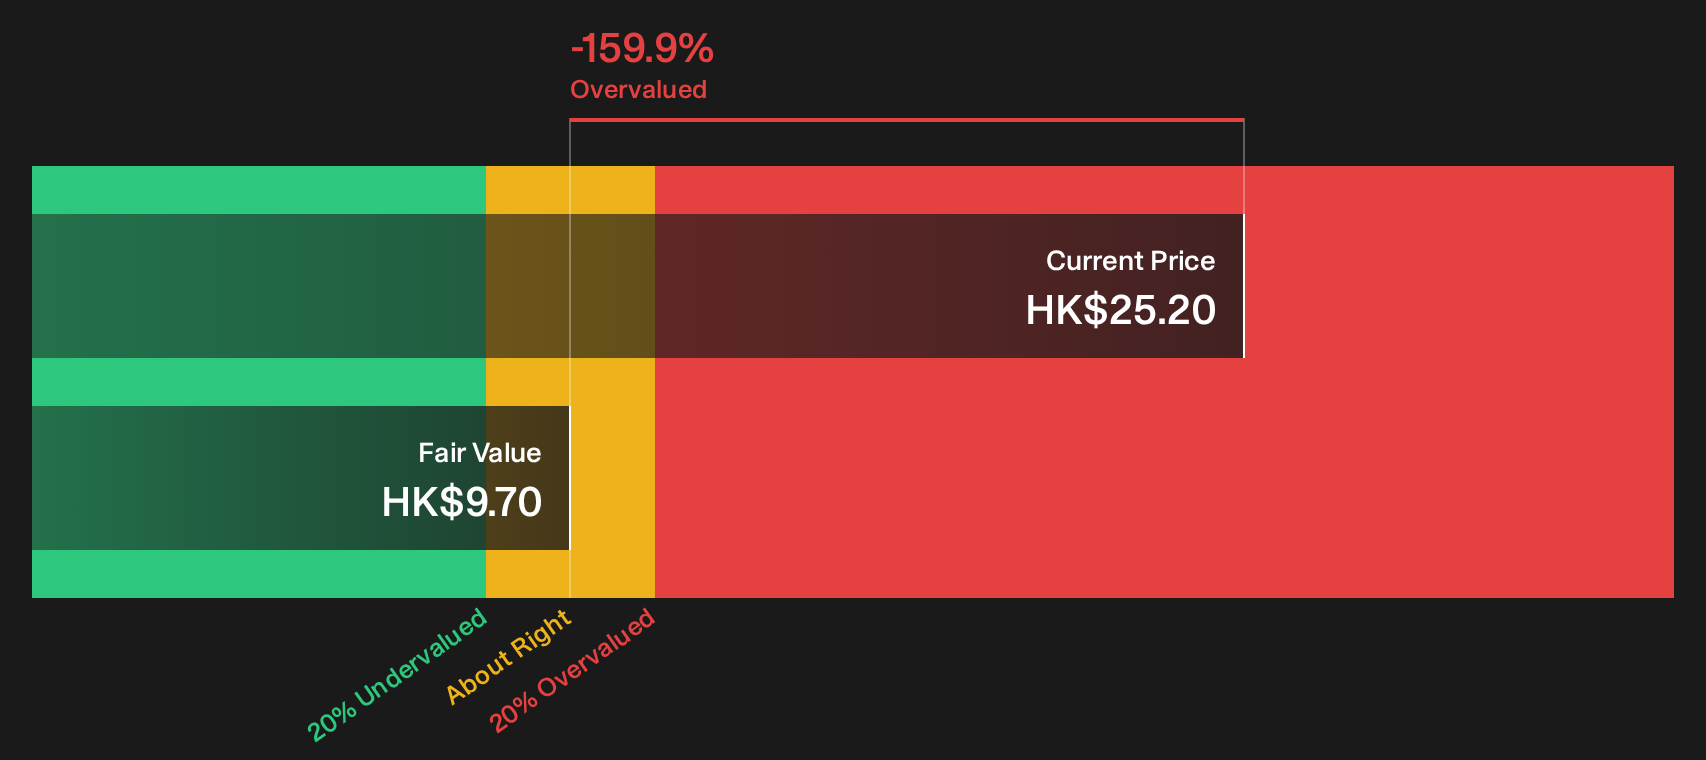
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Chervon Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 183 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment on Chervon Holdings looking divided, you can move quickly by weighing the risks against the positives and forming your own stance using the 1 key reward.
Looking for more Chervon Holdings style investment ideas?
If you stop at Chervon Holdings, you risk missing other opportunities that fit your approach. Put a little time into sourcing fresh ideas and give yourself more options.
- Spot potential value early by scanning the 613 high quality undiscovered gems that pair solid fundamentals with quieter market attention.
- Strengthen your downside protection by reviewing the 227 resilient stocks with low risk scores that focus on resilience and more measured risk scores.
- Zero in on financial robustness by filtering for the list of solid balance sheet and fundamentals (199 results) that line up with disciplined capital structures.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com