


Is Nokia Oyj (HLSE:NOKIA) Undervalued Following Its Expanded Microsoft AI Platform Tie Up?
Nokia Oyj (HLSE:NOKIA) just extended its collaboration with Microsoft to build a shared data platform for telecom operators, aiming to speed up AI driven automation, operational assistants and network level decision making.
That partnership news comes during a period of strong momentum for Nokia Oyj. The share price is at €9.362, with a 1-day share price return of 1.21% and a 7-day share price return of 8.99%, even though the 90-day share price return is down 21.98% after a series of product, client and defense collaborations in September. The year-to-date share price return of 69.48% and a 1-year total shareholder return of 138.31% indicate that recent gains build on a much larger upward move. The 3-year and 5-year total shareholder returns of 186.56% and 119.41% highlight a period in which long-term holders have already seen substantial value created.
Scan Nokia Oyj’s AI and telecom momentum against a hand picked group of 88 AI infrastructure stocks that are also building the data and network backbone for the next wave of automation.
After such a sharp swing in Nokia Oyj’s share price, some investors will lean into the AI and defense story now while others wait for a pullback. So what does the current valuation actually reflect?
Most Popular Narrative: 38% Undervalued
Nokia Oyj’s most followed valuation storyline pegs fair value at €15.16 per share, well above the latest close at €9.36. This frames the recent rally as only part of the move implied by that narrative.
Nokia delivered a strong second quarter, reporting revenue of €4.815 billion and earnings per share of €0.07, supported by growing demand for AI and cloud-related solutions. The company is also expanding its presence in the defense sector through AI-powered tools for 5G networks, creating additional opportunities to diversify revenue and strengthen long-term growth prospects.
See why 8 investors see Nokia Oyj as 38% undervalued.
According to TheTurntTomato, this thesis leans heavily on Nokia Oyj’s push into AI linked networking and 5G based defense tools, as well as a balance sheet backed by about €2.78b in cash that can support further investment when peers may have less room to spend.
That view also sits alongside Simply Wall St’s own DCF output, which currently puts a future cash flow value estimate at €13 per share, compared with the market price of €9.36. This reinforces the idea that recent gains have not closed the gap implied by these models.
Result: Fair Value of €15.16 (UNDERVALUED)
Still, Nokia Oyj’s AI and defense story depends on sustained demand for telecom infrastructure and on successful execution of its heavy investment program without eroding margins.
Find out about the key risks to this Nokia Oyj narrative.
Another View: Nokia Oyj Through Earnings Multiples
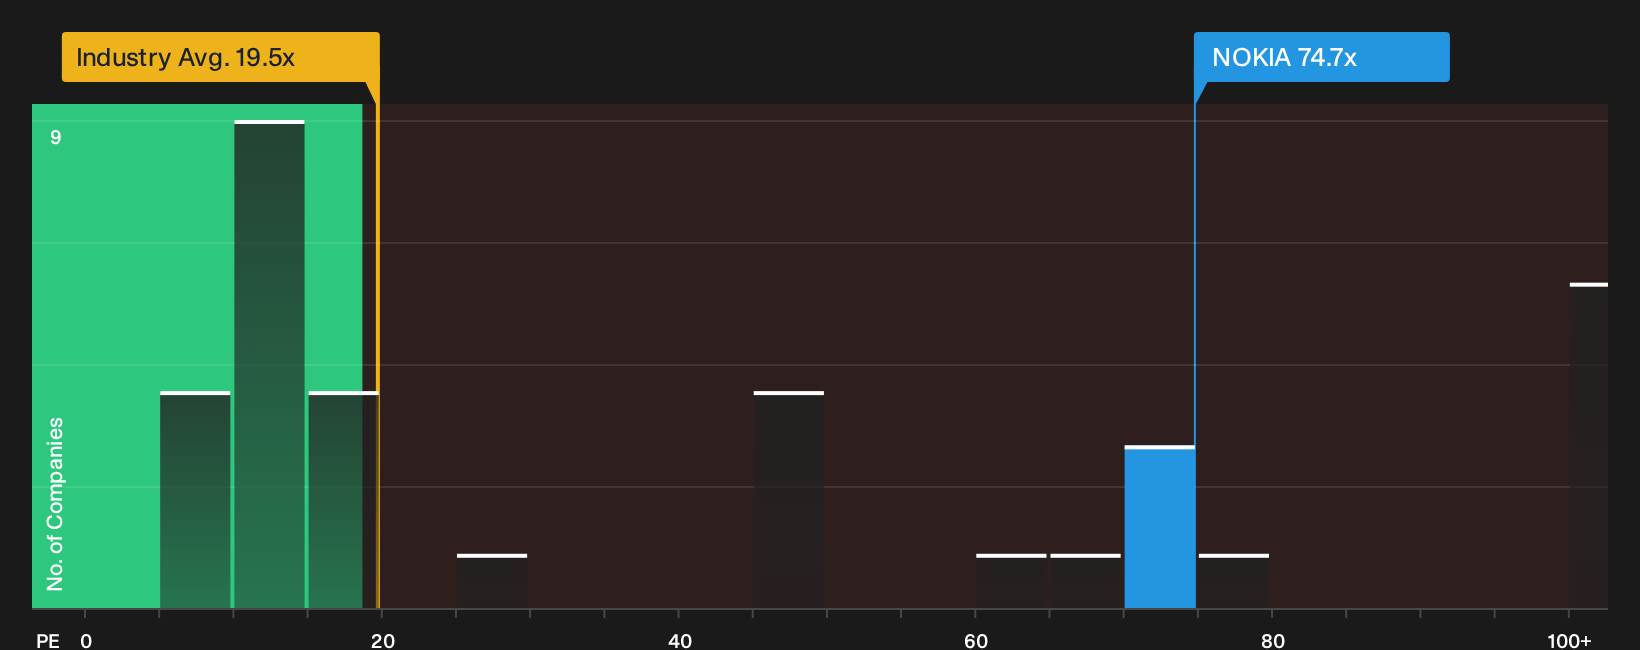
The story looks very different once Nokia Oyj is viewed through its P/E ratio. At about 74.7x earnings, the stock trades well above the European communications sector on 19.5x and ahead of peers on 37.5x, while the fair ratio sits lower at 51.2x.
That gap suggests investors are already paying a premium for future profit growth, which raises the risk that any disappointment on earnings could hit the share price harder than for cheaper rivals. The question is whether you think Nokia Oyj has done enough to justify that kind of head start.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Nokia Oyj’s AI push and rich valuation can spark either excitement or caution, so move quickly, review the underlying numbers yourself, and weigh both the 2 key rewards and 3 important warning signs.
Looking for more ideas beyond Nokia Oyj?
If Nokia Oyj has sharpened your focus on where capital can work harder, do not stop here. The wider market still holds plenty of opportunities.
- Target resilient compounding by reviewing a 159 dividend fortresses that can help anchor your portfolio with income focused ideas.
- Hunt for mispriced opportunities by scanning a 613 high quality undiscovered gems that many investors may not be watching yet.
- Prioritise capital preservation by filtering for a 227 resilient stocks with low risk scores that emphasises steadier balance sheets and lower volatility profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com