


Is Telix Pharmaceuticals (ASX:TLX) Undervalued After Its ITM Merger Move?
Telix Pharmaceuticals (ASX:TLX) has moved to lead a merger with ITM Isotope Technologies Munich SE, outlining plans for a combined radiopharmaceutical group that spans isotope production, manufacturing and commercial distribution.
Despite the merger announcement knocking the share price down by about 11.7% on the day to A$15.76, Telix Pharmaceuticals still carries a 38.7% year to date share price gain. Long term holders have seen total shareholder returns of 167.1% over five years, hinting that recent weakness contrasts with a much stronger multi year record.
Position your Telix Pharmaceuticals view alongside a curated group of radiopharma and biotech peers by scanning our 16 high quality undiscovered gems that are still flying under most investors' radar.The merger sell off has reset expectations around Telix Pharmaceuticals at the same time as its pipeline and Pixclara approval expand the story. Does that combination still leave more upside for new buyers than downside risk now?
Most Popular Narrative: 33% Undervalued
Against the last close at A$15.76, the most followed narrative pegs Telix Pharmaceuticals at a fair value of A$23.36. This frames the recent merger pullback against a higher long run earnings and cash flow outlook that uses a 7.25% discount rate.
Vertical integration in radiopharmaceutical manufacturing and last mile distribution through RLS, ARTMS, Iso Therapeutics and other TMS sites, including planned cyclotron deployment, which can reduce reliance on third parties and over time may support gross margins and supply reliability, both key inputs to sustainable earnings.
See why 21 investors see Telix Pharmaceuticals as 33% undervalued.
Result: Fair Value of A$23.36 (UNDERVALUED)
Still, the story for Telix Pharmaceuticals can shift quickly if PSMA imaging pricing comes under more pressure, or if the SEC subpoena process drags on.
Find out about the key risks to this Telix Pharmaceuticals narrative.
Another View: Telix Pharmaceuticals Looks Expensive On Earnings
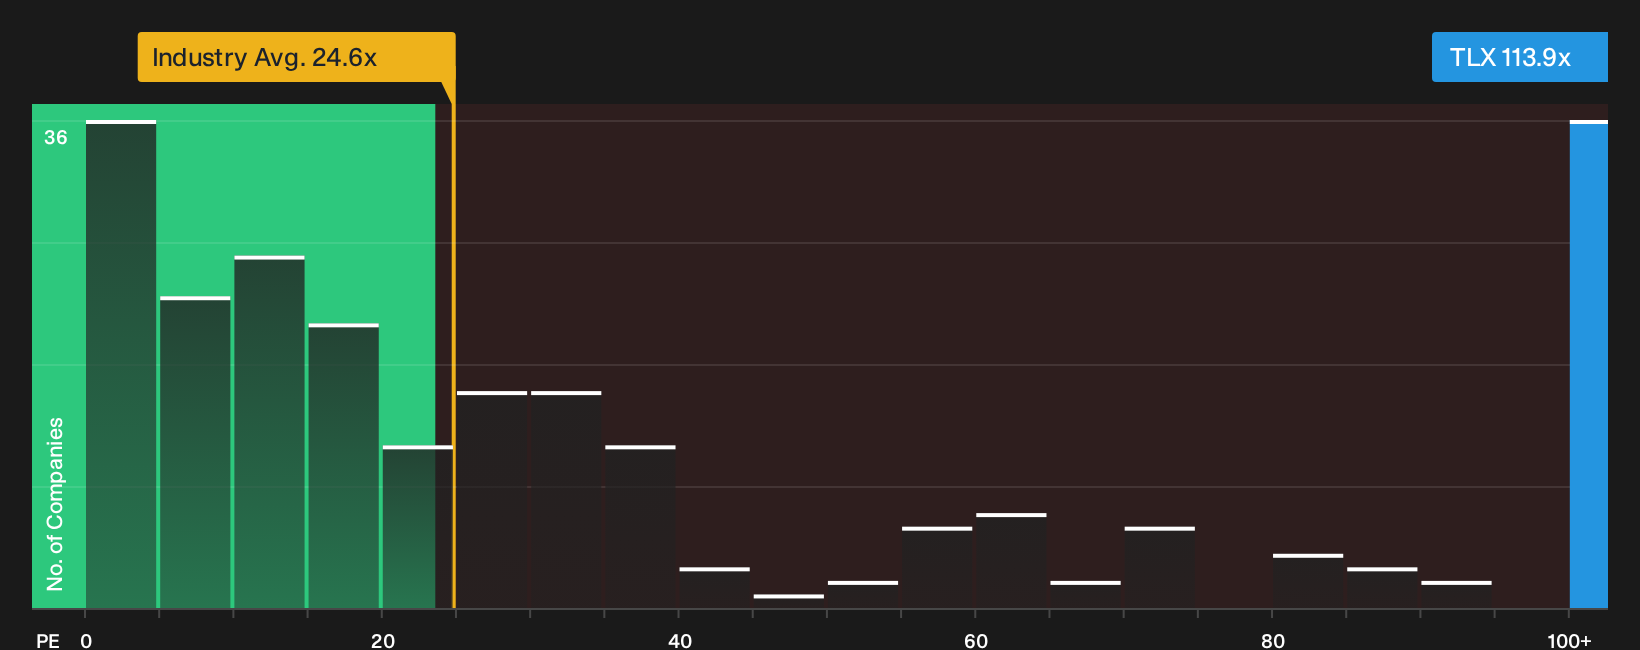
Where the fair value narrative leans on long range cash flows, the current share price tells a different story when looking at Telix Pharmaceuticals through its P/E ratio. At about 113.9x earnings, the stock trades well above both the peer average of 30.4x and the global Biotechs sector on 24.6x.
The fair ratio for Telix Pharmaceuticals is estimated at 51x. That is less than half of where the shares currently change hands and it points to meaningful valuation risk if sentiment cools or forecasts are revised. For an investor weighing fresh capital, the key consideration is whether the growth story is strong enough to justify paying so far ahead of that fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in Telix Pharmaceuticals sentiment can be a strength if you use them quickly and test the numbers yourself rather than following the crowd. To see how the risk and reward signals line up for your own thesis, start with 3 key rewards and 2 important warning signs.
Looking for more Telix Pharmaceuticals style investment ideas?
If Telix Pharmaceuticals has sharpened your thinking, do not stop here. Fresh opportunities rarely sit still and the next move often matters most.
- Target potential value upside by scanning companies on our 5 high quality undervalued stocks where quality fundamentals meet lower implied expectations.
- Prioritise staying power by reviewing the list of solid balance sheet and fundamentals (12 results) so you can focus on businesses with stronger financial footing.
- Reduce portfolio stress by checking out the 7 resilient stocks with low risk scores and see which stocks line up with a more cautious playbook.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com