


Itoham Yonekyu Holdings (TSE:2296) On Index Exit And A Valuation Question
Itoham Yonekyu Holdings (TSE:2296) has just been removed from the FTSE All-World Index (USD). This change can influence index fund flows and prompt investors to reassess how they view the stock.
The latest move comes after a mixed stretch for Itoham Yonekyu Holdings, with the share price down 12.41% year to date but recording a 7.22% 90 day share price return. The 3 year total shareholder return of 36.81% and 5 year total shareholder return of 58.05% indicate momentum that has been built over a longer horizon.
Spot 17 high quality undervalued stocks that, like Itoham Yonekyu Holdings after its index removal, may be slipping off the radar just as their long term return profile begins to matter most.Itoham Yonekyu Holdings has already delivered solid multi year gains, yet the recent index exit and weaker 1 year return have reset expectations. Is most of the payoff now reflected in the share price, or is there still clear upside?
Preferred P/E of 14.1x for Itoham Yonekyu Holdings: Is it justified?
On a simple earnings yardstick, Itoham Yonekyu Holdings trades on a P/E of 14.1x, which points to a cheaper tag than many direct peers even after the recent share price pullback from its index removal.
The P/E ratio compares the current share price with earnings per share and gives a quick read on how much investors are paying for each unit of profit. For a mature food producer like Itoham Yonekyu Holdings, where rapid expansion is not the central story, P/E often carries more weight than growth style metrics because cash generation and earnings resilience matter more than headline revenue pace.
Here, the picture leans toward value support. Management delivered earnings growth of 21% over the past year, ahead of the 10.2% for the broader JP Food industry, and profits are described as high quality with improving net profit margins at 1.9% compared with 1.6% a year earlier. Yet the stock changes hands at 14.1x earnings, below both the Food industry average of 16.8x and the peer average multiple of 26.5x, which indicates the market is assigning a lower earnings premium despite that recent profit improvement. The estimated fair P/E of 16.7x is also higher than the current multiple, which indicates investors may choose to re-rate the valuation if confidence in those earnings solidifies.
Explore the SWS fair ratio for Itoham Yonekyu Holdings.
Result: Price-to-earnings of 14.1x (UNDERVALUED).
Still, Itoham Yonekyu Holdings faces pressure if processed meat demand stalls or if any margin gains fade in a tougher pricing backdrop for food producers.
Find out about the key risks to this Itoham Yonekyu Holdings narrative.
Another view on Itoham Yonekyu Holdings valuation
The SWS DCF model tells a different story. On this view, Itoham Yonekyu Holdings at ¥4,975 sits slightly above an estimated future cash flow value of ¥4,925.48, which points to a mild premium rather than a bargain. If cash generation simply tracks those forecasts, how much margin of safety do you really have?
Look into how the SWS DCF model arrives at its fair value.
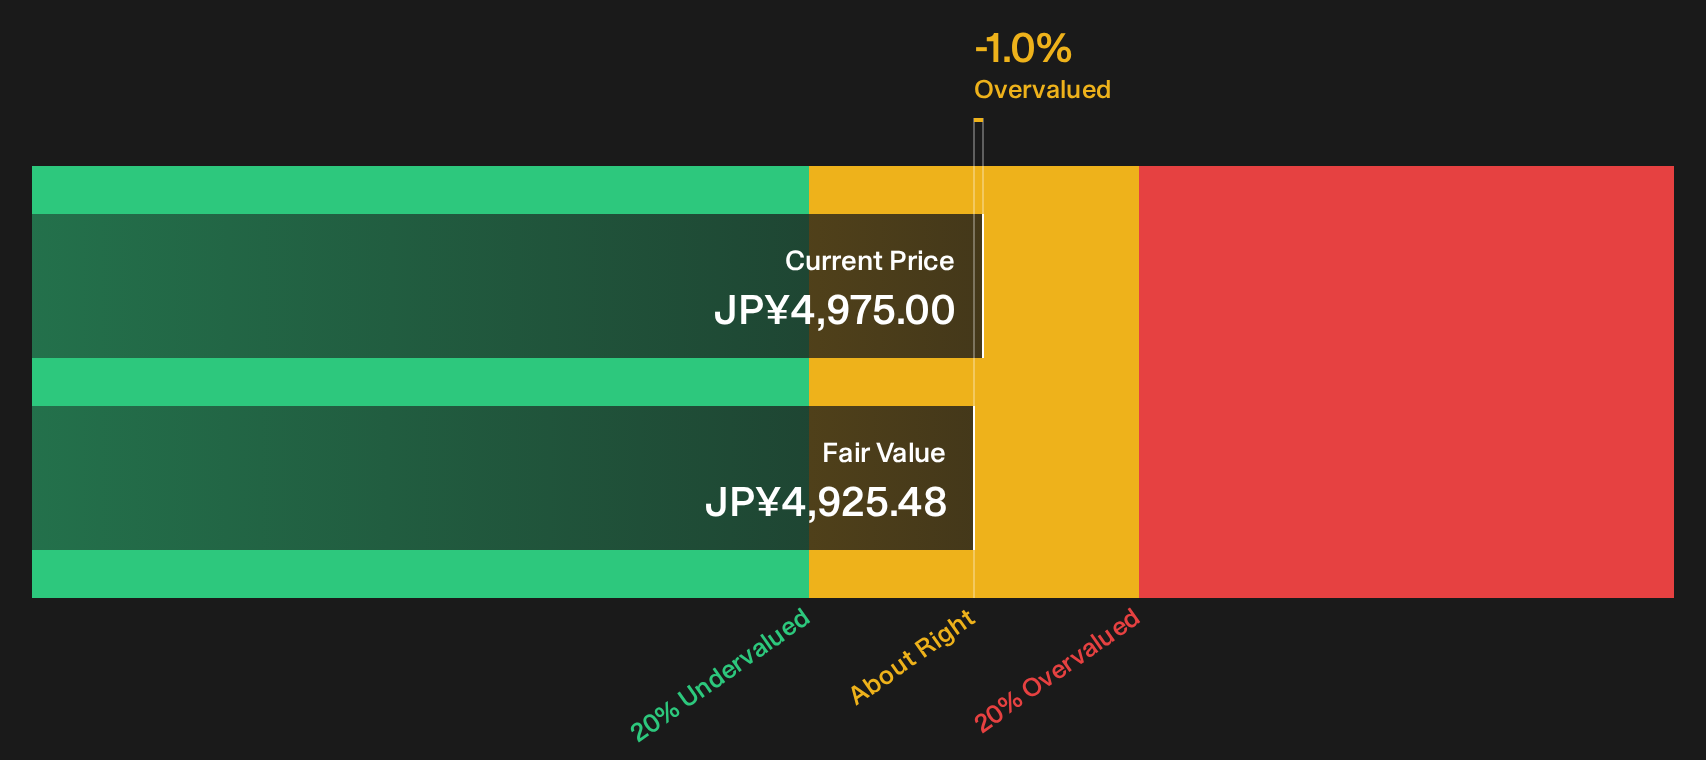
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Itoham Yonekyu Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Itoham Yonekyu Holdings can feel confusing, so it helps to inspect the data and form a view before sentiment shifts again. To weigh up both the potential upsides and the areas of concern in one place, review the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Itoham Yonekyu Holdings?
If Itoham Yonekyu Holdings has sharpened your focus on valuation and quality, consider expanding your options by lining up a few fresh watchlist candidates today.
- Target stronger cash generation potential and balance sheet resilience by reviewing the list of solid balance sheet and fundamentals (21 results) that could handle tougher conditions without forced capital raises.
- Look for potential value gaps in the market by scanning the 17 high quality undervalued stocks that combine supportive fundamentals with pricing that has not yet adjusted.
- Identify income ideas by shortlisting the 14 dividend fortresses that pair higher yields with underlying financial strength instead of stretched payout ratios.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com