


Encompass Health (EHC) Opens Pennsylvania Hospital As Expansion Keeps Undervaluation In Focus
Encompass Health (EHC) just opened a new 50 bed inpatient rehabilitation hospital in Lower Providence Township, Pennsylvania, giving the group more physical capacity to deliver specialized rehab services in the region.
For investors watching Encompass Health, the story around this new Pennsylvania facility sits against a backdrop of steady share price momentum over recent months. The 90 day share price return is 21.87% and the year to date share price gain is 14.46%. This comes even though the 1 year total shareholder return has slipped 2.71%. Longer term total shareholder returns over 3 and 5 years, at 77.64% and 107.84% respectively, point to a much stronger multi year payoff profile.
See how Encompass Health compares with other hospital and healthcare providers by reviewing our hand picked list of list of solid balance sheet and fundamentals (23 results)
The recent run in Encompass Health has been strong, yet the current price still sits below some estimated value markers. Has the bulk of the upside already played out, or is there meaningful room left on the table as capacity expands?
Most Popular Narrative: 18% Undervalued
On the most followed view of Encompass Health, the current $121.75 share price sits at a discount to an estimated fair value around $148.17. That narrative is anchored on capacity growth, discharge trends and a 7.24% discount rate.
The surge in the 65 plus population and persistent undersupply of inpatient rehabilitation beds are driving high and still unmet demand for Encompass Health's core services. Ongoing hospital openings and bed expansions position the company to capture significant incremental patient volume, supporting higher revenue growth for years to come.
See why 6 investors see Encompass Health as 18% undervalued.
Result: Fair Value of $148.17 (UNDERVALUED)
Still, the Encompass Health story can change quickly if labor shortages drive sustained wage pressure or if heavier use of debt for expansion strains flexibility.
Find out about the key risks to this Encompass Health narrative.
Another View on Encompass Health Valuation
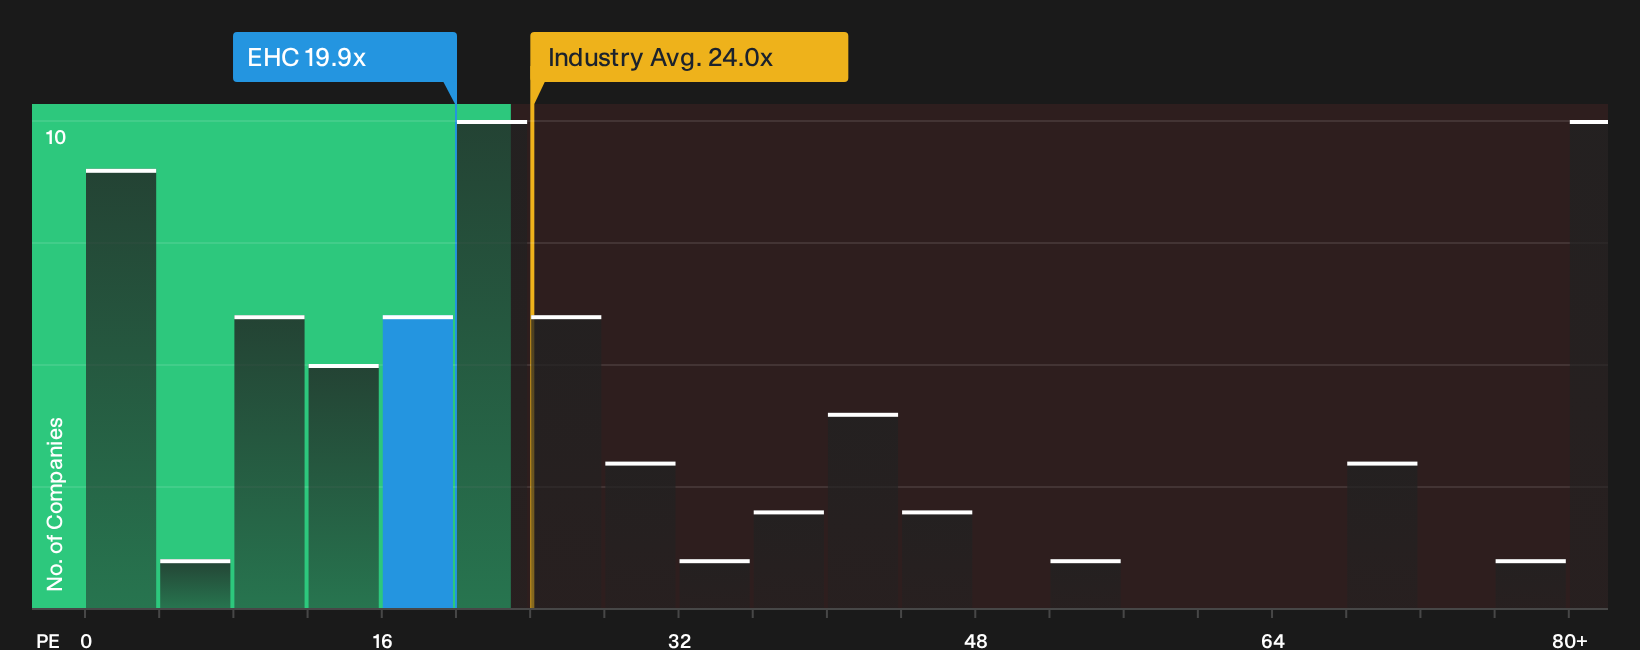
There is a different read on Encompass Health when you focus on the current P/E. The stock trades around 19.9x earnings, compared with 16.9x for direct peers and a fair ratio estimate of 25.5x. That combination of a premium to peers but a discount to the fair ratio raises a straightforward question: Is the market overpaying relative to competitors, or underpaying if the fair ratio is correct?
For a closer look at how this earnings multiple compares with what the numbers imply, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Encompass Health's valuation and risk reward profile can create noise, so move quickly, review the underlying data, and weigh both sides of the argument by checking the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Encompass Health?
If Encompass Health has you thinking harder about where to put fresh capital, do not stop here. Broaden your watchlist with focused stock ideas built from clear, data driven filters that can help you spot strong opportunities before they feel crowded.
- Target potential mispricings by scanning the market for companies that score well on quality checks yet trade below estimated value through the 35 high quality undervalued stocks.
- Build a steadier income stream by hunting for robust payout candidates screened as 7 dividend fortresses.
- Dial down portfolio stress by concentrating on resilience and balance sheet strength with our 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com