


Marathon Petroleum (MPC) Gains On Tight Fuel Supplies Following A Fair Value Debate
Recent commentary on tighter diesel and jet fuel supplies, coupled with refinery capacity cuts on the U.S. West Coast, has pushed Marathon Petroleum (MPC) into focus for investors watching refining profitability and cash generation.
Recent price action has been strong, with Marathon Petroleum’s share price up 17.79% over the past 30 days and 70.97% over 90 days, contributing to a 157.29% year to date share price return and a 130.70% total shareholder return over the past year. This indicates sustained momentum rather than a short-lived spike.
Scan other refiners riding similar margin tailwinds by reviewing our hand picked list of list of solid balance sheet and fundamentals (23 results) alongside the recent strength of Marathon Petroleum.
Marathon Petroleum now trades above the average analyst target and yet below some intrinsic value estimates. After this run, where does a reasonable fair value range actually sit for new money and existing holders?
Most Popular Narrative: 31% Overvalued
On Simply Wall St’s most followed narrative, Marathon Petroleum’s fair value of $324.56 sits well below the last close at $424.89. This frames the recent rally as stretching beyond that model’s estimate of future cash flows and earnings power.
Disciplined capital allocation through continued share buybacks, increasing MPLX distributions, and maintenance of an investment-grade balance sheet are set to drive higher earnings per share and sustained shareholder returns, aligning with positive long-term company trends.
See why 61 investors see Marathon Petroleum as 31% overvalued.
Result: Fair Value of $324.56 (OVERVALUED)
Still, the narrative can break if long term demand for gasoline and diesel weakens faster than expected or if stricter climate policies squeeze refining profitability.
Find out about the key risks to this Marathon Petroleum narrative.
Another View on Marathon Petroleum’s Value
The analyst narrative frames Marathon Petroleum as about 31% overvalued, based on a $324.56 fair value. A different lens tells a very different story. The SWS DCF model estimates future cash flows at $507.73 per share, which would put the current $424.89 price in undervalued territory instead.
That is a wide gap between an overvaluation call and a DCF that still points to upside. It raises a simple question for investors weighing Marathon Petroleum today: which set of assumptions about future cash generation feels more realistic to you.
Look into how the SWS DCF model arrives at its fair value.
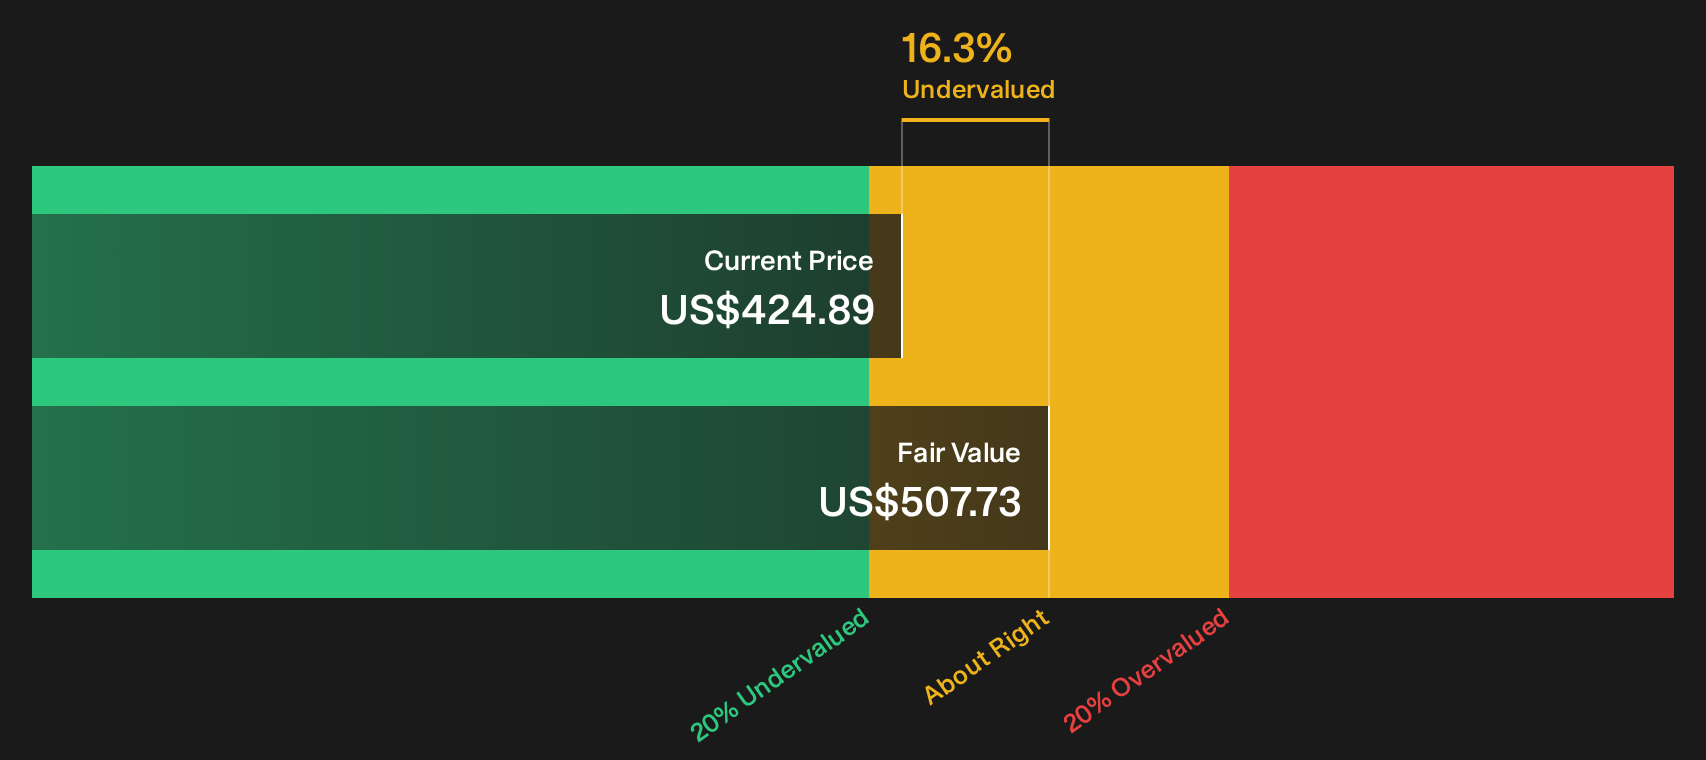
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Marathon Petroleum for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Marathon Petroleum’s value can be useful, not paralysing. Act quickly by reviewing both the upside and the worries in the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Marathon Petroleum?
If the valuation debate around Marathon Petroleum has your attention, broaden your watchlist with a few focused stock ideas built from the Simply Wall St screener tools.
Expand your opportunity set by scanning a 16 high quality undiscovered gems that combine strong fundamentals with less crowded investor attention.
Stack potential income streams by zeroing in on a curated group of 7 dividend fortresses that may suit a yield focused approach.
Dial up resilience in your portfolio by filtering for a 30 resilient stocks with low risk scores that aim to keep downside in check when sentiment shifts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com