


3 AI Infrastructure Stocks Retail Investors Are Watching Right Now
AI is suddenly being talked about as both a miracle tool and a possible “silicon species,” and that mix of excitement and alarm is pulling huge attention toward the picks and shovels that power it. Regulation risk looms, yet the build out of cloud, chips, and data centers keeps drawing fresh capital. This article reviews three stocks from our AI Infrastructure and Enablers screener that appear especially exposed to this moment.
The three stocks that follow are just a small sample of the AI infrastructure theme. The full screen surfaced 139 more large caps whose business descriptions and fundamentals point to equally interesting AI related stories that are not covered here.
If you want to move straight from ideas to your own due diligence, head into the AI Infrastructure and Enablers (Semiconductors, Cloud, and Data Center REITs) screener to identify, filter, and analyze setups across semiconductors, cloud platforms, and data center landlords.
Delta Electronics (TWSE:2308)
Delta Electronics plugs directly into the AI infrastructure theme because its power and thermal gear sits behind the racks that run large language models. Its scale means those data center oriented lines already matter inside a much broader industrial portfolio.
Delta Electronics generates revenue across several groups, led by the Power Supply and Spare Parts Business Group at NT$337,932 million and the Infrastructure Business Group at NT$226,211 million, with Automation and Transportation contributing smaller shares. The stock’s market value sits around NT$4,701,553 million.
"Sustained investment in AI and data center infrastructure by hyperscalers is driving strong demand for Delta's power and cooling solutions, underpinning record revenues and margin expansion in these business lines. This positions Delta to capture ongoing top-line and operating income growth as global digitalization accelerates."
What happens if one unseen pressure on Delta Electronics’ AI focused cooling and power projects tightens just as customers rethink long-term spending?
If that friction point matters to you, read the full narrative for Delta Electronics to see how Delta Electronics could balance AI demand against tightening data center budgets.

ASML Holding (ENXTAM:ASML)
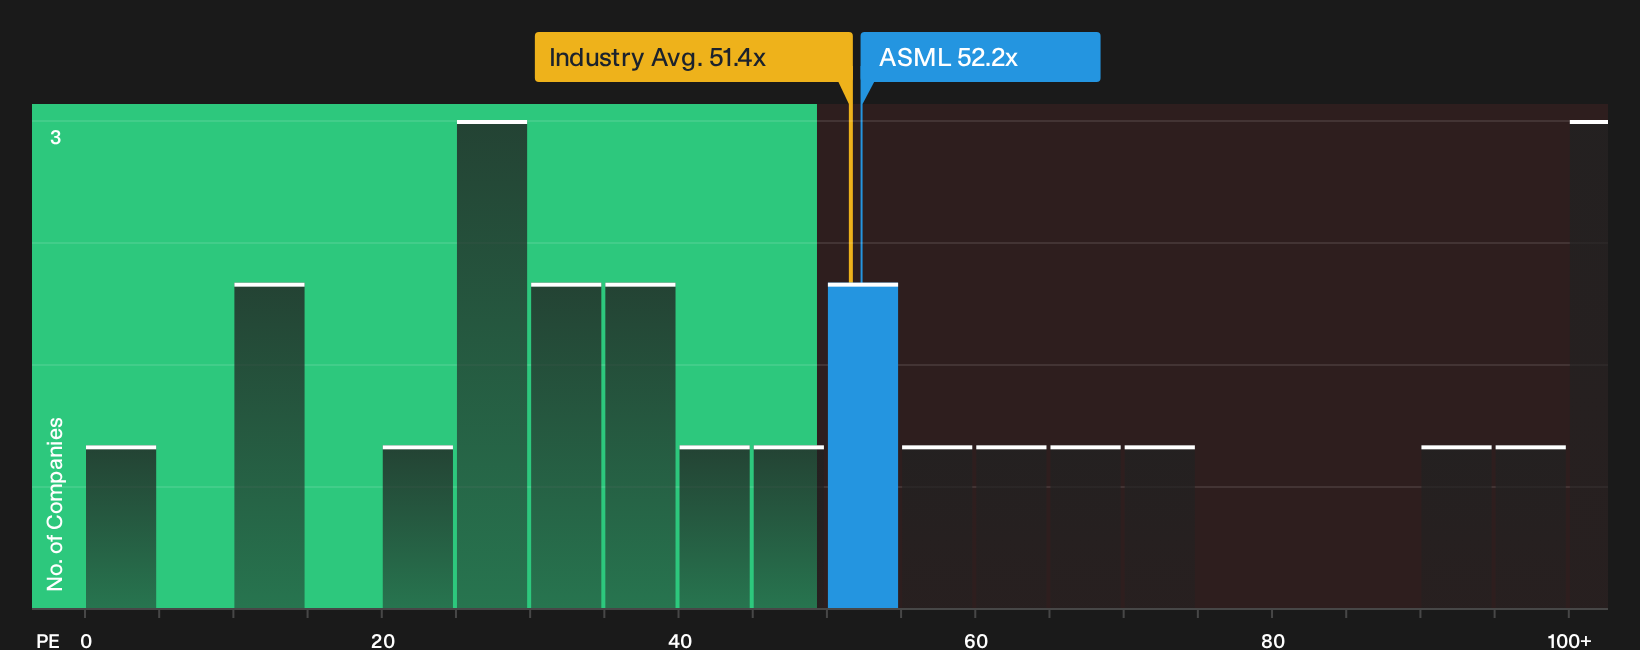
ASML Holding is the purest AI picks-and-shovels play in this screener, since its lithography systems are required to print the advanced chips that power hyperscale data centers. It earns about €35.3b from semiconductor equipment and services on a market value near €555.3b.
"The real risk comes from geopolitics. Export restrictions, especially involving China, have turned ASML into a geopolitical chokepoint."
What happens if one unseen pressure on ASML’s leading-edge tool demand tightens just as chipmakers lock in years of AI capex plans?
That pressure point is where ASML Holding’s story really sharpens, and the full narrative for ASML Holding shows how export risk, AI demand and long term tool economics are colliding.
Infineon Technologies (XTRA:IFX)
Infineon Technologies leans into the AI infrastructure theme through its power, sensor, and security chips that sit inside servers, data centers, and connected hardware, with most revenue coming from Automotive at about €7.5b, Power & Sensor Systems at €5.0b, Green Industrial Power at €1.7b, and Connected Secure Systems at €1.4b on a roughly €72.4b market cap.
Infineon Technologies is already tied closely to AI hardware demand, yet the most interesting part of its story sits inside its manufacturing plans.
"IFX is investing heavily in new production capacity at Dresden: Smart Power Fab (start of construction 2023, invest €5b), an increase FCF to €3.0b is reasonable, and already considered in the “fair value”."
What happens to Infineon Technologies’ AI-linked opportunity set if a single unseen pressure changes how that extra capacity feeds into margins and demand?
When that single pressure starts to bite, the full narrative for Infineon Technologies lays out how Infineon Technologies’ new capacity could reshape AI demand, margins, and long term optionality.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities do not wait. Breakout momentum often gets caught quickly once the crowd notices, and the cleanest entry points start dropping away. Scan these ideas while it matters and get in early.
- Spot potential turnarounds early and track 183 high quality undervalued stocks before renewed momentum pulls valuations higher and the best entry windows disappear.
- Zero in on steady income ideas using the 160 dividend fortresses before yields compress and today’s payouts look generous only in hindsight.
- Follow powerful infrastructure shifts by reviewing the 39 power grid technology and infrastructure stocks while these backbone operators remain under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com