


Progyny (PGNY) Rebounds Over The Past Year, Is The Stock Still Trading At A Discount?
Progyny (PGNY) is in focus after recent trading data showed mixed short-term returns, with the share price roughly flat over the past week but higher over the past month and past 3 months.
With Progyny trading at about US$27.13, the recent 30-day share price return of 5.77% contrasts with a softer 90-day share price move of 1.88%. A 1-year total shareholder return of 22.59% sits against weaker 3 and 5-year total shareholder returns, suggesting near term momentum has improved even as longer term holders have experienced more muted outcomes.
Scan Progyny alongside other health-focused benefits and medical services businesses that have been hand-picked for resilient fundamentals in our list of solid balance sheet and fundamentals (23 results).
Progyny has delivered a quicker rebound in the past year than its longer term track record suggests. After that reset, does the current valuation still offer a favorable risk-reward profile for new buyers, or has most of the potential upside already been realized?
Most Popular Narrative: 20% Undervalued
Progyny is trading at $27.13 against a widely followed fair value estimate of about $33.82. This frames the current setup as modestly discounted rather than stretched, especially given the recent rebound in the share price.
Investment in an integrated women's health platform (including new services such as pelvic floor therapy, leave navigation, and enhanced digital engagement) positions Progyny to cross-sell adjacent products, resulting in higher share of wallet with current clients and additional revenue streams, supporting both topline and margin expansion.
See why 26 investors see Progyny as 20% undervalued.
Result: Fair Value of $33.82 (UNDERVALUED)
Still, the story can change quickly if employer cost cutting slows new benefit adoption, or if rising competition squeezes Progyny’s pricing power and client wins.
Find out about the key risks to this Progyny narrative.
Another View on Progyny’s Valuation
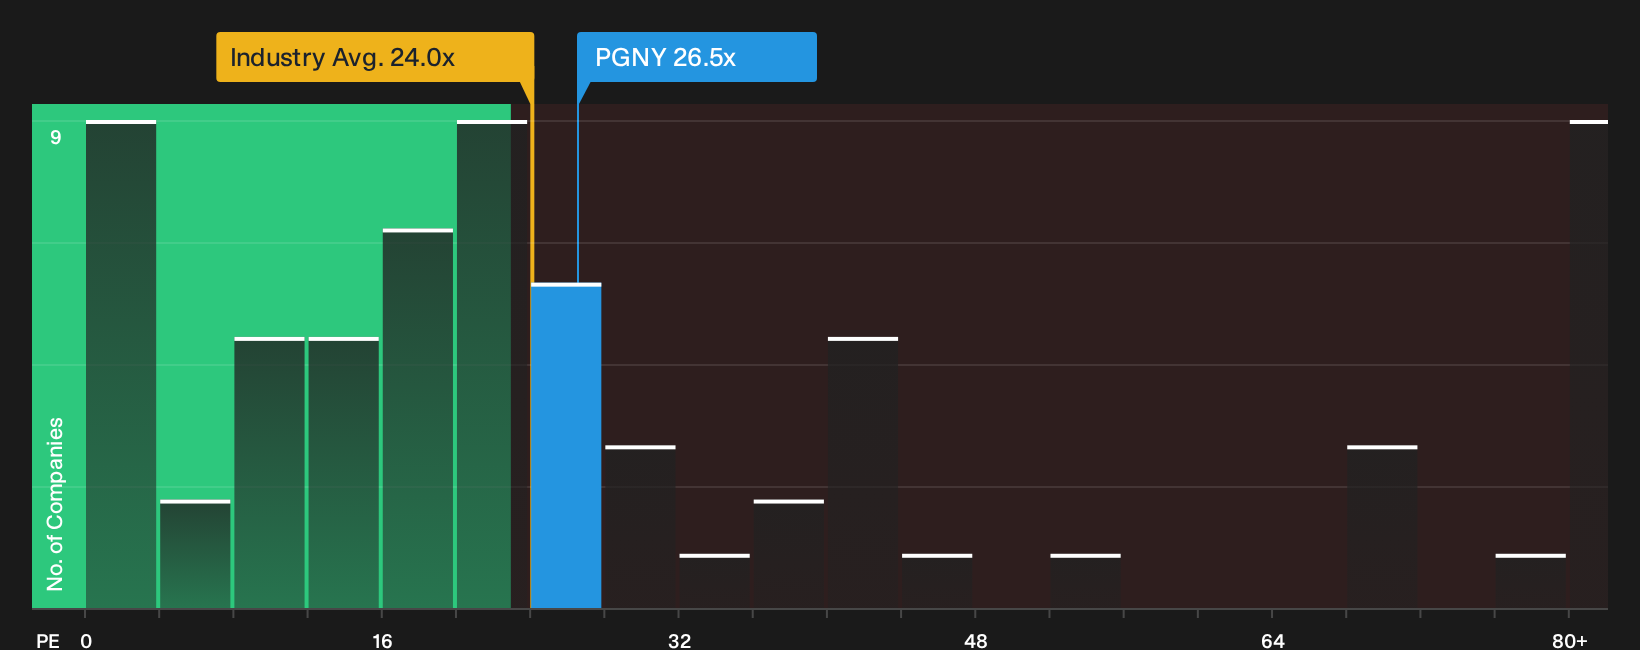
The earlier fair value of $33.82 presents Progyny as modestly undervalued. From a different perspective, the current P/E of 26.5x is higher than the broader US Healthcare sector at 24x, yet below peers at 32.5x and very close to a fair ratio of 27.8x. That combination of a slight premium to the sector, a discount to peers, and proximity to the fair ratio suggests a more balanced picture. The key question is whether this represents a genuine margin of safety or simply a full price for quality.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Progyny can feel confusing. Move quickly, review the underlying metrics for yourself, and pressure test the upside by checking the 4 key rewards.
Looking for more investment ideas beyond Progyny?
If Progyny has your attention, do not stop here. Your next strong opportunity could be sitting in plain sight among other high quality stocks on the Simply Wall St screener.
- Target resilient businesses with healthy finances by scanning the list of solid balance sheet and fundamentals (23 results) that keep earning power and balance sheet strength front and center.
- Hunt for quality at a discount by reviewing the 35 high quality undervalued stocks that filters for companies combining strong fundamentals with prices that still look appealing.
- Build a steadier income stream by checking the 7 dividend fortresses that focuses on higher yielding stocks with an emphasis on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com