


International Consolidated Airlines Group And 2 British Undervalued Stocks To Watch
The Federal Reserve has just lifted interest rates again, which keeps borrowing costs higher for longer and puts pressure on weaker balance sheets. That backdrop often pushes investors toward solid British businesses whose cash flows and debt profiles can handle tougher money markets. This article focuses on a group of financially resilient UK stocks that currently look cheap and highlights three that score especially well on our quality and value screen.
The three stocks covered below are only a starting sample from this high quality, undervalued theme. The full screen surfaces 7 more UK businesses with equally compelling cash flow strength, balance sheets and value signals that are not discussed here.
To go straight to the source and identify your own candidates, analyze the full High Quality Undervalued Stocks list with the High Quality Undervalued Stocks screener.
International Consolidated Airlines Group (LSE:IAG)
International Consolidated Airlines Group brings together British Airways, Iberia, Vueling and Aer Lingus, giving the group the kind of recurring passenger cash flows and balance-sheet scale that fit neatly with a high quality, undervalued recovery theme.
IAG runs a broad aviation group that earns most of its income from passenger airlines, with British Airways at about €17.3b, Iberia €8.1b, Vueling €3.3b, Aer Lingus €2.5b and IAG Loyalty €3.0b, and the stock sits in the large cap bracket at roughly £18.5b.
"The ongoing expansion and modernization of the fleet, with significant CapEx allocated to next-generation, fuel-efficient aircraft and a planned infusion of 50 Boeing 737s at Vueling, positions IAG to structurally reduce fuel and maintenance costs and enhance operational efficiency, directly improving net margins and long-term earnings power."
What happens if one unseen pressure on future demand does not break the way current expectations quietly assume it will.
If that unseen pressure is what really drives the next leg of the story, the full narrative for International Consolidated Airlines Group shows how International Consolidated Airlines Group could still be mispriced by the market.

Foresight Group Holdings (LSE:FSG)
Foresight Group Holdings runs an infrastructure and private equity platform built around renewable-focused real assets. This ties directly into the High Quality Undervalued Stocks theme through cash-generating projects and long-term contracts that support more resilient earnings.
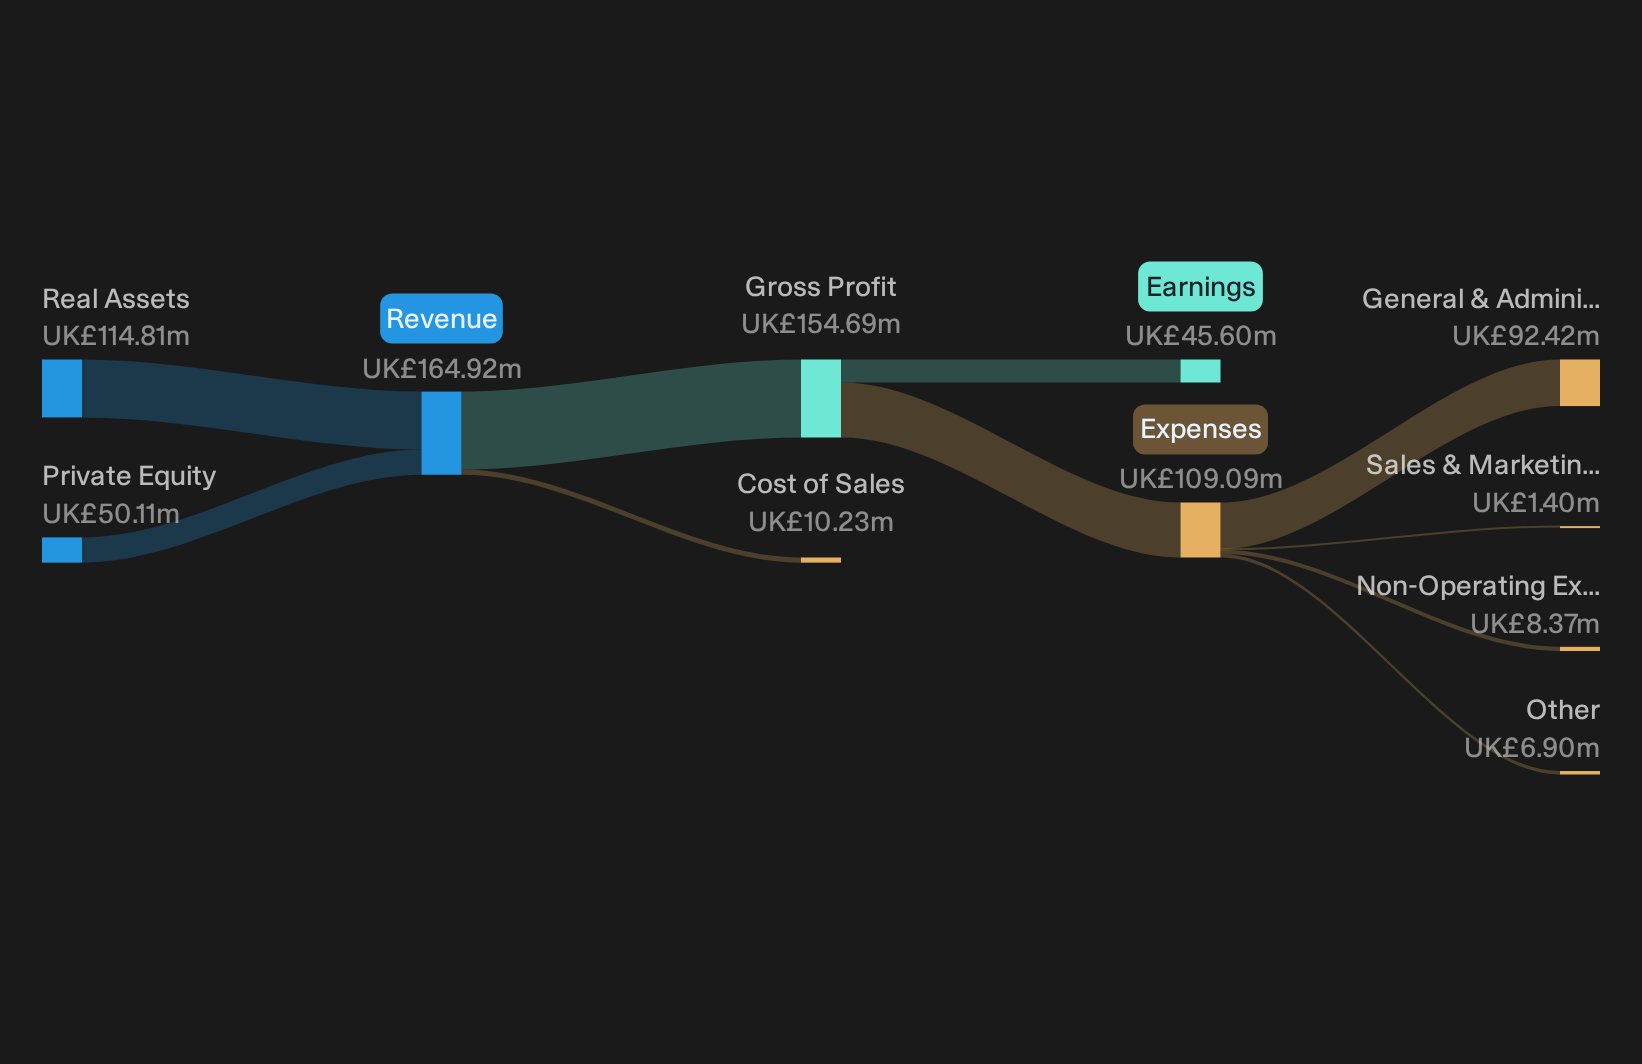
Foresight Group Holdings manages real assets that produce £114.8 million of revenue and private equity operations that add £50.1 million, with activity led by the United Kingdom and supported by Australia and continental Europe. The stock carries a market value of about £488 million.
Foresight Group Holdings gives investors exposure to income-producing renewables and broader private markets in one vehicle. The next piece of the story is how capital allocation choices can turn that platform into a stronger compounding engine.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is set to deliver compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
What happens to that appealing set up if one pressure on future fee growth and margins refuses to move the way management hopes?
If that pressure on fees keeps building, the full narrative for Foresight Group Holdings shows how Foresight Group Holdings could still turn it into accelerating value creation for long term investors.
BAE Systems (LSE:BA.)
BAE Systems is a global defense contractor supplying electronic warfare, precision weapons, combat vehicles and naval programs that align closely with the High Quality Undervalued Stocks theme through long-term, high-margin government contracts. Electronic Systems generates about £7.8b, Air £7.7b, Maritime £6.7b, Platforms & Services £5.3b and Cyber & Intelligence £2.4b, with the group valued at roughly £57.3b.
For investors focused on dependable cash generation and balance sheet strength, BAE Systems offers a different flavour of quality compared with airlines or asset managers, rooted in long-duration defense programs that can support value if current contracts and pipelines hold up.
"The company's order backlog has reportedly increased to £75 billion, with a pipeline of new opportunities partly associated with higher defense spending commitments across NATO, the US, UK, Europe, and Indo-Pacific, providing visibility on contracted revenues over multiple years."
The key consideration is how pressure around future contract execution and capacity expansion ultimately feeds through to margins and cash generation.
If that execution risk is what really moves the story, the full narrative for BAE Systems shows how BAE Systems’ backlog, capacity and cash flows could be decoupling from market expectations.

Seeking Fresh Alternatives Beyond These Picks?
New breakout stories often move before the crowd even notices them. Fresh momentum can be captured quickly and the best entry points can disappear fast, so consider acting promptly if something fits your strategy.
- Spot potential turnaround plays with strong finances before they trend by scanning the 6 high quality undiscovered gems that remain under the radar for now.
- Focus on potential income opportunities by reviewing the 1 dividend fortresses that aim to keep cash returns flowing even while prices swing.
- Explore long term infrastructure and electrification themes by checking the 39 power grid technology and infrastructure stocks that could benefit if grid upgrades continue.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com