


Weichai Power (SEHK:2338) Tests Valuation Following Shaanxi Deal And H Share Dividend
Weichai Power (SEHK:2338) has put two investor focused decisions on the table: a new cash dividend for H shares and a supplemental sales agreement with Shaanxi Automotive. Together, these moves reshape both cash flows and commercial ties.
Weichai Power’s share price has pulled back over the past month, with a 30 day share price return of a 5.15% decline and a 90 day share price return of a 22.68% decline. However, the year to date share price return of 67.02% and a 1 year total shareholder return of 124.67% suggest that momentum has been strong. This fresh dividend plus the Shaanxi Automotive agreement now slot into an already powerful multi year total shareholder return of 237.57% over three years and 133.28% over five years.
Scan how Weichai Power stacks up against other heavy-industry and capital-goods plays by reviewing our curated list of 39 power grid technology and infrastructure stocks in related infrastructure supply chains.
Weichai Power now pairs a fresh cash dividend with a deeper link to Shaanxi Automotive. That points to a solid industrial platform. The real tension is whether the current HK$31.70 price already reflects it.
Preferred P/E of 18x for Weichai Power: Is it justified?
On a P/E of 18x at HK$31.70, Weichai Power trades at a richer earnings multiple than both its peer group and the wider Hong Kong machinery sector.
The P/E ratio compares the current share price with earnings per share and gives a quick sense of how much investors are paying for each unit of profit. For an industrial manufacturer that spans engines, commercial vehicles, logistics and agricultural equipment, earnings power often matters more than headline revenue growth, so this lens carries weight.
Here, the market is paying more for Weichai Power’s profits than for similar machinery stocks. The stock is described as expensive versus the peer average P/E of 11.9x and also expensive relative to the Hong Kong machinery industry multiple of 12.8x. This suggests expectations for the business are materially higher than for rivals and could leave less room for disappointment if growth or margins soften.
2338 is also assessed as good value when that 18x P/E is set against an estimated fair P/E of 19.3x, which is a level the market could move towards if sentiment stays aligned with those assumptions.
Explore the SWS fair ratio for Weichai Power.
Result: Price-to-earnings of 18x (OVERVALUED)
Still, the recent 30 day and 90 day share price declines, together with richer P/E levels than sector peers, could quickly challenge confidence in the Weichai Power rerating.
Find out about the key risks to this Weichai Power narrative.
Another view on Weichai Power’s valuation
While the 18x P/E at HK$31.70 looks heavy against peers, the SWS DCF model suggests a different picture. It values Weichai Power at HK$87.95 per share, which represents a very wide gap to the market price and indicates a different risk and reward balance for holders.
Look into how the SWS DCF model arrives at its fair value.
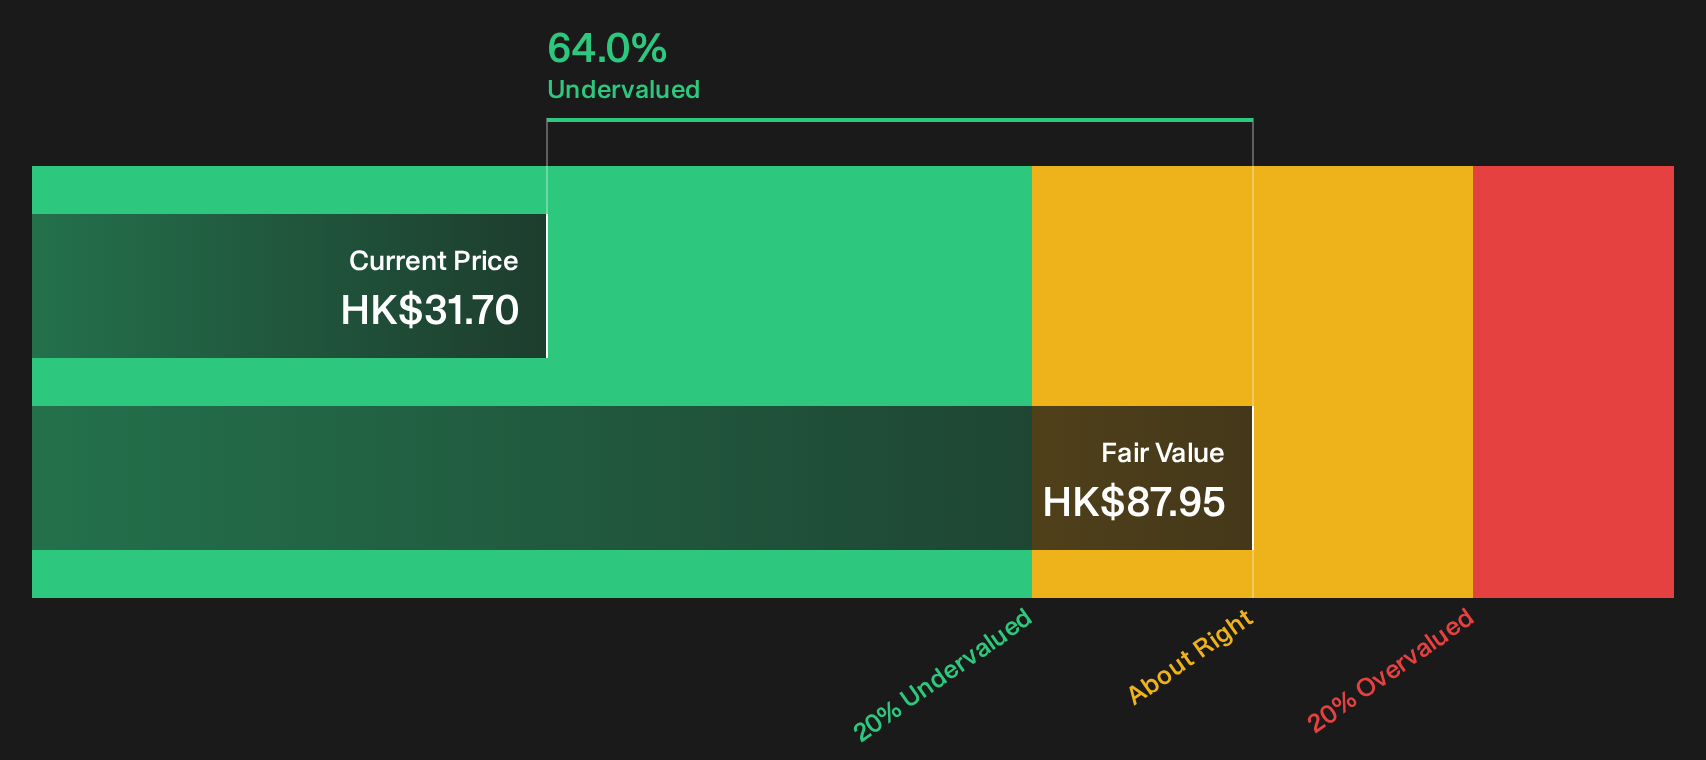
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Weichai Power for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Reading through the mixed signals on Weichai Power and wondering what to make of it all yourself? Move quickly, review the full balance of risks and upsides, and ground your own view in the data by checking the 4 key rewards and 1 important warning sign.
Looking for more ideas beyond Weichai Power?
If Weichai Power has sharpened your interest, do not stop here. Put that curiosity to work and line up a few more targets worth your attention.
- Target resilient bargains by scanning a curated mix of quality companies trading below their assessed value through the 179 high quality undervalued stocks.
- Strengthen portfolio stability by filtering for companies with healthier finances using the list of solid balance sheet and fundamentals (198 results).
- Get ahead of the crowd by narrowing in on underfollowed opportunities with strong fundamentals via the 614 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com