


Meitu (SEHK:1357) Could Be 55% Undervalued As MVLAND 2.0 Sharpens Its AI Video Pitch
Meitu (SEHK:1357) has pushed its AI ambitions further with MVLAND Version 2.0, introducing a new Studio Mode that integrates music analysis, storytelling tools, and detailed shot-level video controls for creators.
The MVLAND upgrade comes at a tricky moment for Meitu shareholders. The stock closed at HK$4.035 after a 1-day share price gain of 5.77%. However, the 30-day share price return is down 8.92% and the year-to-date share price return has fallen 45.69%, while the 5-year total shareholder return of 167.16% still reflects a much stronger long-run payoff profile.
Scan beyond Meitu and see how other AI-focused creators' tools are priced and performing with the hand-picked 147 AI small caps list.
So is Meitu’s sharp single day rebound a hint that the AI video push is finally getting more credit, or just a brief sentiment swing on a still depressed share price chart?
Most Popular Narrative: 55% Undervalued
Meitu’s most followed narrative puts fair value at HK$8.97, well above the last close at HK$4.04. This frames the latest AI announcement against a much wider valuation gap.
Successful integration of advanced AI features (AI Wardrobe, AI Flash, and RoboNeo) has significantly improved user engagement and willingness to pay, demonstrated by a 45.2% year-on-year revenue growth in the core Photo, Video, and Design (PVD) segment and a rising subscription rate, pointing to higher future ARPU and improved gross margins.
See why 6 investors see Meitu as 55% undervalued.
Result: Fair Value of HK$8.97 (UNDERVALUED)
Still, the Meitu story can break if competition in AI imaging ramps up faster than expected or if overseas users prove harder to convert into profitable subscribers.
Find out about the key risks to this Meitu narrative.
Another View On Meitu’s Valuation
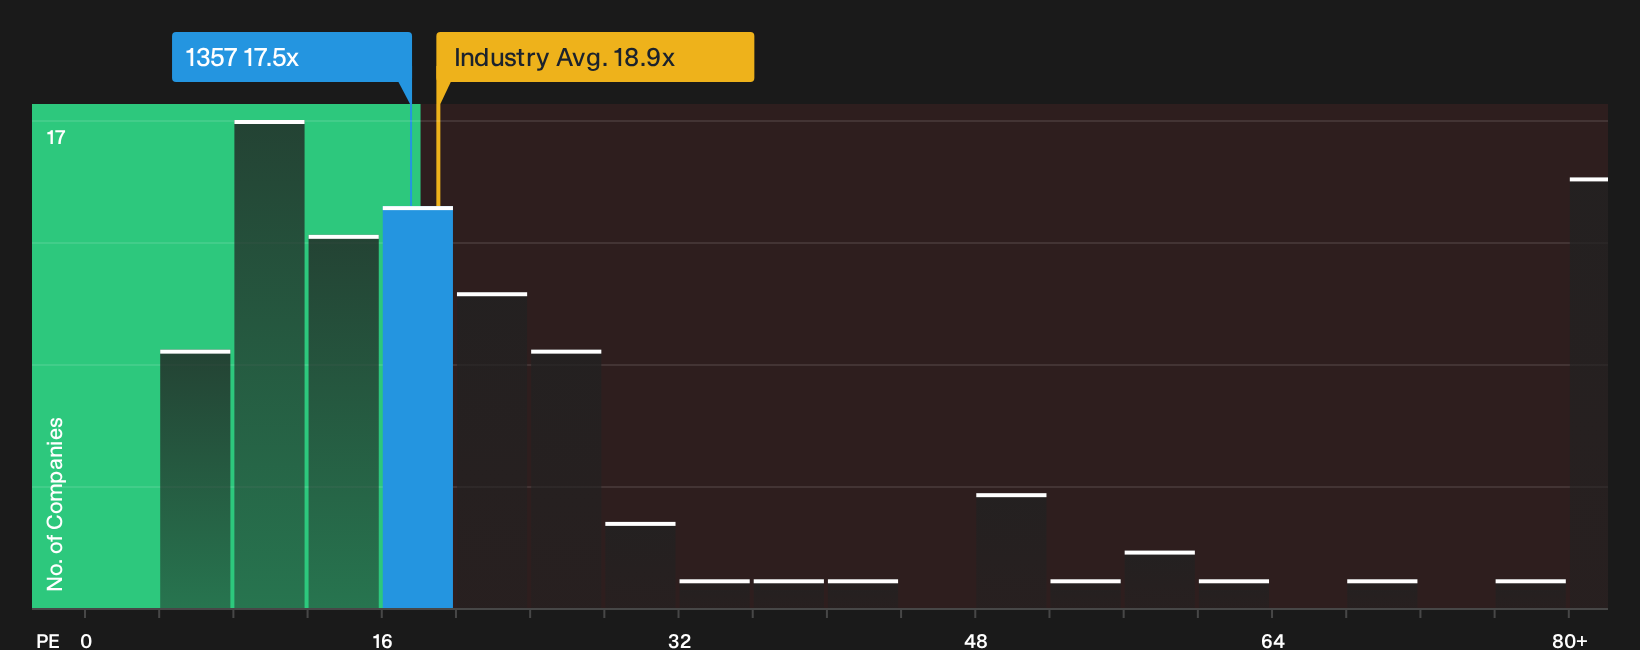
The story looks different once price is compared to earnings. Meitu trades on a P/E of 17.5x, above a fair ratio of 16.2x and richer than the peer average of 13.2x, even though it sits slightly below the Asian Interactive Media and Services group at 18.9x. Is that extra multiple a margin of safety or a margin of error?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Meitu’s value story are clear, so move fast, check the data points for yourself and weigh both the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Meitu?
Do not stop with Meitu. Use the Simply Wall St screener to quickly surface fresh ideas that fit the way you like to build a portfolio.
- Target potential upside with a focused set of undervalued opportunities by running the 179 high quality undervalued stocks.
- Prioritise resilience and sleep-better-at-night positions using the 226 resilient stocks with low risk scores.
- Hunt for under-the-radar opportunities that the crowd may have missed by checking the 614 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com