


Did Updated Survival Data Just Shift Summit Therapeutics (SMMT) Investment Narrative?
- Summit Therapeutics reported updated Phase III HARMONi data for ivonescimab plus chemotherapy in EGFR mutated non squamous NSCLC, with overall survival and safety results remaining consistent and favorable across Asian and western patients, and forming the core of its ongoing U.S. BLA review.
- The repeated overall survival hazard ratio of 0.76 across the global population and western subgroup highlights how ivonescimab’s effect looks regionally aligned. This matters for Summit Therapeutics as it plans a multi region commercial push if the drug is eventually approved.
- We will now look at how these globally consistent overall survival data for ivonescimab could reshape Summit Therapeutics' investment narrative.
Summit Therapeutics Investment Narrative Recap
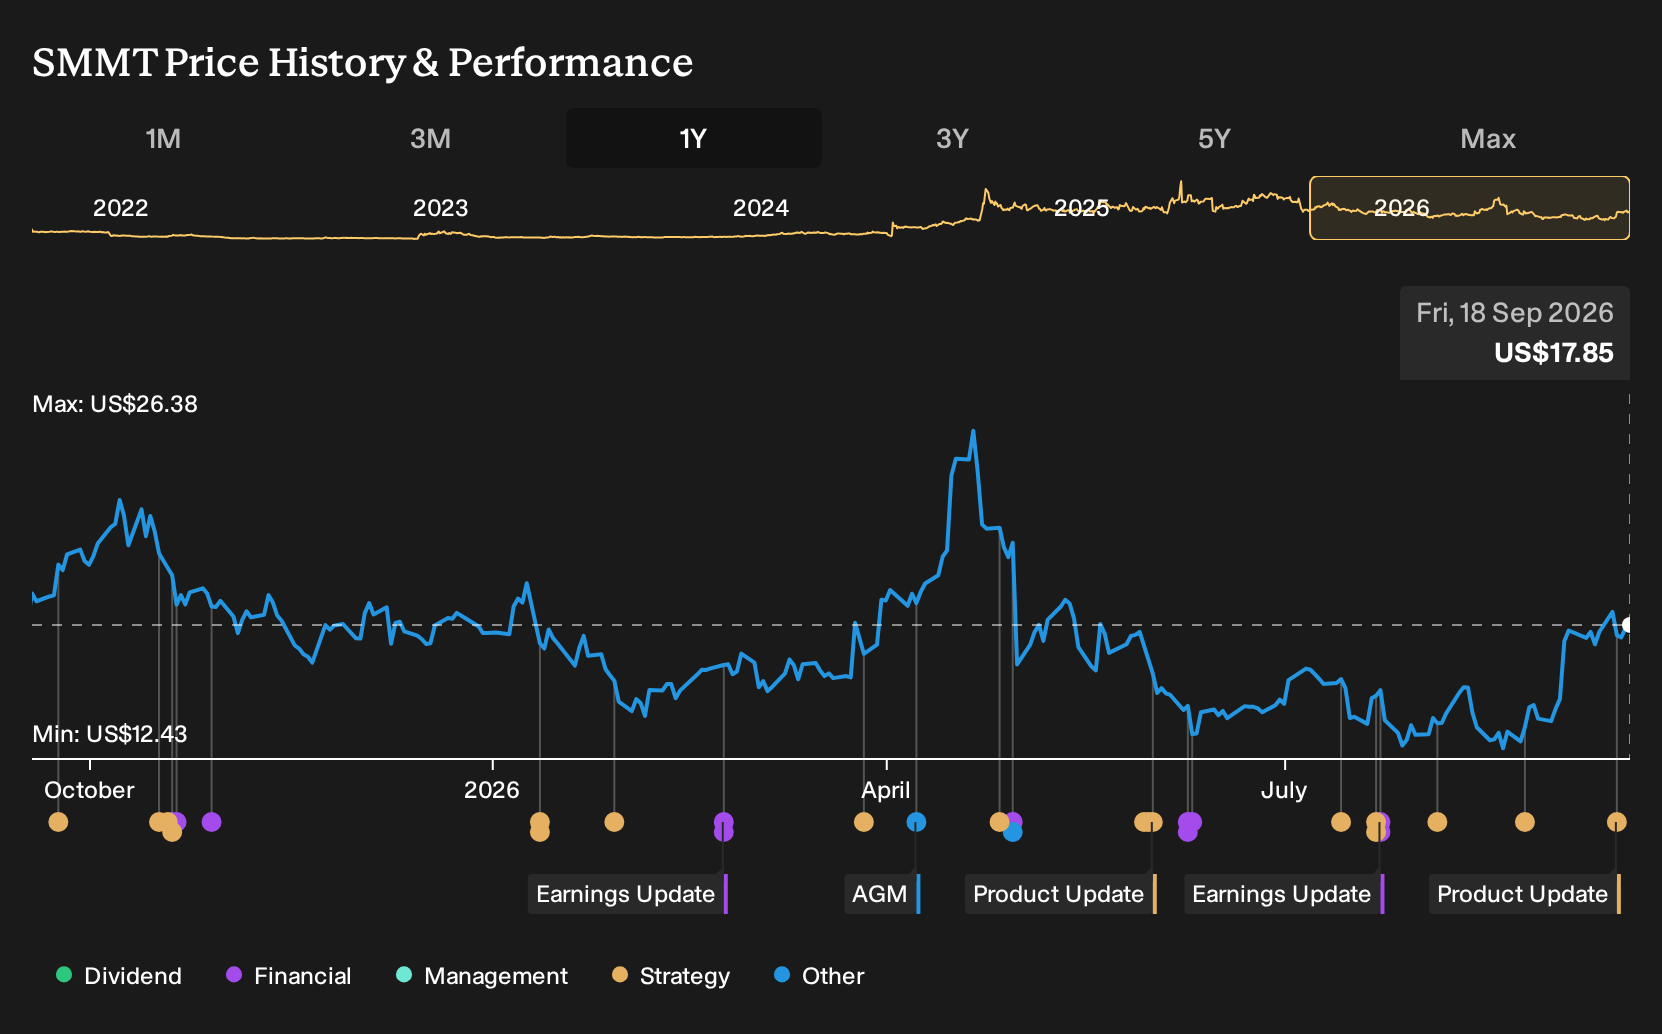
For an investor to stay with Summit Therapeutics, there needs to be conviction that ivonescimab can move from a single late stage asset to a commercial franchise across several tumor settings. The updated HARMONi survival readout feeds directly into that view, because the U.S. BLA and the November 14, 2026 PDUFA date remain the key near term trigger for the whole story.
The biggest operational risk still sits with regulatory expectations for overall survival and the fact that Summit has no product revenue while spending heavily on R&D and commercial build out. The latest data strengthen the package feeding the FDA review, but they do not remove the binary nature of that decision or the funding pressure if approval timing slips.
The HARMONi 2026 World Conference on Lung Cancer update ties closely to earlier disclosures around the Biologics License Application for ivonescimab in EGFR mutated non squamous NSCLC. That BLA leans on both progression free survival and the evolving overall survival profile, so every additional data cut affects how robust the submission looks going into the PDUFA deadline.
HARMONi now sits alongside HARMONi 2 in China, where Akeso reported ivonescimab monotherapy with an overall survival hazard ratio of 0.73 versus pembrolizumab and a median follow up of 36 months. Together, these trials frame the near term catalyst path for Summit Therapeutics and also highlight the concentration risk if any major Phase III outcome or regulatory review falls short of expectations.
Summit Therapeutics' current analyst narrative points to revenue of US$1.3b and earnings of US$223.0m by 2029, starting from a base of zero revenue and a loss of US$856.1m today. This implies roughly 60% yearly top line growth and an earnings swing of about US$1.1b over that period.
Uncover why Summit Therapeutics' fair value indicates a 64% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts frame the updated HARMONi survival signal as a potential springboard for a much larger Summit Therapeutics story. Before this news, they were already penciling in US$2.5b of revenue and US$272.9m of earnings by 2029, compared with consensus at US$1.3b and US$223.0m. That gap shows how far opinions can stretch, so it makes sense for you to revisit both sets of assumptions and decide which version of Summit’s future feels closer to your own view as this fresh data filters into forecasts.
Explore 4 other Summit Therapeutics fair value estimates, including one that suggests as much as 887% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Summit Therapeutics research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Summit Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Summit Therapeutics' overall financial health at a glance.
Looking for more investment ideas beyond Summit Therapeutics?
Once you have a view on Summit Therapeutics, it can help to widen the lens and compare it with other opportunities that match your risk profile and income goals. The Simply Wall St Screener lets you quickly filter for different styles of stocks so you can see where ivonescimab’s story sits alongside sturdier balance sheets, income plays, or earlier stage growth.
- If capital preservation comes first for you, focus on sturdier businesses by scanning a 30 resilient stocks with low risk scores that aim to keep risk levels contained.
- Income oriented investors can zero in on cash return potential by reviewing a curated set of 7 dividend fortresses that may suit a yield focused portfolio.
- Those hunting for future growth stories can broaden their watchlist by running through a 16 high quality undiscovered gems that combine strong fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com