


Visteon (VC) Stock Trades Near Fair Value On Current Earnings
Visteon has seen its share price slide over the past year, which puts fresh attention on a simple question for you as an investor. Is the current US$94.61 price tag in line with what the company is earning today and is expected to earn down the road.
- Over the last 3 years the stock has fallen 30.7%, which puts more weight on whether earnings can support even the current valuation.
- The business depends heavily on turning its automotive electronics contracts into consistent profits, so the durability of those earnings streams may shape how comfortable you feel paying today's multiple.
- Your read on Visteon is one view; the desks covering it have another. See what analysts think Visteon's shares could be worth.
The issue now is whether Visteon's current share price is justified by its earnings power and the P/E level that those profits support.
If you are weighing whether Visteon's P/E fits its earnings profile, it can help to compare that question across a wider group using the 35 high quality undervalued stocks.
Where Does Visteon Sit on Earnings?
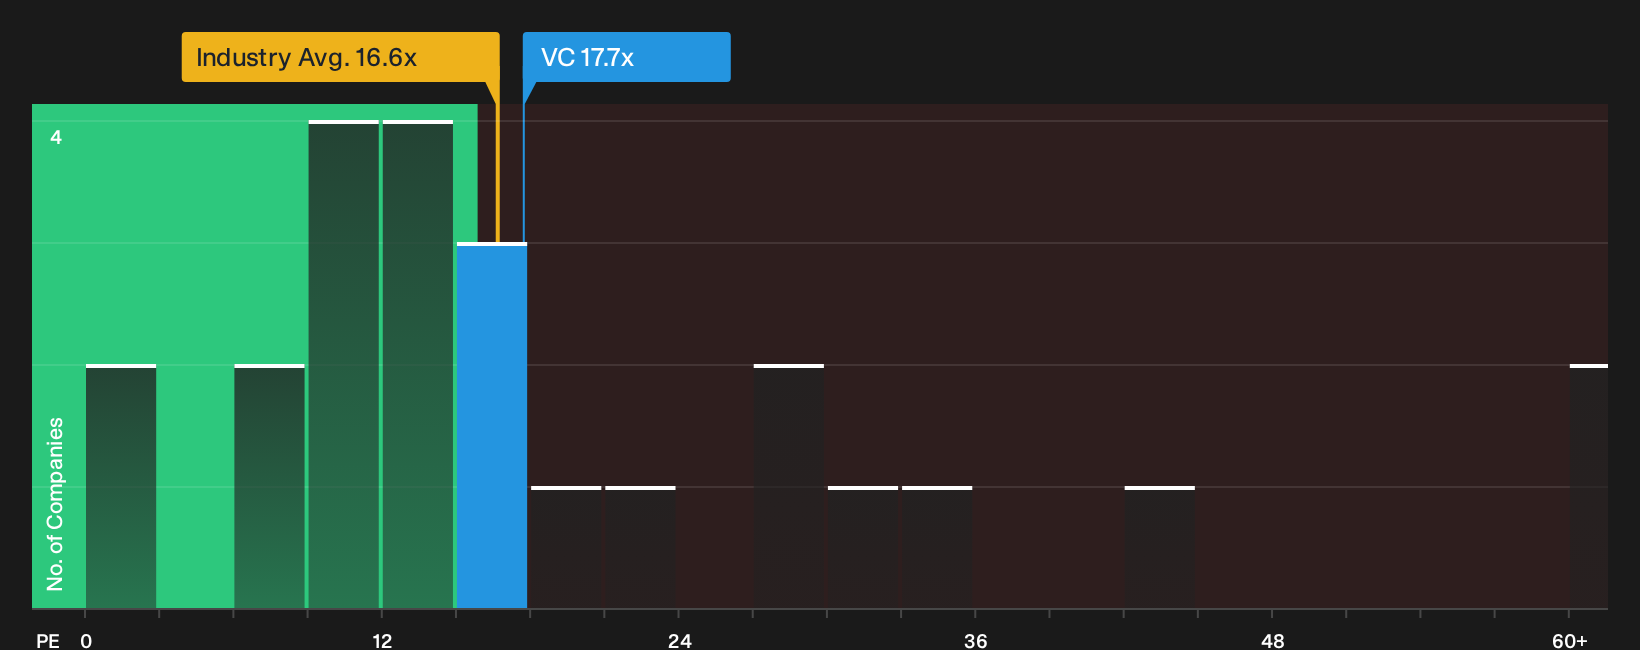
The current P/E of Visteon sits around 17.7x, which lines up with how the market often prices an established auto components business with clear earnings.
At roughly 17.7x earnings, Visteon trades very close to the Auto Components industry average near 16.6x and the peer group around 11.9x. The stock also clusters around the tailored fair multiple that factors in its margins, growth profile, size and risk, so the market is not placing a clear premium or discount on the shares on this measure alone. For you as a shareholder, the key question is whether the quality and durability of Visteon's earnings justify paying a P/E that broadly matches what the model suggests as a reasonable anchor. Explore the numbers behind Visteon's P/E valuation.
The Visteon Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take the P/E puzzle around Visteon and translate it into specific paths for growth, margins and earnings that would need to play out for the stock to be worth materially more or less than it is today. They sit on the platform's Community page. Instead of a single output from a ratio or model, Narratives set out the future those numbers rest on so you can watch how closely reality lines up with that story.
One of the top community narratives on Visteon: 35% undervalued
"Analysts broadly agree that Visteon's leadership in automotive displays and cockpit AI can drive long-term revenue growth, but the magnitude may be significantly understated..."
Discover why this Narrative puts Visteon at 35% undervalued.
Before acting on Visteon’s valuation, there is one more piece to check
Price, earnings and market comparisons only show part of the picture for Visteon, because the people steering the business and the way their pay is structured can strongly influence how those numbers evolve over time. See who runs Visteon and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com