


What MYR Group (MYRG)'s Expanded Credit Facility Means For Shareholders
- MYR Group Inc. recently entered a five year Fourth Amended and Restated Credit Agreement, securing a US$690 million revolving facility plus US$150 million and C$70 million term loans, with multi currency features, letters of credit capacity and swingline availability.
- The enlarged and more flexible borrowing capacity, including an option to add up to US$445 million of incremental commitments, provides MYR Group with additional scope to fund working capital, capital projects and potential acquisitions without immediately relying on equity issuance.
- This article examines how MYR Group's broader credit capacity may influence the investment narrative centered on electrification demand and capital deployment.
MYR Group Investment Narrative Recap
To own MYR Group, you need to be comfortable with a contractor that leans heavily on transmission, distribution and commercial work tied to electrification, while accepting that renewables are a smaller slice of the mix than before. The enlarged credit agreement strengthens liquidity and can support bidding and execution on large grid and data center projects, but it does not change the basic thesis.
The near term swing factor still sits in backlog quality and execution, especially in lumpier commercial and industrial work where timing can move revenue and cash flow around. The biggest risk remains tight labor markets and rising wage bills putting pressure on margins, particularly if utility or industrial demand softens while MYR Group is ramping spend for new projects.
The refreshed five year credit agreement is the key recent update tied to these catalysts. It refinances older facilities and adds more flexible borrowing, letters of credit and multicurrency capacity that are often essential to win and perform on large utility and infrastructure contracts, especially when customers demand bonding and balance sheet support.
For you as an investor, that financing structure affects how MYR Group can fund working capital swings, capital expenditure and any future acquisitions without immediately tapping equity. It can also reinforce the firm’s ability to pursue higher margin mix such as data centers and storage, while still carrying the risk that heavier use of debt funding and project missteps would pressure returns if earnings or backlog become more volatile.
MYR Group's current analyst narrative points to revenues of US$6.1b and earnings of US$299.8 million by 2029, based on assumed 15.0% yearly revenue growth and a change in profit from US$165.3 million today. This implies an earnings increase of about US$134.5 million from current levels if those projections occur.
Uncover why MYR Group's fair value indicates a 48% potential upside to its current price, which could narrow quickly.
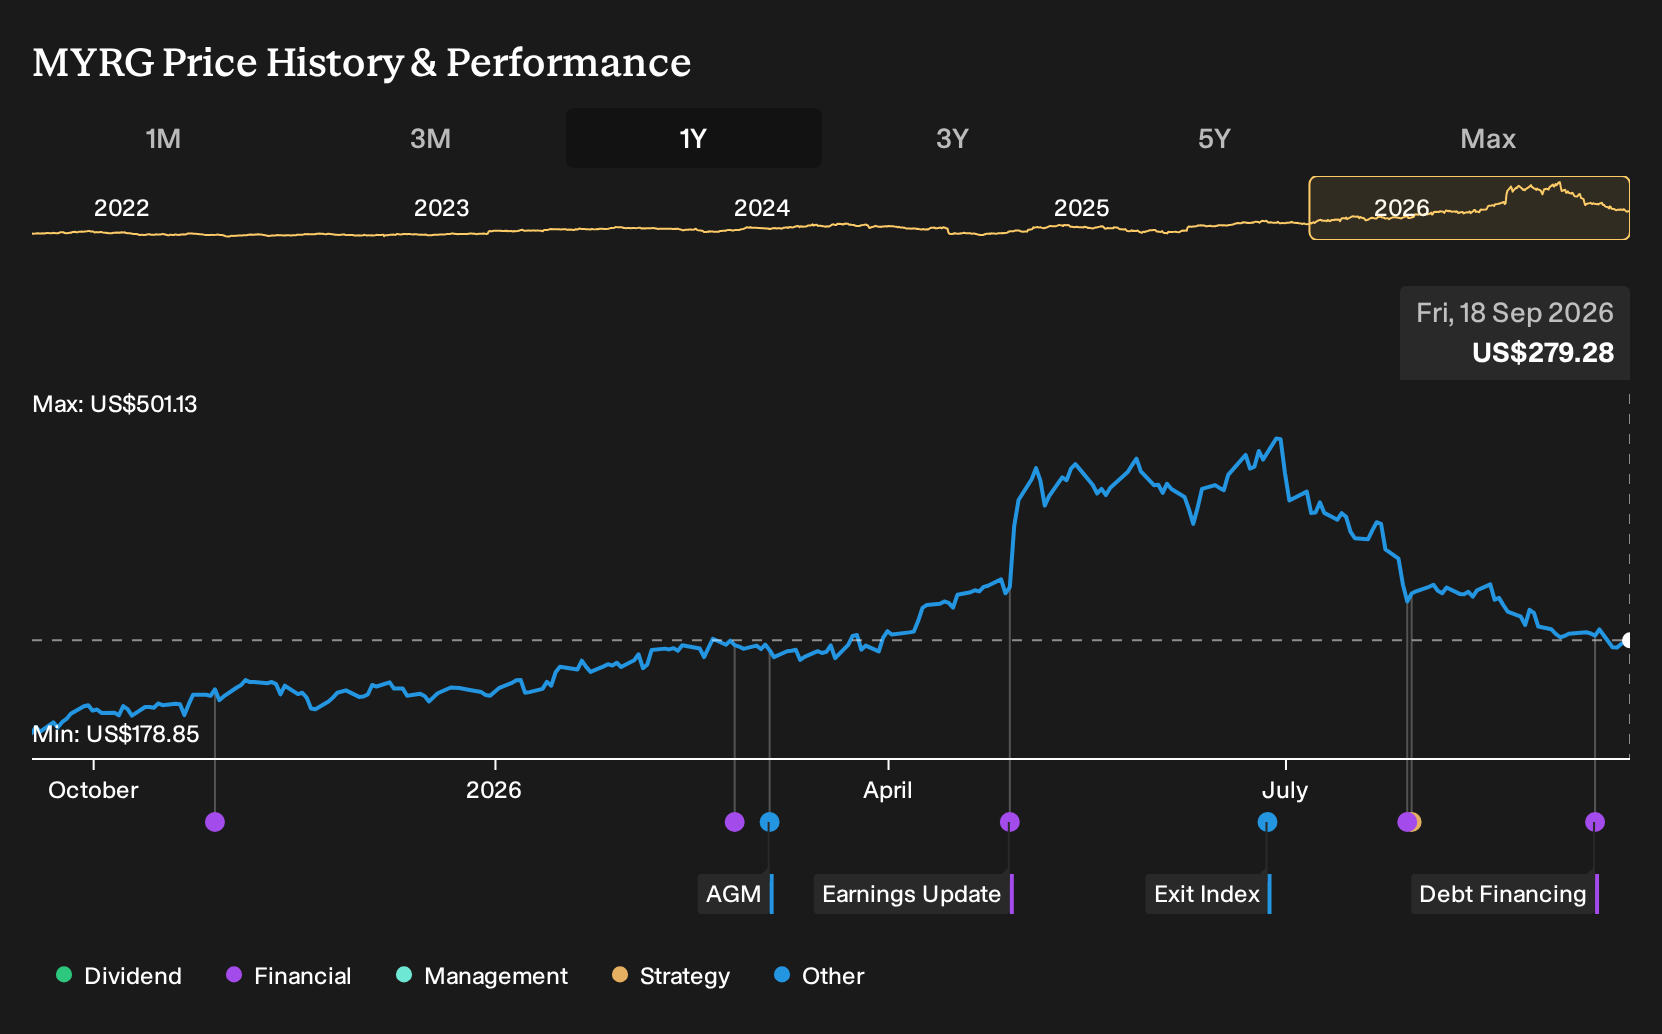
Exploring Other Perspectives
One bullish twist on MYR Group is that some analysts focus less on debt risk and more on what extra capacity could mean if data center work accelerates. Before this new credit deal, the most optimistic group already penciled in US$6.4b of revenue and US$306.7 million of earnings by 2029. Those targets and the new financing both predate each other, so you may see forecasts shift as analysts revisit how much balance sheet firepower really matters.
Explore 4 other MYR Group fair value estimates, including one that suggests as much as 71% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your MYR Group research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for MYR Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MYR Group's overall financial health at a glance.
Looking for more MYR Group sized investment ideas?
If MYR Group has sharpened your interest in infrastructure and capital allocation, it can help to scan a wider field of opportunities using structured filters rather than jumping ticker to ticker.
- For investors who prioritize resilience and lower downside risk, consider starting with a curated set of companies that screen well on balance sheet strength and fundamentals via the list of solid balance sheet and fundamentals (23 results).
- If upside potential is your main focus, you might prefer to comb through a carefully filtered pool of attractively priced businesses with solid quality markers using the 35 high quality undervalued stocks.
- Income focused investors who want cash flow from payouts rather than just price moves can zero in on sturdier payers with higher yields through the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com