


A Longtime Bear on FuelCell Energy Stock Just Turned Bullish. Here’s What Changed.
FuelCell Energy (FCEL) just got a vote of confidence roughly a week after its earnings report. Craig-Hallum reinstated coverage with a “Buy” rating and a $22 price target, well above the current $15.50. What’s interesting is that the same firm dropped coverage of the stock back in early 2024. Its complaint then was a messy product focus and minimal product backlog. So a new “Buy” rating from a firm that walked away in the past means something. The reason for the change is the data center boom. Analyst Eric Stine sees FuelCell’s molten carbonate technology as a strong match for powering AI data centers. It runs nonstop, powers a site directly, and gives reliable, steady electricity. Interest in on-site data center power is growing fast. Stine believes FuelCell now belongs in that conversation, with a clearer path to real product sales and, eventually, profits.
The Wins Are Real, but So Are the Risks
There’s evidence behind the call. As I covered when FuelCell signed its Siemens deal, the company’s path to profitability runs through large data center projects. Its latest quarter showed that shift is starting to happen. FuelCell landed its first data center order and a 75 MW capacity reservation in Texas with a major operator. Total committed and awarded capacity backlog climbed to $3.6 billion, and the company holds $737 million in cash to fund its expansion.
But the quarter also came with problems that shouldn’t be ignored. Third-quarter revenue fell 29% to $33 million, and the company remains deeply unprofitable. Management doesn’t expect positive adjusted EBITDA until late fiscal 2027. It also flagged that much of that $3.6 billion backlog is reserved capacity rather than confirmed orders. That means it isn’t guaranteed to become revenue, and even the part that does may arrive later than expected.
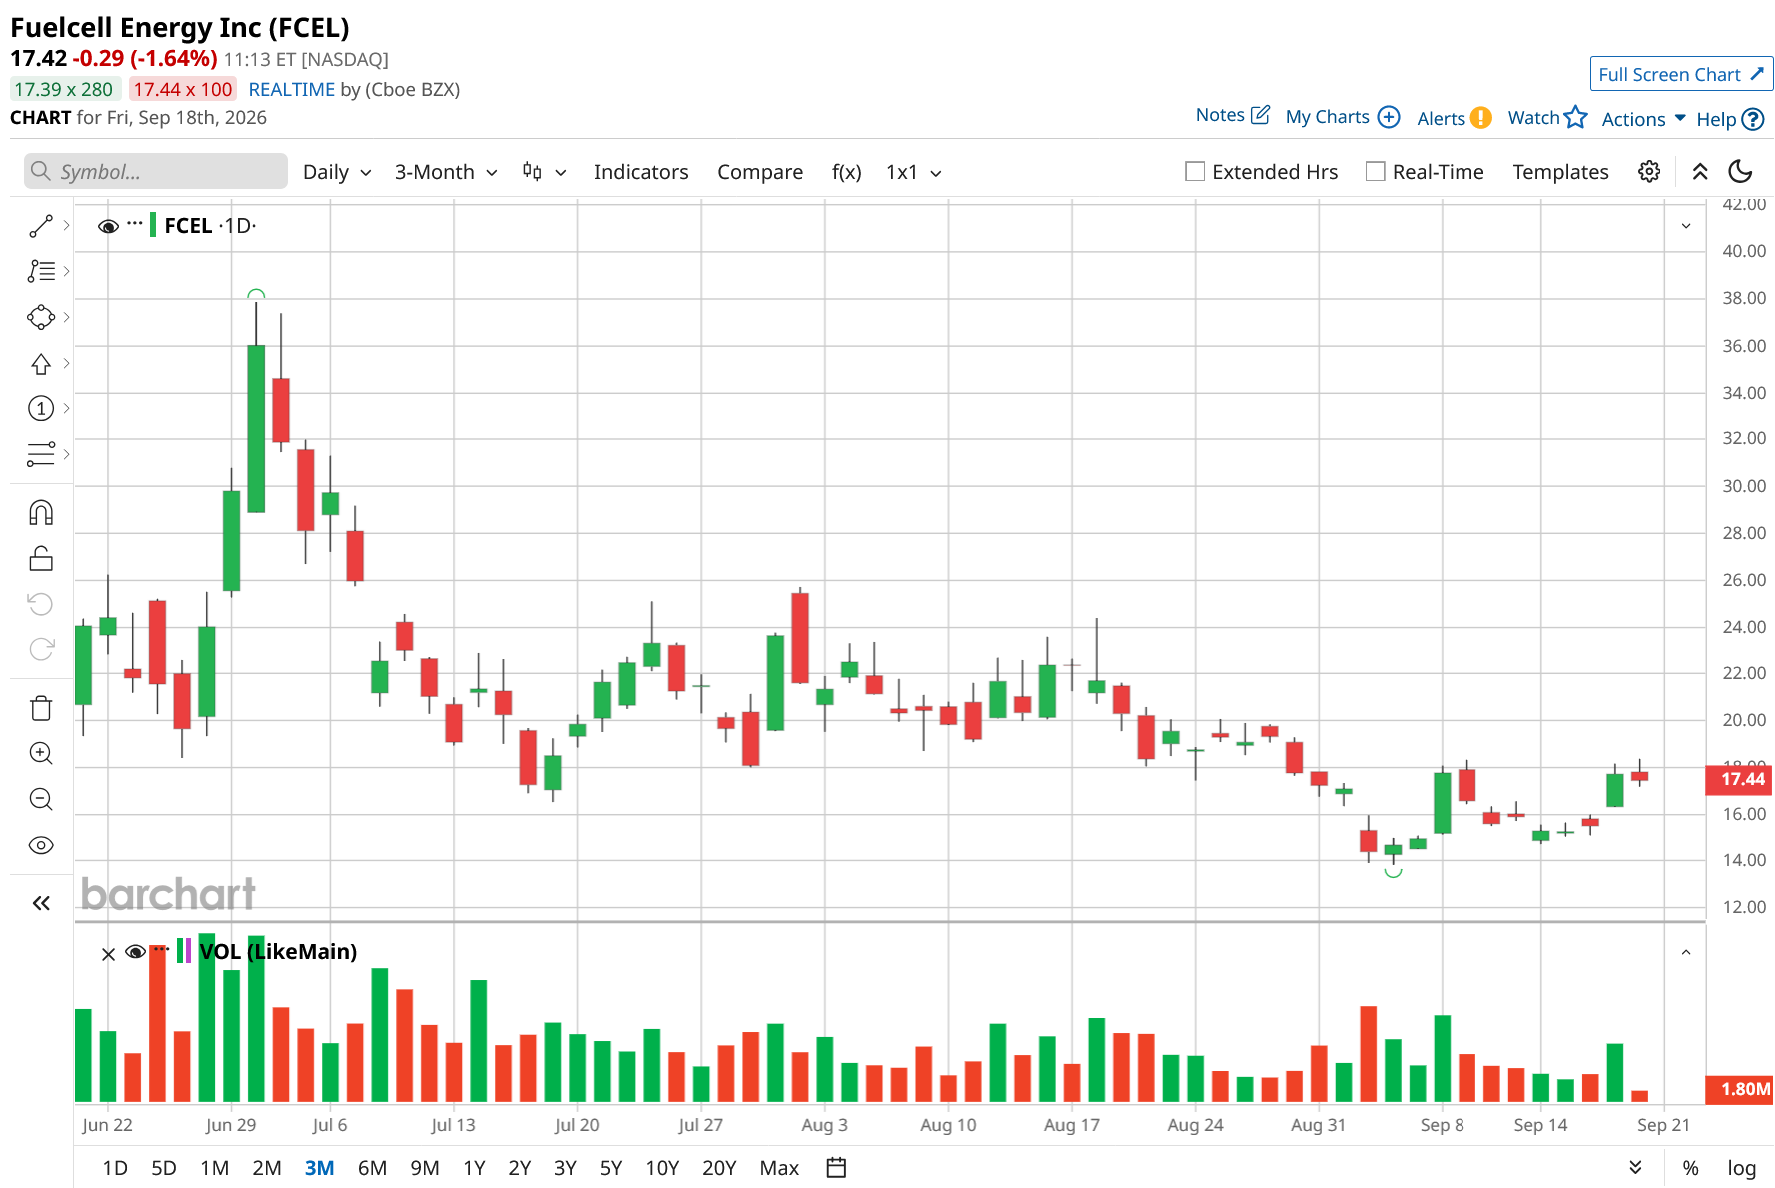
FCEL stock has dropped about 53% from its 52-week high at the end of June. This shows how skeptical investors remain. The data center opportunity is genuine, but FuelCell still has to deliver on it.
About FuelCell Energy Stock
FuelCell Energy is involved in the production of fuel cells intended for clean electricity generation. The company is a beneficiary of the data center and AI boom because of its ability to provide power quickly and in an environmentally friendly manner. It helps provide an alternative to the massive grid delays, which are currently the biggest bottleneck in data center deployments. The firm is headquartered in Danbury, Connecticut.
FCEL stock more than doubled in a matter of weeks after its Q2 earnings. Since reaching its 52-week high in late June, however, the stock has dropped just as sharply. FCEL currently trades at roughly $17.40, far below the $37.88 share price it carried just two and a half months back.
Since FuelCell Energy isn’t profitable, it makes little sense to look at its valuation multiples. It has a forward price-to-sales multiple of 8.32x, which is only slightly higher than its five-year average multiple of 7.49x. The stock had certainly become overvalued in June, but there are good reasons for the excitement we witnessed in that month. The company’s technology offers a fast way to set up the power infrastructure for data centers. It is expected to grow its earnings by 60% on average over each of the next three years, which suggests that a sales multiple in line with the five-year average is a fair multiple to pay.
FuelCell Energy Bets on Scale to Drive Profitability
FuelCell Energy reported its third-quarter fiscal 2026 earnings on Sept. 2. It missed both earnings and revenue estimates for the third quarter. Revenue was $33 million, down 29% from $46.7 million a year earlier. The decline in product revenue was tied in part to the completion of the 42-module Gyeonggi Green Energy repowering project in South Korea. The company reported a net loss of $45.3 million, improved from a loss of $91.1 million in the prior year quarter. However, the company said it is seeing strong demand from data center customers, where it is positioning its fuel cell systems.
Looking forward, the company appears to be optimistic as it is planning to achieve positive adjusted EBITDA results in the fourth quarter. The company lowered its fiscal 2026 capital spending guidance to $10 million to $20 million. Management said the reduction was due to the timing of equipment deliveries, not project delays or operational issues. On a positive front, the company reaffirmed that Torrington expansion remains fully funded, supported by approximately $298 million.
What Are Analysts Saying About FCEL Stock?
Following the third-quarter earnings, analysts upgraded their financial models and came up with new price targets. On Sept. 8, Jefferies lowered the firm’s price target on FCEL from $24 to $20 and kept a “Buy” rating. The lower price target revision reflects near-term pressure faced by the company from higher costs related to the FIT deal order. However, the firm believes that EBITDA and margins should improve as production ramps. In contrast, Citi initiated coverage of FCEL with a “Hold” rating and a price target of $19. The firm believes the company has not yet shown a meaningful increase in turning potential projects into actual orders.
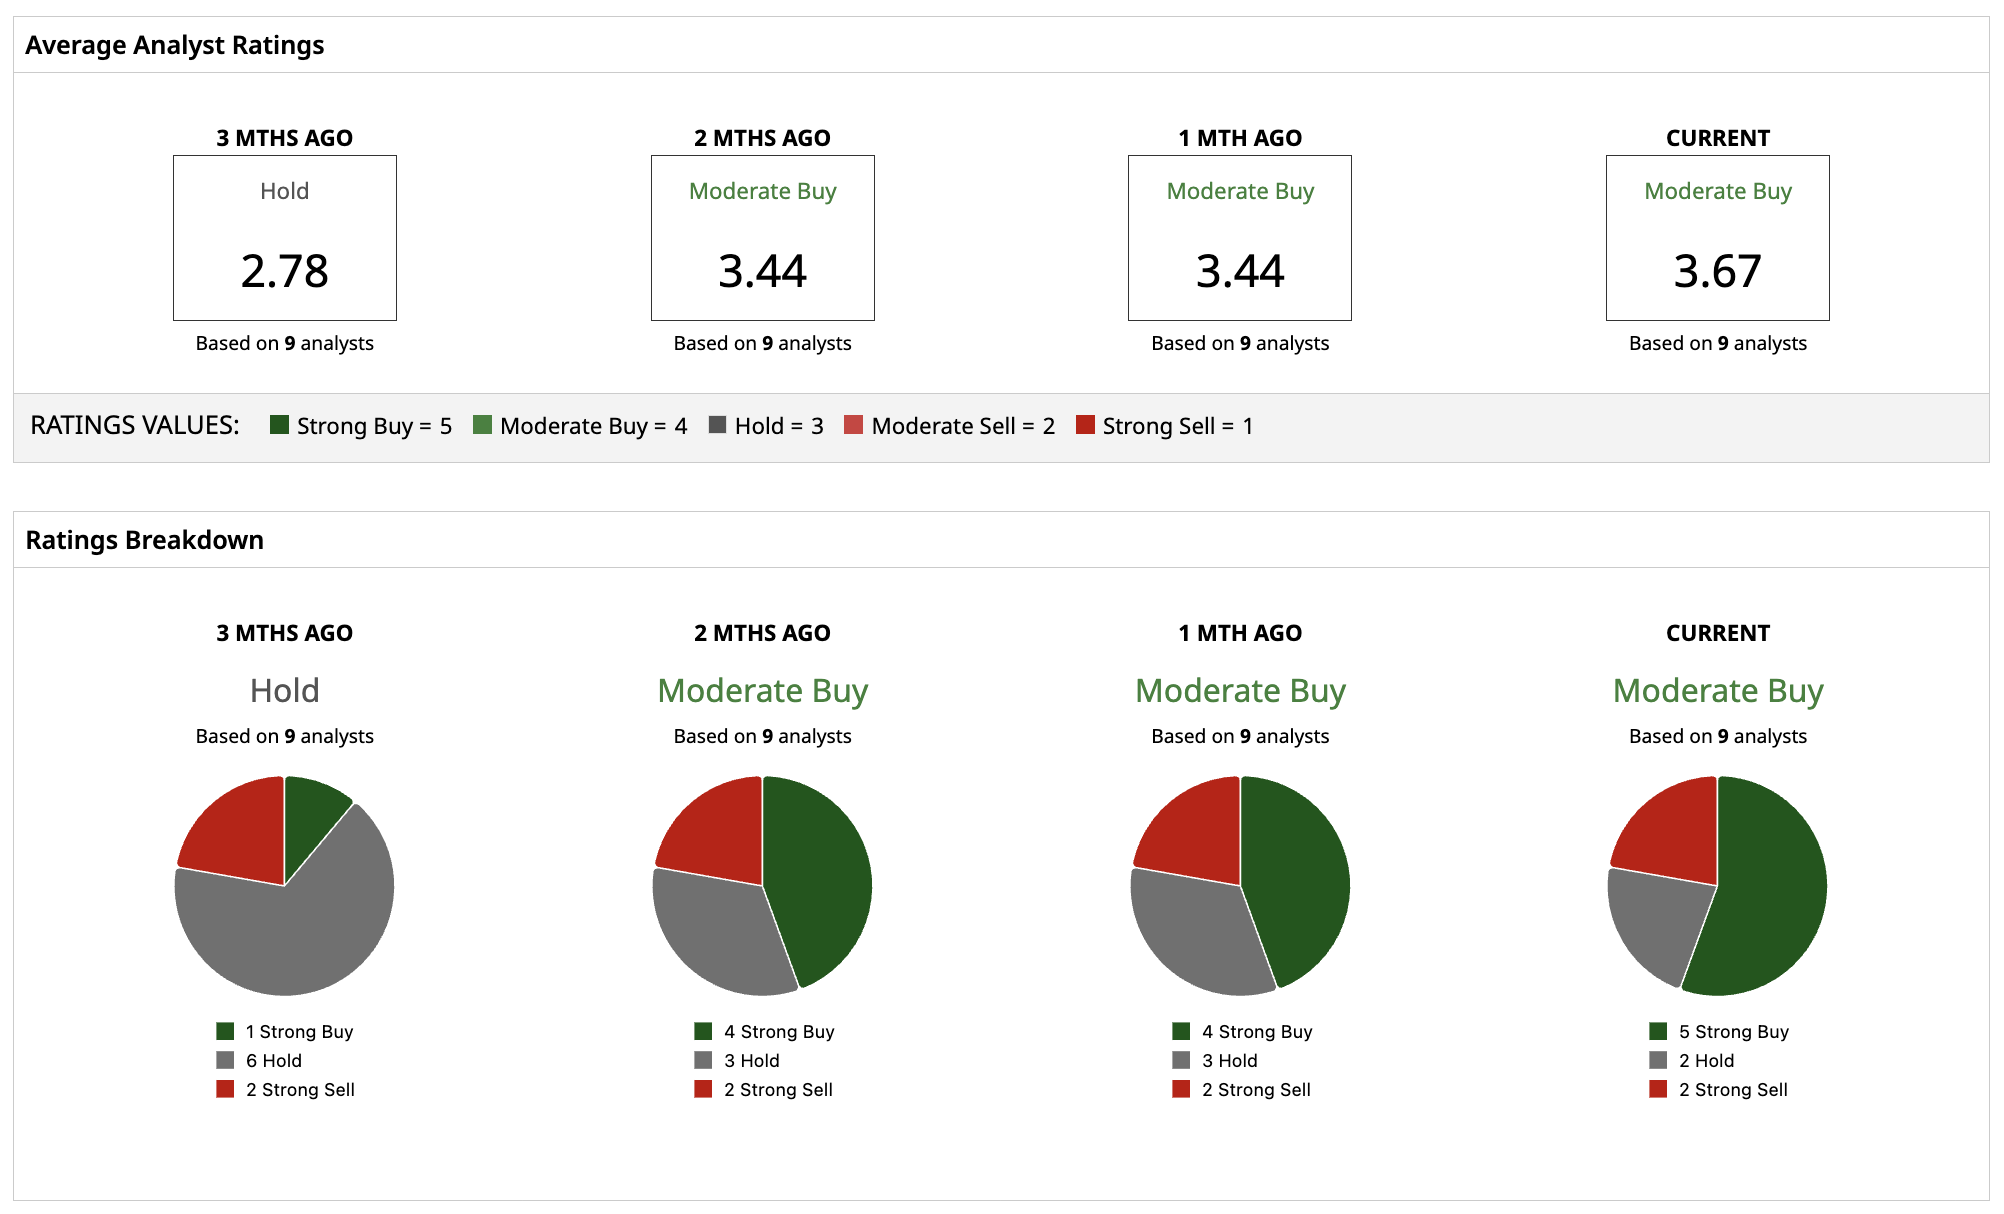
Based on nine Wall Street analysts covering FCEL stock, it holds a consensus “Moderate Buy” rating. Out of those, five have a “Strong Buy” rating, two have a “Hold” rating, and two have a “Strong Sell” rating. The stock has a median price target of $21, which reflects 37% upside from the current share price.
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.