


Is Nelnet (NNI) Fully Valued As New Directors Join Its Board?
Nelnet (NNI) just expanded its board to 10 directors, adding Apple executive Angie Klein and infrastructure investor Ed Pallesen, which gives investors fresh angles on marketing, capital allocation, and risk oversight at the education finance group.
Nelnet’s recent board refresh comes as the shares have drifted lower in the short run, with the 90 day share price return down 2.82% and the year to date share price return down 2.26%. However, the 5 year total shareholder return of 67.60% points to momentum that has built over a longer horizon.
Compare Nelnet's boardroom reshuffle with other financial players by scanning a curated set of 16 high quality undiscovered gems that may be quietly rebuilding for their next phase of growth.
Nelnet trades only slightly below analyst targets even as Wall Street questions its growth options and return on equity. Is that small discount a chance to be early, or a warning that caution is still warranted?
Price-to-Earnings of 14.9x: Is it justified for Nelnet?
Nelnet trades at a P/E of 14.9x, which puts a premium on its $126.07 share price compared with several peers, even though earnings have declined in recent years.
The P/E ratio links what you pay today to the profit the business currently generates. For a diversified financial group like Nelnet, that multiple reflects how much confidence investors have in the durability of its loan servicing fees, education technology income, and bank related earnings.
Earnings have declined by 10.6% per year over the past 5 years and fell 8.3% over the past year, yet the valuation still sits above the Consumer Finance industry average of 9.1x and the peer average of 9.5x. That gap indicates that the market is paying a higher multiple for Nelnet relative to similar stocks, rather than marking the shares at a discount.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 14.9x (OVERVALUED)
Still, Nelnet’s earnings decline over the past 5 years and its premium P/E versus consumer finance peers could unwind quickly if sentiment on its diversified model weakens.
Find out about the key risks to this Nelnet narrative.
Another view on Nelnet's valuation
On a multiples check, Nelnet already looks expensive next to consumer finance peers. The SWS DCF model goes further and suggests the stock is trading above an estimated future cash flow value of $20.84. This flags a much steeper potential valuation gap for you to weigh. Does that make the current $126.07 price feel defensive or stretched?
Look into how the SWS DCF model arrives at its fair value.
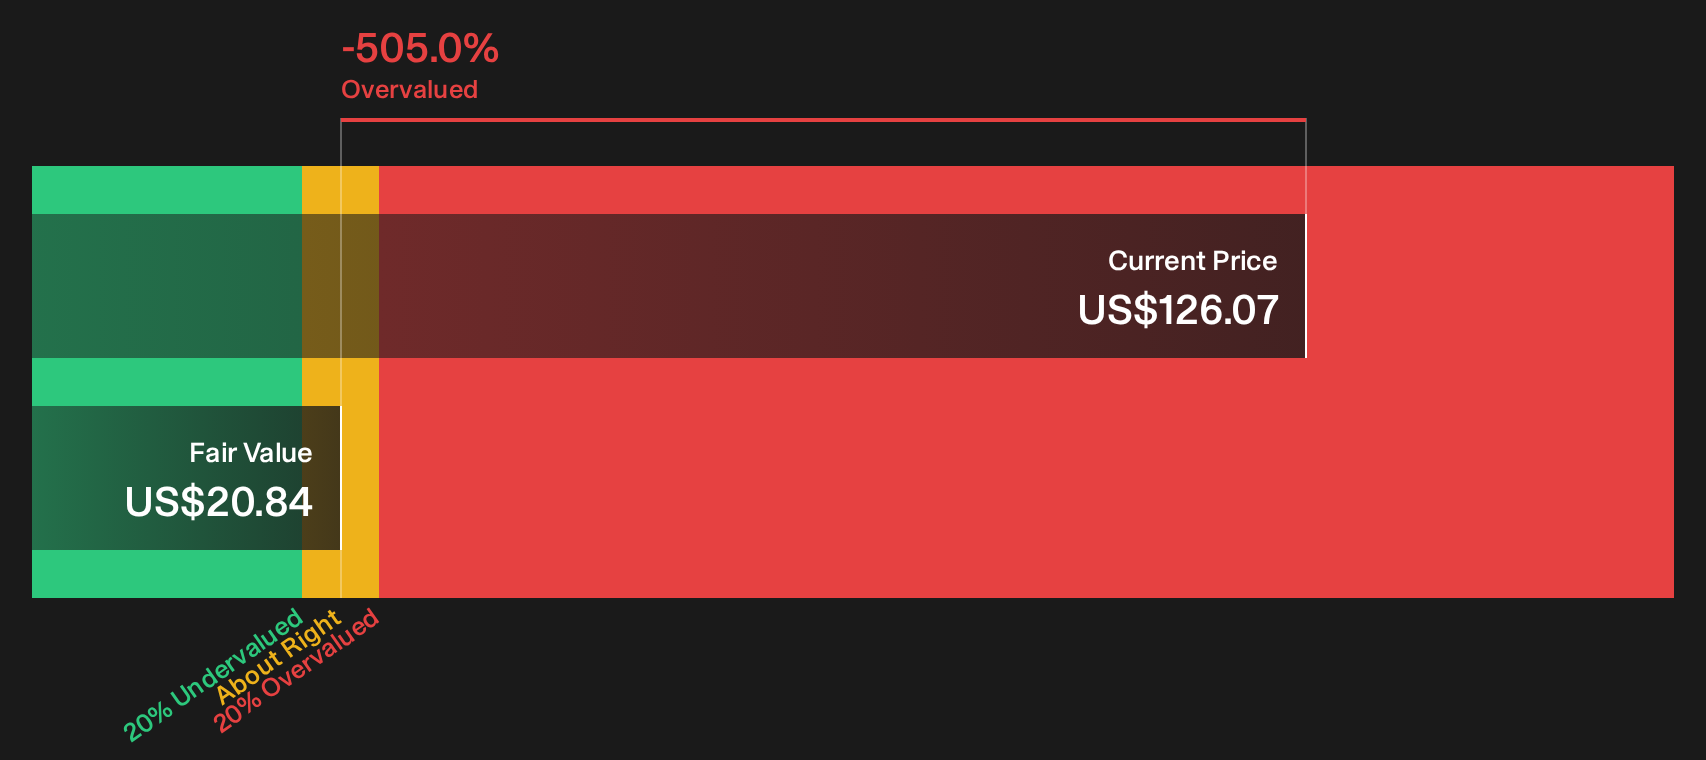
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nelnet for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Nelnet appears mixed. Consider acting promptly, review the underlying data for yourself, and weigh both sides of the story with 1 key reward and 2 important warning signs
Looking for more investment ideas beyond Nelnet?
Do not stop with Nelnet. Use today’s research momentum to scan other opportunities that fit your style, risk tolerance, and return expectations across the market.
- Hunt for potential mispriced opportunities by reviewing companies highlighted in the 35 high quality undervalued stocks.
- Prioritise resilience and aim to sleep better at night by focusing on businesses from the 30 resilient stocks with low risk scores.
- Strengthen your watchlist with financially robust operators using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com