


3 US Stocks Riding Electric Pickup Battery Localization Growth
The electric pickup story is quietly shifting from truck beds and tow ratings to battery chemistry and factory addresses. CATL’s push to license tall battery designs into the US throws a spotlight on which businesses could gain from local production, tighter rules and fiercer competition. This article walks through three stocks exposed to that news and how each might fit, or not, in a long term portfolio.
The three businesses profiled below are just a sampling, while the full screen surfaced 33 more companies with equally detailed pickup and battery localization stories that are not covered here. To identify and analyze the highest conviction ideas from that broader list, head straight into the US-Listed Electric Pickup & Battery Localization Beneficiaries screener.
Dana (DAN)
Dana plugs directly into the screener’s theme because it supplies the driveline, cooling and battery related hardware that lets US pickup makers localize electric platforms and integrate tall-pack batteries without redesigning entire trucks from scratch.
Dana generates about US$5.4b of revenue from Light Vehicle products and roughly US$2.4b from Commercial Vehicle parts, giving wide exposure to on-highway axles, e-drivetrains and thermal systems, and the business carries a market value of about US$3.2b.
"Dana has a 3 year net new sales backlog of about US$950 million and has secured a RAM Dakota axle program worth US$250 million of annual sales."
How that pipeline translates into actual returns will hinge on a single pressure point that could sharply swing future profitability.
That pressure point is exactly what the full narrative for Dana unpacks, showing how Dana’s backlog, capital choices, and execution risk could be decoupling from the headline order wins.
Gentherm (THRM)
Gentherm brings the screener theme into the cabin and battery pack, supplying thermal and comfort technology that rides along with every electric pickup and helps automakers meet efficiency goals as more hardware and software content gets packed into US built trucks.
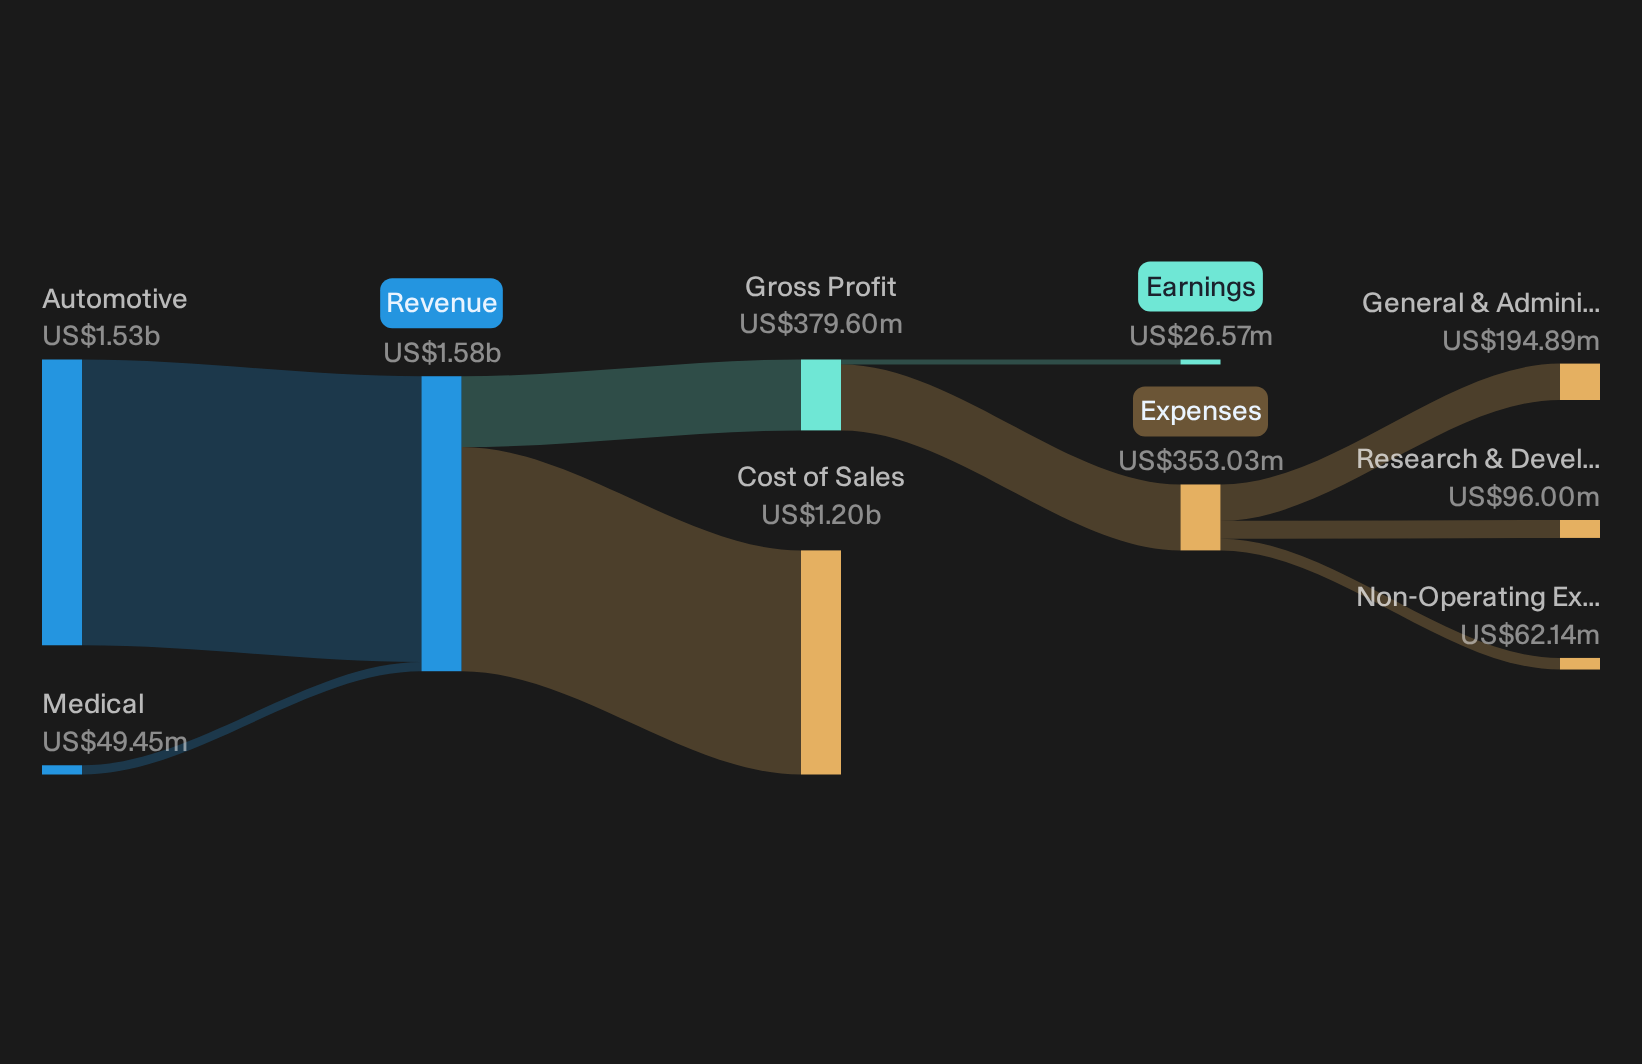
Gentherm generates about US$1.53b of revenue from Automotive and roughly US$49 million from Medical, wrapping seat comfort, climate control and battery performance hardware into a global supply footprint, and the stock carries a market value of about US$1.1b.
"Accelerating adoption of comfort and wellness features (like pneumatic lumbar, massage, and climate-controlled seating) by mainstream, high-volume vehicle platforms, as demonstrated by new multi-year awards from Ford, GM, Hyundai, and multiple Chinese OEMs, suggests higher content-per-vehicle and robust revenue growth ahead as these features become industry standard rather than luxury-only."
What investors in Gentherm really need to watch is how one unresolved cost and pricing pressure shapes the payoff from all that extra content.
That pricing squeeze is exactly what the full narrative for Gentherm unpacks, showing how Gentherm’s content gains could be masking both underappreciated earnings power and real execution risk.
Modine Manufacturing (MOD)
Modine Manufacturing ties into the electric pickup and battery localization story through the thermal plumbing that keeps high power batteries and electronics within a safe temperature window. Its real draw for investors is how that cooling know how spills into faster growing areas.
Modine Manufacturing designs mission critical thermal systems for vehicles, buildings and electronics, generating about US$1.1b from Performance Technologies within US$2.3b of segment adjusted revenue, and the stock carries a market value near US$10.0b.
"The accelerating build-out of data centers and the need for next-generation cooling solutions are driving extraordinary demand for Modine's products, with management forecasting the potential to double data center revenues from ~$1 billion in fiscal '26 to $2 billion by fiscal '28."
What matters next is how one quiet constraint on that expansion shapes the balance between fast top line growth and the margins behind it.
That quiet constraint is exactly what the full narrative for Modine Manufacturing lays bare, showing where Modine Manufacturing’s data center momentum could accelerate further and where capacity limits may still bite.

Seeking Fresh Alternatives Beyond These Three?
Fresh ideas move first, then the crowd follows. Spot early breakout momentum while it still flies under the radar for now. Do not wait; consider acting early.
- Consider resilient compounding potential with a curated 30 resilient stocks with low risk scores that helps you focus on businesses that may hold up when momentum in other areas starts dropping.
- Target companies with established cash generation using the 38 profitable AI stocks that aren't just burning cash so you are tracking AI players where revenue and earnings already support the excitement, not just the story.
- Explore long term income ideas through the 7 dividend fortresses and see which high yield opportunities might be offering solid payouts while attention stays elsewhere.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com