


Lam Research Stock and the Case for Future Chip Factory Spending
- Lam Research recently saw strong buying interest as semiconductor equipment peers rallied, reflecting investor focus on future fab capital spending rather than current chip demand.
- The move highlights how Lam Research’s prospects are closely linked to long term wafer fab investment cycles. This reinforces the importance of tool demand visibility over short term end-market swings.
- Now the focus shifts to how Lam Research’s investment narrative ties into this renewed optimism around future wafer fab equipment spending.
Spot emerging momentum in Lam Research and similar chip equipment plays by scanning the 88 AI infrastructure stocks.
Lam Research Investment Narrative Recap
To own Lam Research, you need to believe that wafer fab equipment spending tied to AI, advanced logic, and 3D NAND justifies sustained demand for its etch and deposition tools, even with cyclicality. The latest 5% surge, led by optimism around future capex, aligns with that thesis but does not change the core story on its own.
The key near term swing factor remains customer capital spending plans at a handful of large foundries and memory makers. That is also the biggest operational risk, alongside China exposure and tariffs. A four day run in the SOX is helpful for sentiment, but it does not materially reduce those business risks.
In the context of this move, the most relevant reference point is still the existing outlook that analysts have set around Lam Research, rather than a fresh corporate announcement. Current expectations assume revenue growth of about 16.6% a year and earnings growth of roughly 21.3% a year.
The question for investors is whether the recent rally in chip equipment stocks makes that earnings path more plausible, or simply prices in optimism earlier. Forecasts also point to very high future return on equity and firm profit growth compared with the broader US market. Those projected gains sit against concentrated customers, high R&D needs, and elevated current P/E levels.
Lam Research's narrative projects US$45.8b revenue and US$17.3b earnings by 2029. This implies 25.4% yearly revenue growth and an earnings increase of about US$10b from US$7.3b today.
Uncover why Lam Research's fair value indicates a 29% potential upside to its current price, which could narrow quickly.
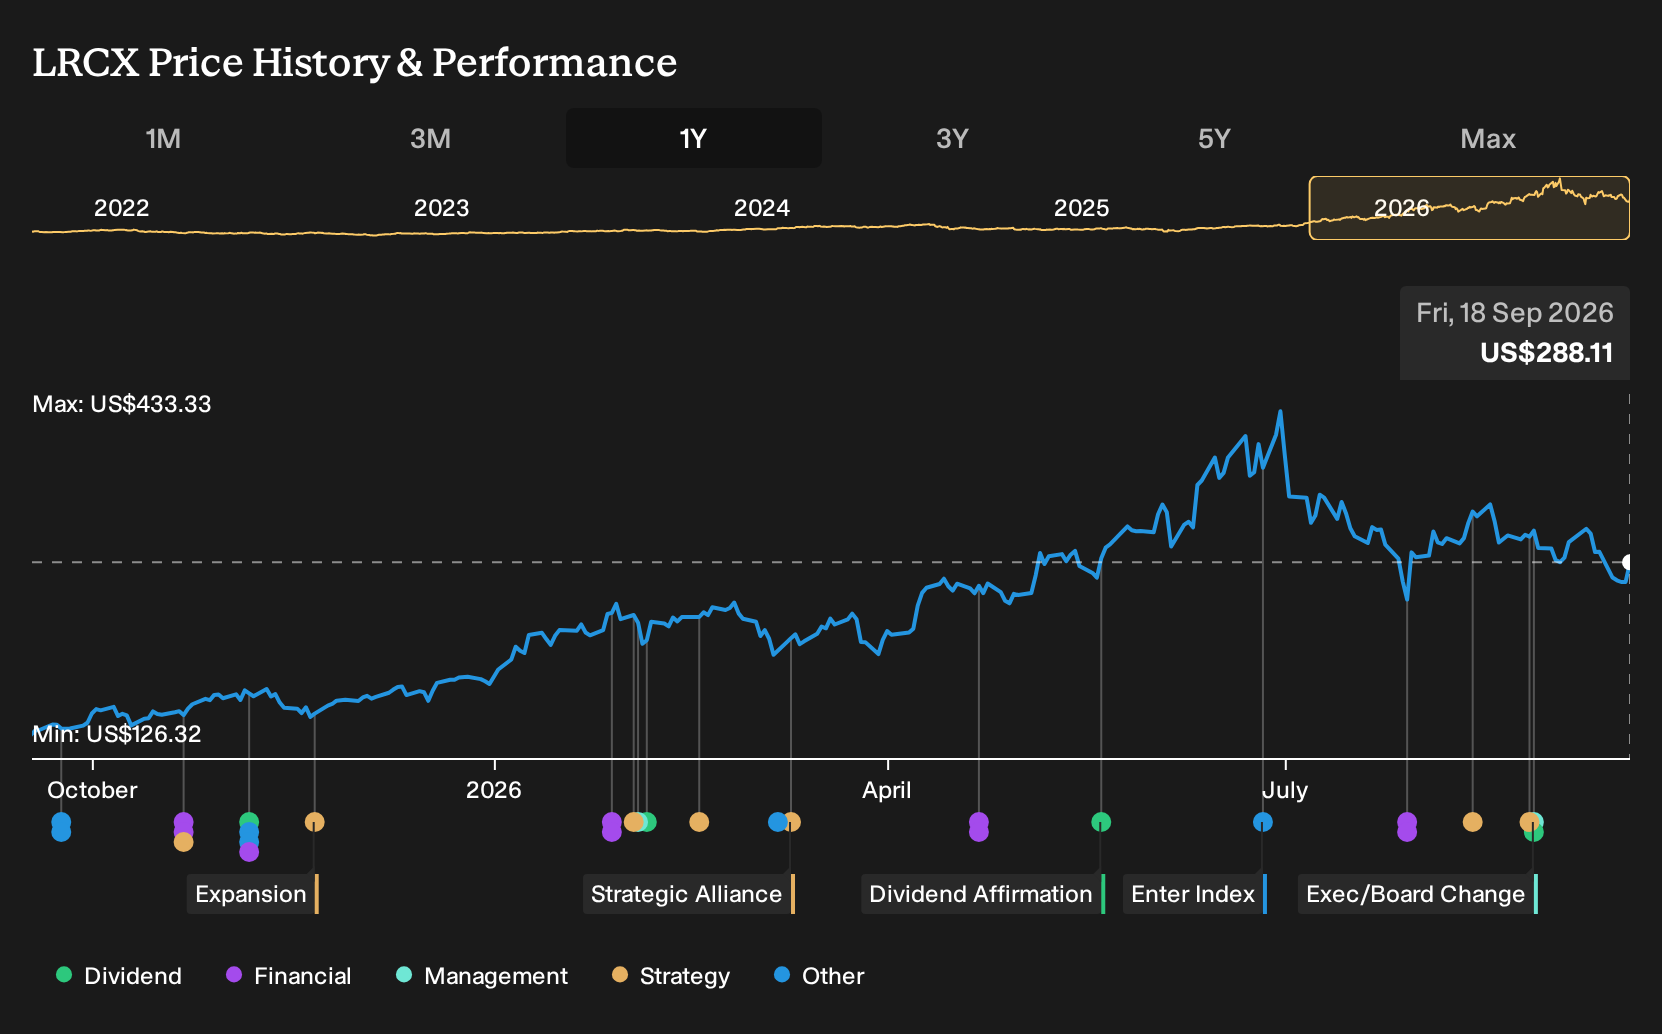
Exploring Other Perspectives
You are seeing Lam Research through a bullish capex lens, but the most cautious analysts keep circling back to export controls as the swing factor. Their earlier models pointed to about US$38.6b in revenue and US$14.3b in earnings by 2029. That more muted path could be revised again once this latest rally filters into forecasts.
Explore 7 other Lam Research fair value estimates, including one that suggests as much as 41% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Lam Research research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Lam Research. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lam Research's overall financial health at a glance.
Looking For More Investment Ideas Beyond Lam Research?
If you want to balance your view on Lam Research with fresh opportunities, the Simply Wall St Screener can surface companies that fit very different risk and return profiles.
- For investors who like hunting for potential mispricing, scan through 35 high quality undervalued stocks that may offer stronger fundamentals than their current share prices suggest.
- If capital preservation matters most to you, filter for companies on the 30 resilient stocks with low risk scores that score well on stability and financial resilience.
- When you want quality and growth but prefer businesses that are not already crowded, check out the 16 high quality undiscovered gems that the market may not be fully watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com