


Is Kilroy Realty (KRC) A Bargain As It Reaffirms Its Dividend?
Kilroy Realty (KRC) just reaffirmed its regular cash payout, with the board declaring a US$0.54 quarterly dividend per share (US$2.16 annually), alongside an investor-facing appearance at BofA’s Global Real Estate Conference.
The reaffirmed payout lands against a softer tape for Kilroy Realty, with the latest 30 day share price return down 6.4% and the year to date share price return down 10%, even as the 3 year total shareholder return sits in positive territory. Recent pressure, including a 7.5% decline in the 90 day share price return and a 17.8% fall in the 1 year total shareholder return, suggests sentiment has cooled. The fresh dividend decision and conference appearance give investors new reference points for reassessing both income reliability and perceived risk around the portfolio.
Compare Kilroy Realty's recent dividend and share price pressure with hand picked income ideas across real estate and beyond by scanning 7 dividend fortresses.
Kilroy Realty now trades below both analyst targets and one DCF based estimate, after a steady share price pullback. Is the current discount compensation for risk, or does it reflect a gap to underlying value?
Most Popular Narrative: 14% Undervalued
Kilroy Realty's most followed valuation narrative pegs fair value at $39.93, above the $34.23 last close. This puts the current share price on the wrong side of that estimate and makes the underlying assumptions worth understanding.
Industry-wide stagnant or declining rents and persistent tenant downsizing trends accelerate vacancy, necessitating costly repositioning of assets and increasing capital requirements, which will constrain FFO growth and elevate refinancing risks in a risk-averse capital market.
See why 14 investors see Kilroy Realty as 14% undervalued.
Result: Fair Value of $39.93 (UNDERVALUED)
Still, faster leasing in San Francisco or stronger demand for Kilroy Realty's life science projects could tighten vacancies and challenge the idea that the stock deserves a discount.
Find out about the key risks to this Kilroy Realty narrative.
Another View on Kilroy Realty’s Valuation
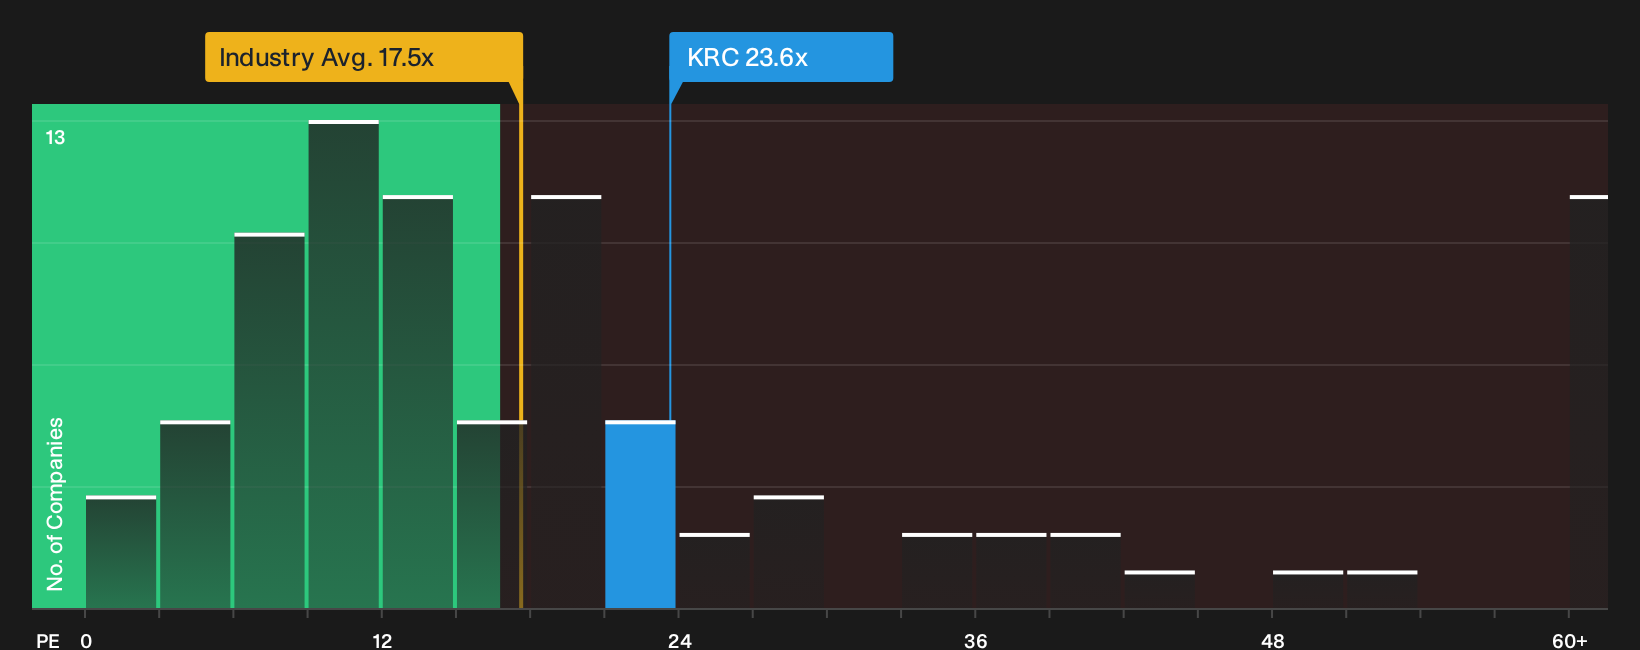
The earlier narrative leans on discounted cash flows and concludes Kilroy Realty looks undervalued, yet the P/E picture is less forgiving. KRC trades on about 23.6x earnings compared with 17.5x for the global Office REITs group and a fair ratio of 22x. This points to a premium that could limit upside if sentiment softens.
That mix of perceived discount on future cash flows and premium on today’s earnings leaves a simple question for you as an investor: Which lens feels more realistic for how this stock might be priced over the next few years, the cash flow model or the earnings multiple?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Kilroy Realty's valuation and income profile do not need to leave you on the fence. Move quickly, test the assumptions against your own expectations, and weigh the 2 key rewards and 4 important warning signs
Hunting For More Ideas Beyond Kilroy Realty?
Do not stop your research with Kilroy Realty. Broaden your opportunity set and pressure test your thesis by lining it up against fresh ideas from the Simply Wall St screener.
- Target resilient income by scanning companies designed to keep paying investors even when conditions feel tough through the 7 dividend fortresses.
- Spot potential value gaps by comparing what you pay today with business quality and balance sheet strength using the 35 high quality undervalued stocks.
- Prioritise sleep at night potential by filtering for companies that pair solid finances with lower risk profiles through the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com