


ZIM Integrated Shipping Services (ZIM) Beat Expectations, Is The Stock Already Fully Valued?
What ZIM’s Earnings Beat Tells You Right Now
ZIM Integrated Shipping Services (ZIM) just posted second quarter 2026 results that topped expectations, with adjusted earnings of $0.64 per share and solid Pacific trade volume growth of 20.3%.
Management is also signaling a stronger second half for adjusted EBITDA and EBIT. This puts the recent performance in the Pacific region at the center of the investment debate.
ZIM Integrated Shipping Services has seen momentum build over 2026, with a 30 day share price return of 6.55%, a 90 day gain of 19.11% and a year to date move of 37.38%. The 1 year total shareholder return of 119.87% and 3 year total shareholder return of more than 3x signal how strongly recent news and earnings shifts have fed into both price action and investor expectations for risk and reward.
Scan how ZIM Integrated Shipping Services fits alongside other freight and logistics plays by reviewing a curated set of list of solid balance sheet and fundamentals (23 results) aligned with similar fundamentals and resilience.
ZIM Integrated Shipping Services now looks like a healthier operator with a hot Pacific trade lane and a share price that has rerated hard. The open question is whether that recent surge still leaves enough value on the table.
Most Popular Narrative: 6% Overvalued
The most followed narrative currently pegs fair value for ZIM Integrated Shipping Services at $28.30, which sits below the last close of $30.10, and frames the recent surge as slightly ahead of where the long term math lands.
Substantial orderbook-induced industry overcapacity, as highlighted by management's comments on ongoing supply growth, poses a persistent risk to freight rates and load factors, undermining long-term revenue growth assumptions, especially in the absence of strong demand or meaningful scrapping. ZIM's asset-light charter-heavy model, while offering operational flexibility in theory, exposes the company to elevated fixed costs and higher charter expenses in volatile markets; with 250,000 TEUs coming up for renewal, there is downward risk to margins and free cash flow should market conditions worsen, contrary to expectations of stable or expanding profitability.
See why 92 investors see ZIM Integrated Shipping Services as 6% overvalued.
The narrative uses a 12.17% discount rate and builds out to a fair value of $28.30, which sits about 6% below the current share price and implies that recent optimism prices in more than the consensus earnings and margin path would support on its own.
Result: Fair Value of $28.30 (OVERVALUED)
Still, a modernized LNG powered fleet and broader exposure beyond China U.S. routes could challenge this overvalued narrative if earnings resilience improves faster than expected.
Find out about the key risks to this ZIM Integrated Shipping Services narrative.
Another View on ZIM Integrated Shipping Services’ Valuation
The analyst narrative tags ZIM Integrated Shipping Services as slightly overvalued around $30.10 compared with a $28.30 fair value. Our DCF model points in the opposite direction, with an implied value of $153.36 per share, which is roughly 80% above the current quote. That sort of gap raises a simple question: Which set of assumptions do you trust more, the cautious earnings path or the long term cash flow story?
Look into how the SWS DCF model arrives at its fair value.
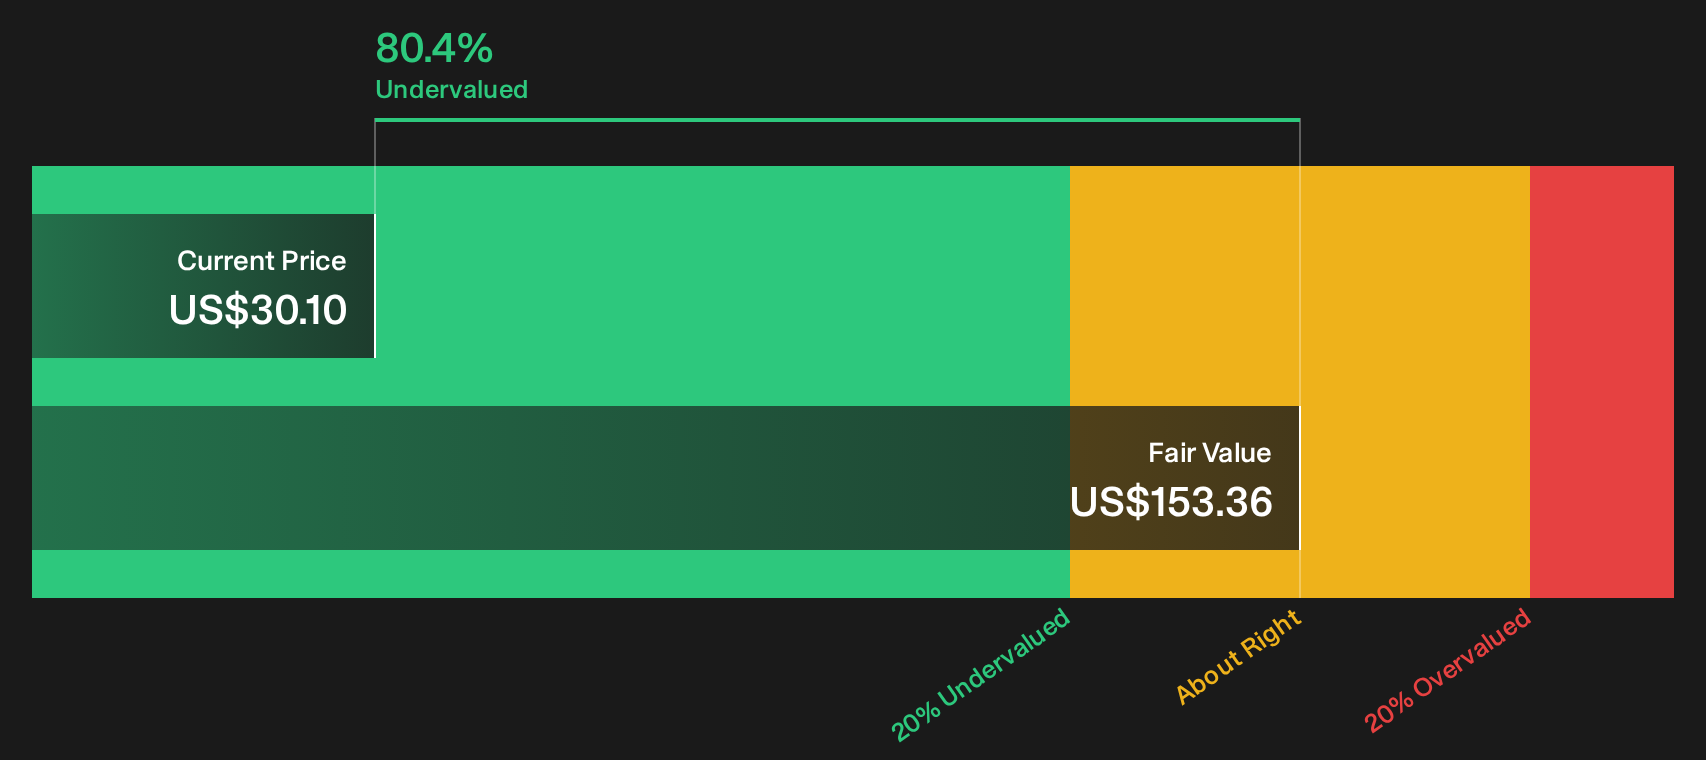
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ZIM Integrated Shipping Services for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views like these only matter if they push you to check the numbers yourself and decide where you stand. Take a few minutes to weigh both the upside and the downside by reviewing the 1 key reward and 4 important warning signs
Looking For More Ideas Beyond ZIM Integrated Shipping Services?
Do not stop your research with ZIM Integrated Shipping Services. Broaden your watchlist with a few focused stock ideas that match different risk and return preferences.
- Target potential mispricing by reviewing a curated set of 35 high quality undervalued stocks that combine quality fundamentals with compressed expectations.
- Strengthen your income plan by scanning 7 dividend fortresses that aim to pair higher yields with resilient cash generation.
- Dial down portfolio risk by filtering for 30 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com